
Who Is Winning the Onchain Gacha Trade
Key Takeaways
- Onchain gacha processes hundreds of millions of dollars in collectibles volume a month, but keeps only a fraction as revenue. Collector Crypt, Courtyard, Phygitals, Beezie, and Monster recorded $284.3 million of gross gacha activity in July 2026 and returned $249.4 million to consumers through buybacks, leaving $34.9 million of revenue after buybacks.
- Combined gross gacha activity fell 17.5% in July to $284.3 million from a record $344.4 million in June. Collector Crypt declined 25.9%, Phygitals 31.9%, and Beezie 30.0%. Courtyard grew 6.8% and Monster 14.6%. Only Courtyard sold more packs, up 22.8%. Monster’s growth came from price, with 8.0% fewer packs at a 24.5% higher average.
- Buybacks returned 87.7% of July gross gacha activity, and since consumers can respend that credit, gross activity counts the same dollar more than once. Measured by revenue after buybacks, Courtyard earned nearly twice as much as Collector Crypt on just over half the volume.
- Partner surfaces supplied 25.9% of Collector Crypt’s July activity, and those partners own the consumer relationships. Excluding them, activity declined 42.1% month-over-month (MoM). The Jupiter integration behind most of that volume decayed 68% within three weeks of launch, which leaves the largest platform’s volume lead dependent on channels it does not control.
- All five platforms operate a secondary marketplace. Only Courtyard's clears at retail scale, with independent buyers taking volume equal to 6.2% of its gacha activity in July. The others mostly bid on their own inventory. Team repurchases accounted for 85.5% of Beezie’s secondary volume, and Collector Crypt’s own buyback bid accounted for just under half of its marketplace volume. Independent buyers reduce the exits a platform funds itself and the inventory it takes back.
- Whether revenue after buybacks actually becomes profit cannot be determined from the available data. Revenue after buybacks is stated before the cost of the collectible, grading, custody, insurance, fulfillment, payment processing, and operating expense. Acquisition cost, resale proceeds, holding periods, and operating expense are not available for all five on a comparable basis, so this report does not compare them.
Introduction
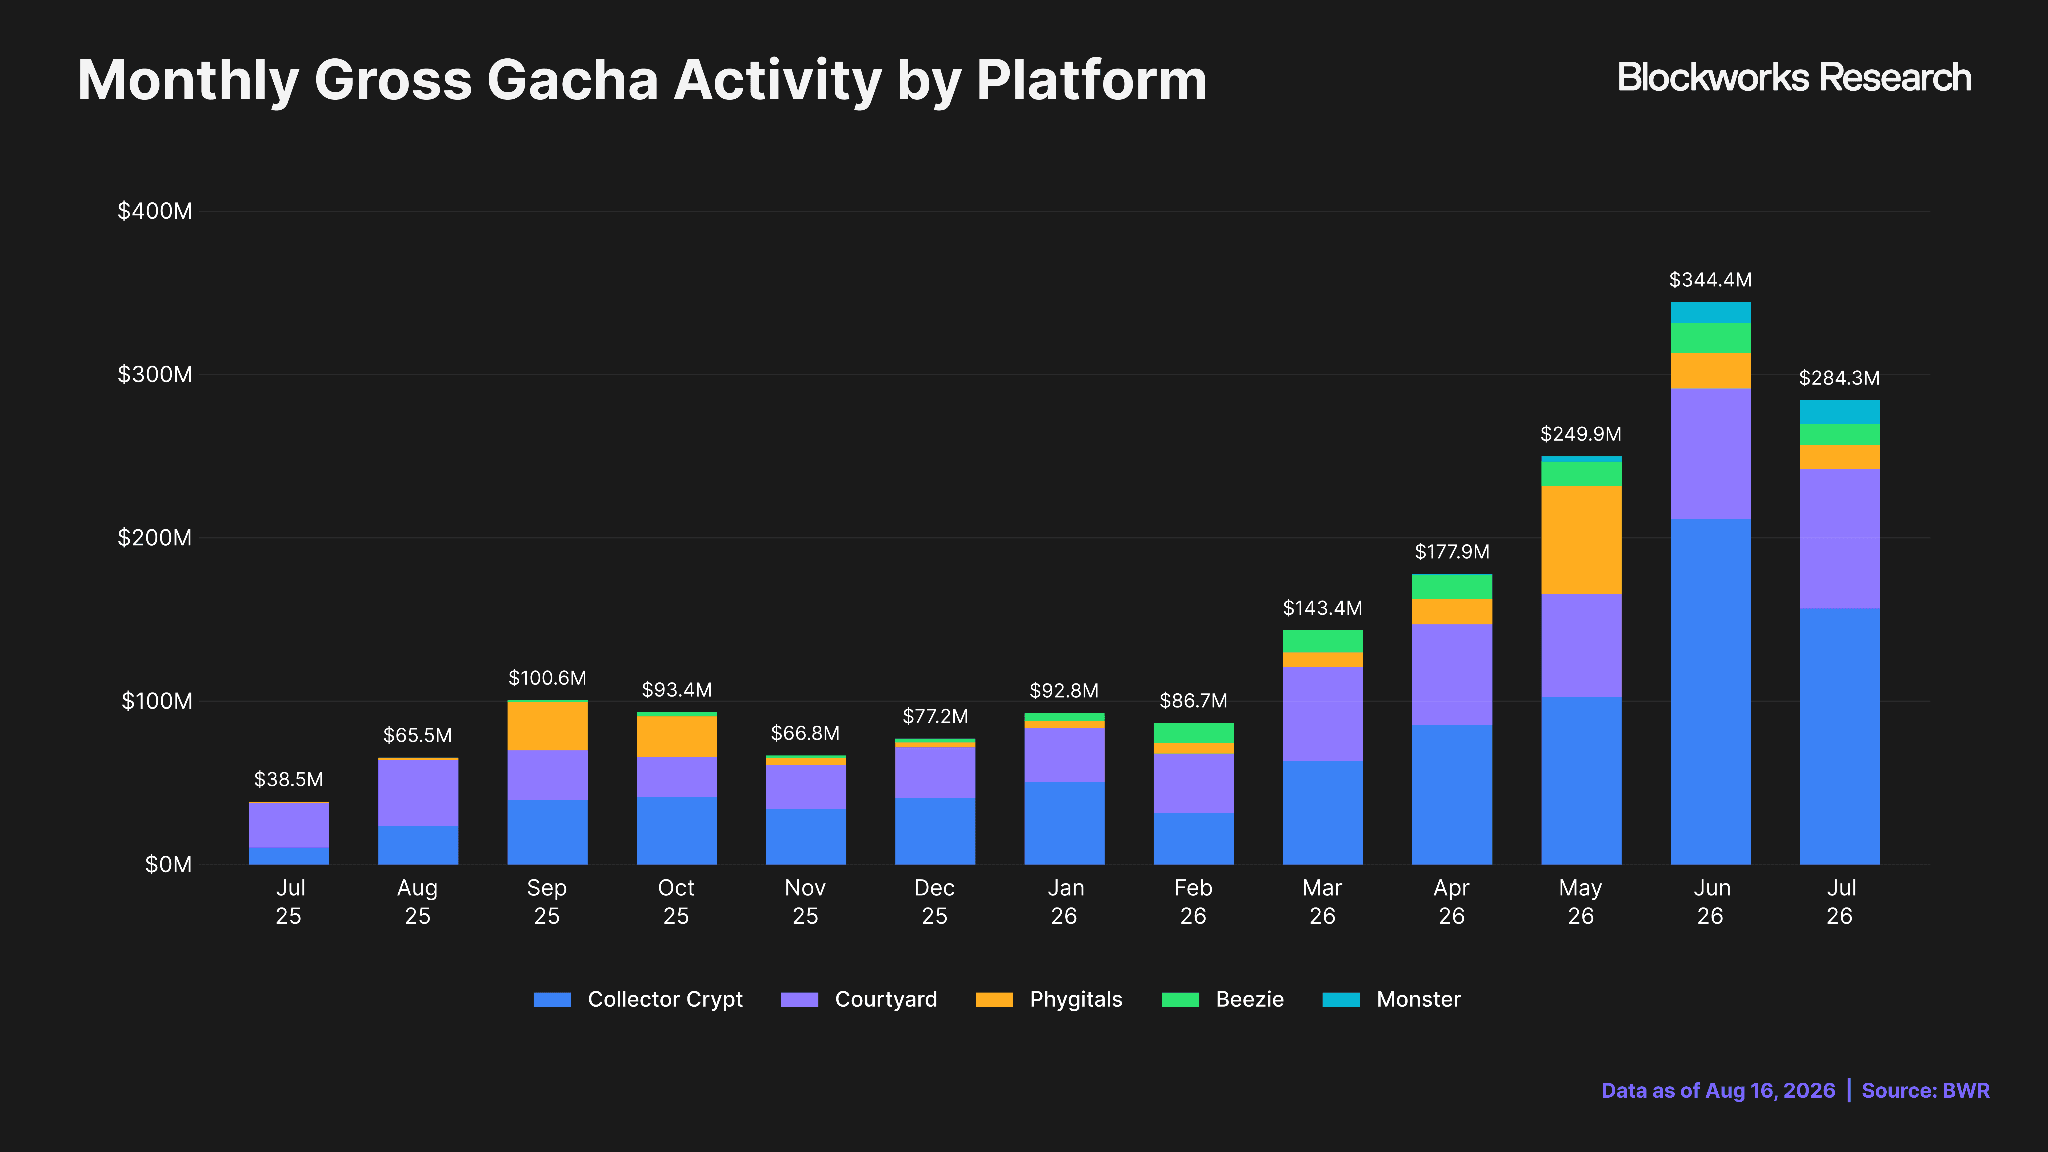
Onchain gacha reached the scale of an established collectibles marketplace in mid-2026 without the revenue that scale implies. Collector Crypt, Courtyard, Phygitals, Beezie, and Monster processed $284.3 million of gross gacha activity in July 2026 and returned $249.4 million to consumers through buybacks, leaving just $34.9 million. The five platforms moved more gross activity in July than eBay’s entire market for single trading cards averaged per month in 2025, though gross activity counts recycled buyback credit while eBay's figure does not.
A collectibles marketplace matches buyers with sellers and collects a fee. A gacha platform sells a randomized pack and then offers to buy back whatever comes out of it. Four of the five platforms fund almost every consumer exit from their own balance sheet, returning between 89.0% and 97.9% of purchase value. Courtyard’s realized ratio was 75.6%, and its 84.6% effective quote is the lowest in the category. It clears more exits through independent buyers than the other four combined. Collector Crypt leads on gross activity, while Courtyard earns nearly twice its revenue after buybacks on just over half the volume.
Revenue after buybacks is what a platform keeps from a pack after funding the exit, which makes it arithmetically identical to what a consumer gives up each time they buy a pack and sell the cards back. A higher figure means more revenue per dollar of consumer spend, and less of that dollar returned to the consumer. It says nothing about what the platform earns after its own costs. This report compares Collector Crypt, Courtyard, Phygitals, Beezie, and Monster on July 2026 activity, buyback intensity, consumer composition, marketplace liquidity, inventory position, and distribution ownership. It ranks them on observable business performance, but not on consumer value or profitability, neither of which the available data can settle. It also examines why gacha revenue is economically different from asset-light protocol revenue, which capabilities can become moats, and which conditions would change our ranking of the five platforms.
The Size of the Opportunity
Onchain gacha competes for demand that web2 platforms such as eBay and GameStop already serve. eBay’s trading card fee revenue shows what the largest single online channel earns from the same activity; GameStop runs the same buyback model without a blockchain, and eBay's sale of its vault to PSA shows what vaulted custody is worth on its own.
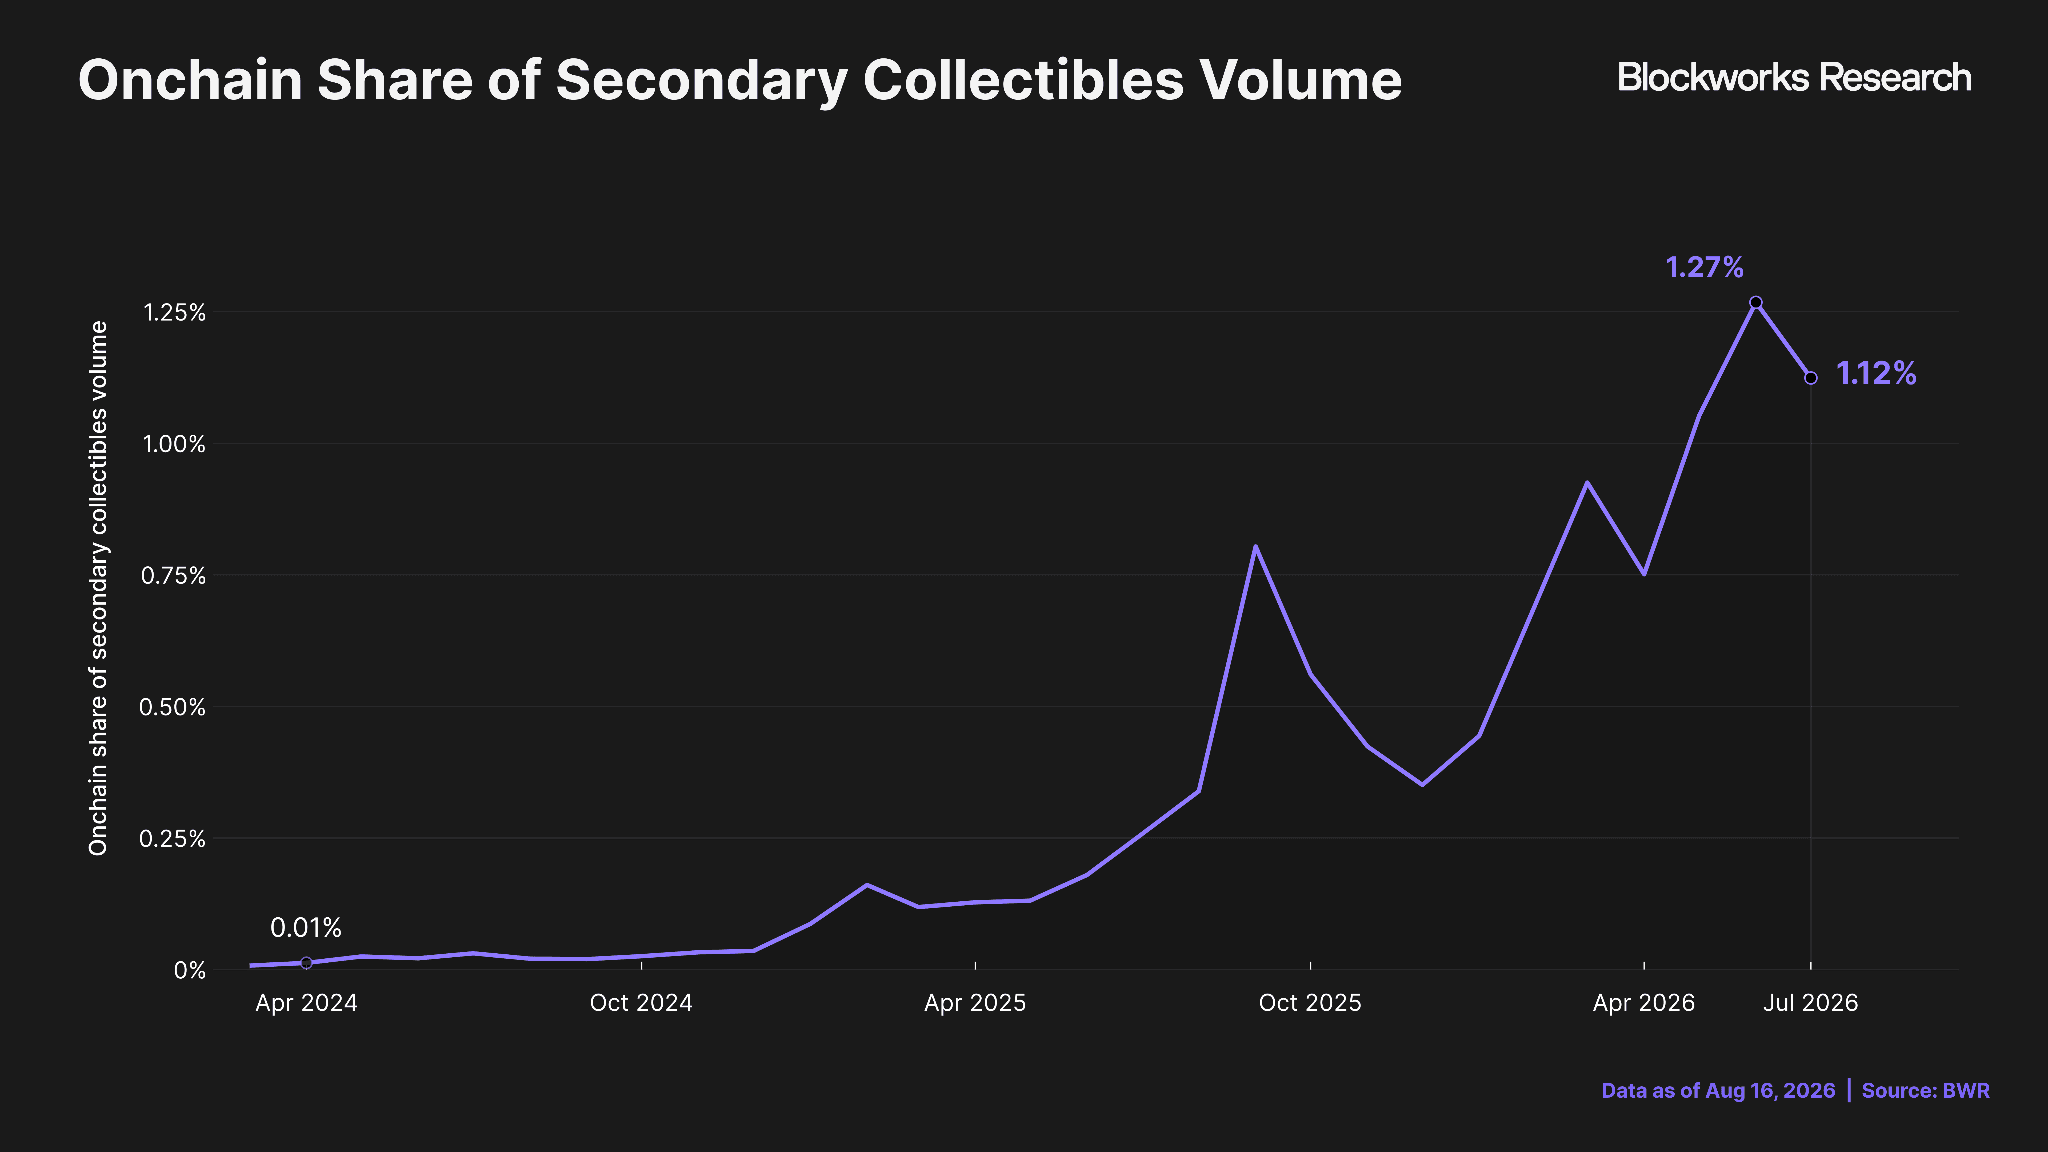
Onchain platforms sold $7.9 million of cards on their own secondary marketplaces in July, compared with $702.6 million across the broader resale market. That is a 1.12% share of card resale, up from 0.01% in April 2024. Close to 90x growth in 27 months still leaves the category a rounding error of the resale market it competes in.
eBay is the best available benchmark for scale, because it is the largest single online channel serving the same demand and its revenue from that channel can be estimated from public data. It does not disclose trading card revenue, so we have to construct the figure. GemRate, which tracks graded card sales, counted $2.62 billion of single cards sold on eBay in 2025, and eBay charges a 13.25% final value fee on trading cards. Applying the fee to the volume produces roughly $347 million of annual marketplace revenue from that channel, before per-order fees, advertising revenue, cards sold in lots or sealed, the lower rate above $7,500 per item, and any category-level fee variance eBay does not disclose.
The five largest onchain gacha platforms produced $34.9 million of revenue after buybacks in July, or around $418 million at an unadjusted annual run rate. The category has reached the revenue scale of the largest single online trading card channel in under two years.
Three factors limit what the revenue comparison proves.
First, the annualization is unsound as a forecast. Monthly category activity has moved by more than 25% in six of the past twelve months, and a sixth of the largest platform’s July activity came from a single integration that decayed 68% within three weeks of launch.
Second, revenue comes from a different cost structure. eBay collects a fee and holds no inventory. Onchain gacha platforms buy the collectibles, package them, fund the exits, and carry returned assets. GameStop is the closer comparable on cost, because unlike eBay, it owns the goods it sells, accepts PSA grading submissions across its store base, and runs a graded-card trade-in program that functions much like a buyback. Its collectibles net sales rose 47.7% in FY2025 to $1.06 billion, and collectibles reached 41.8% of GameStop's total net sales in Q1 FY2026, which shows the model scales without tokenization. GameStop also runs the gacha product itself. Power Packs, launched in April 2026, sells randomized digital packs from $25 to $2,500 that unlock PSA-graded cards held in the PSA Vault, with an instant buyback priced off Card Ladder’s sales database. Sale proceeds are credited to a wallet that can be spent on further packs.
Third, tokenization reduces only part of the friction. It compresses custody, settlement, resale, and cross-border distribution, since a vaulted graded card can change hands without being reshipped, reauthenticated, or reinsured. It does not compress sourcing, grading, authentication, or physical fulfillment, which remain the expensive parts. eBay’s decision to sell its Vault to PSA in May 2024, after launching it in 2022, is the clearest available evidence that vaulted custody is an expense to be managed rather than a durable advantage. eBay kept the marketplace, kept the 13.25% fee, and handed the vault to the grader.
Onchain gacha’s revenue is earned against incumbents who own the distribution, authentication, and physical fulfillment where most of the cost sits, and through a mechanism that compresses none of those functions. Tokenization by itself does not explain why any of these platforms should win. The differences that might are in distribution, product design, and the structure of secondary-market liquidity.
The Onchain Competitive Landscape
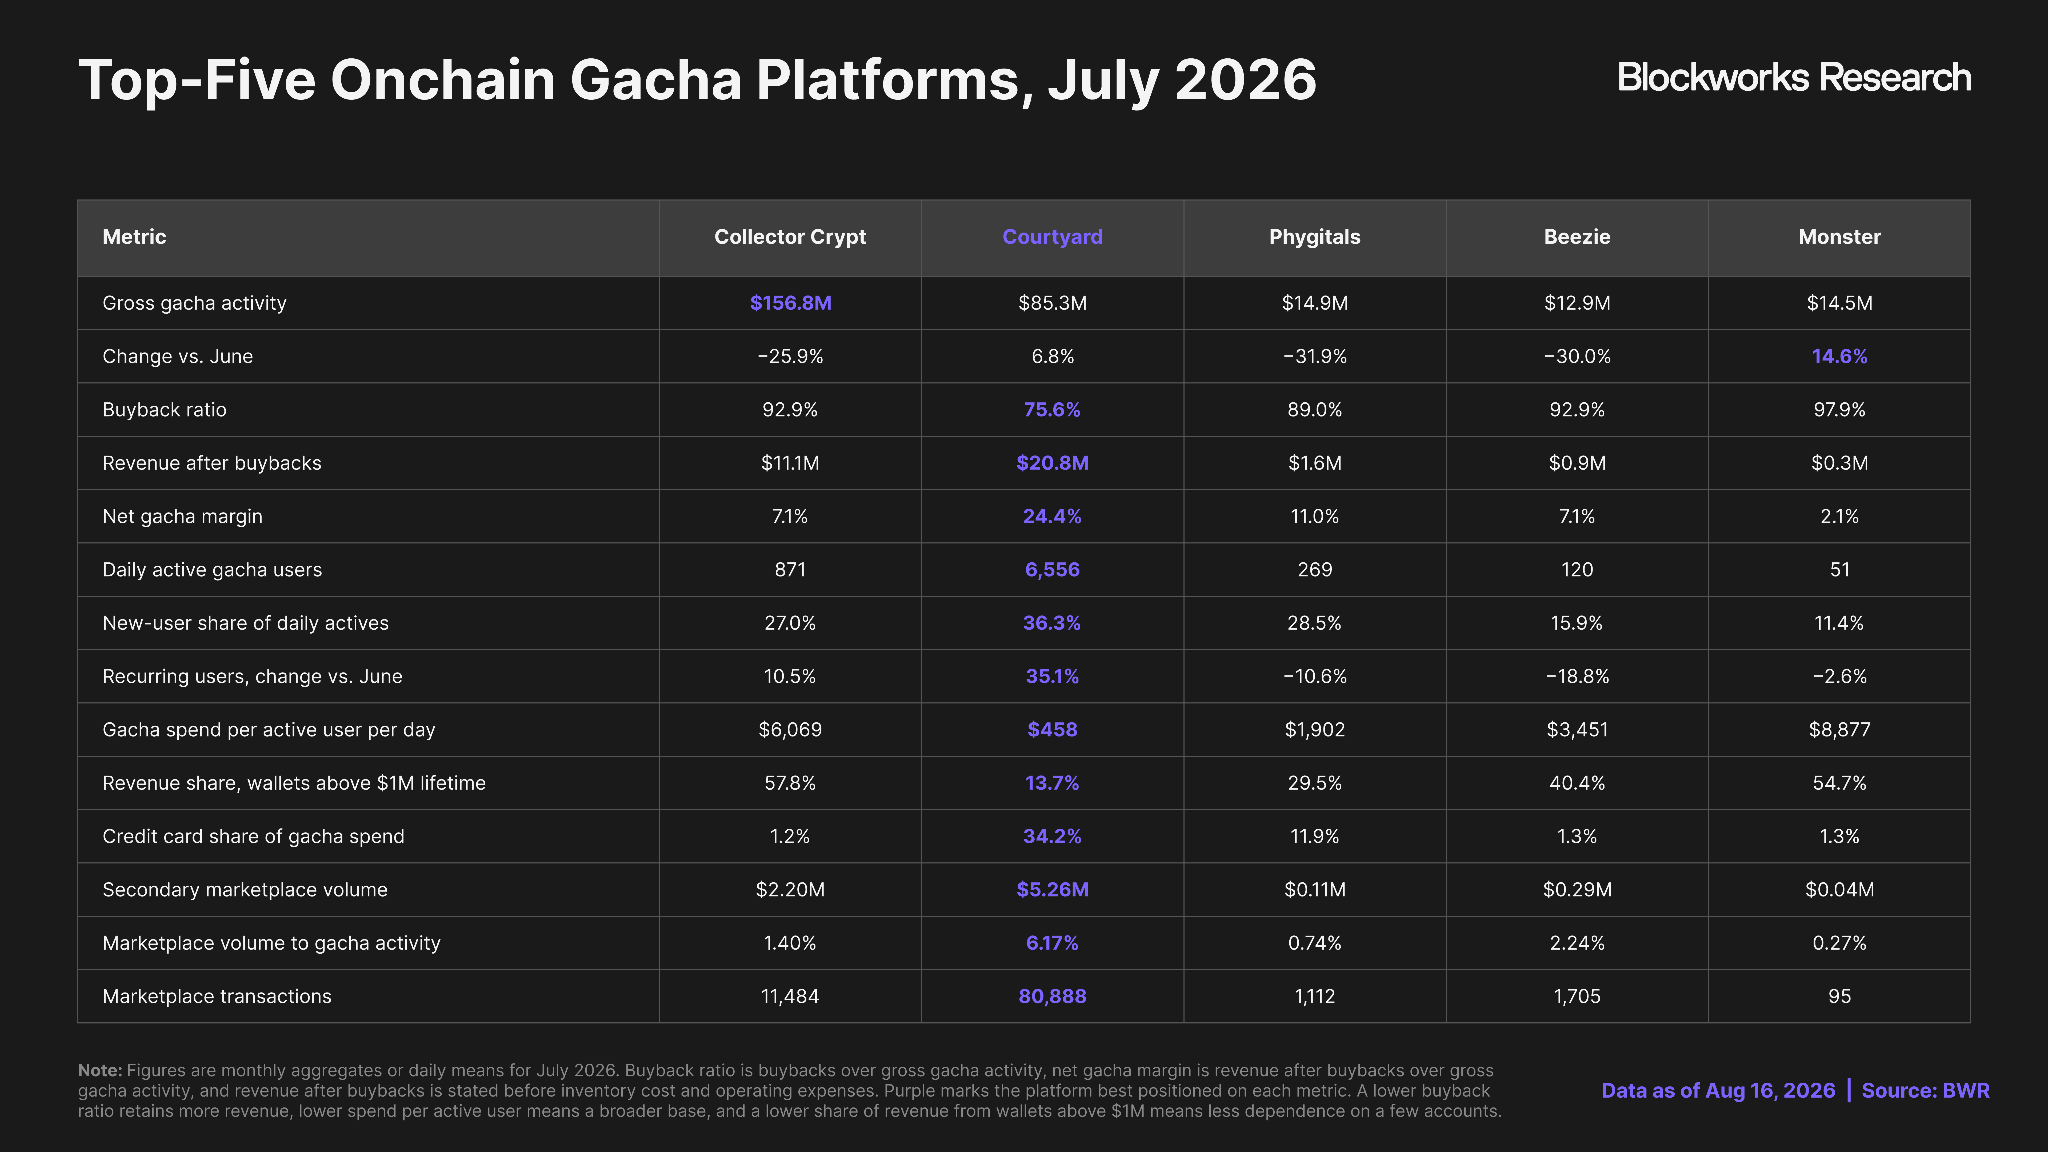
Collector Crypt has the largest gross activity in the category and the most concentrated revenue. 57.8% of its revenue comes from wallets with lifetime spend above $1 million, which are 0.65% of its users. Its 871 daily active users spent an average of $6,069 each per day. It runs gacha across six categories, spanning Pokémon, One Piece, sports, sealed product, anime, and comics, though Pokémon supplied 80.8% of July pack spend. It operates on Solana, and roughly a quarter of its activity arrives through partner surfaces rather than its own.
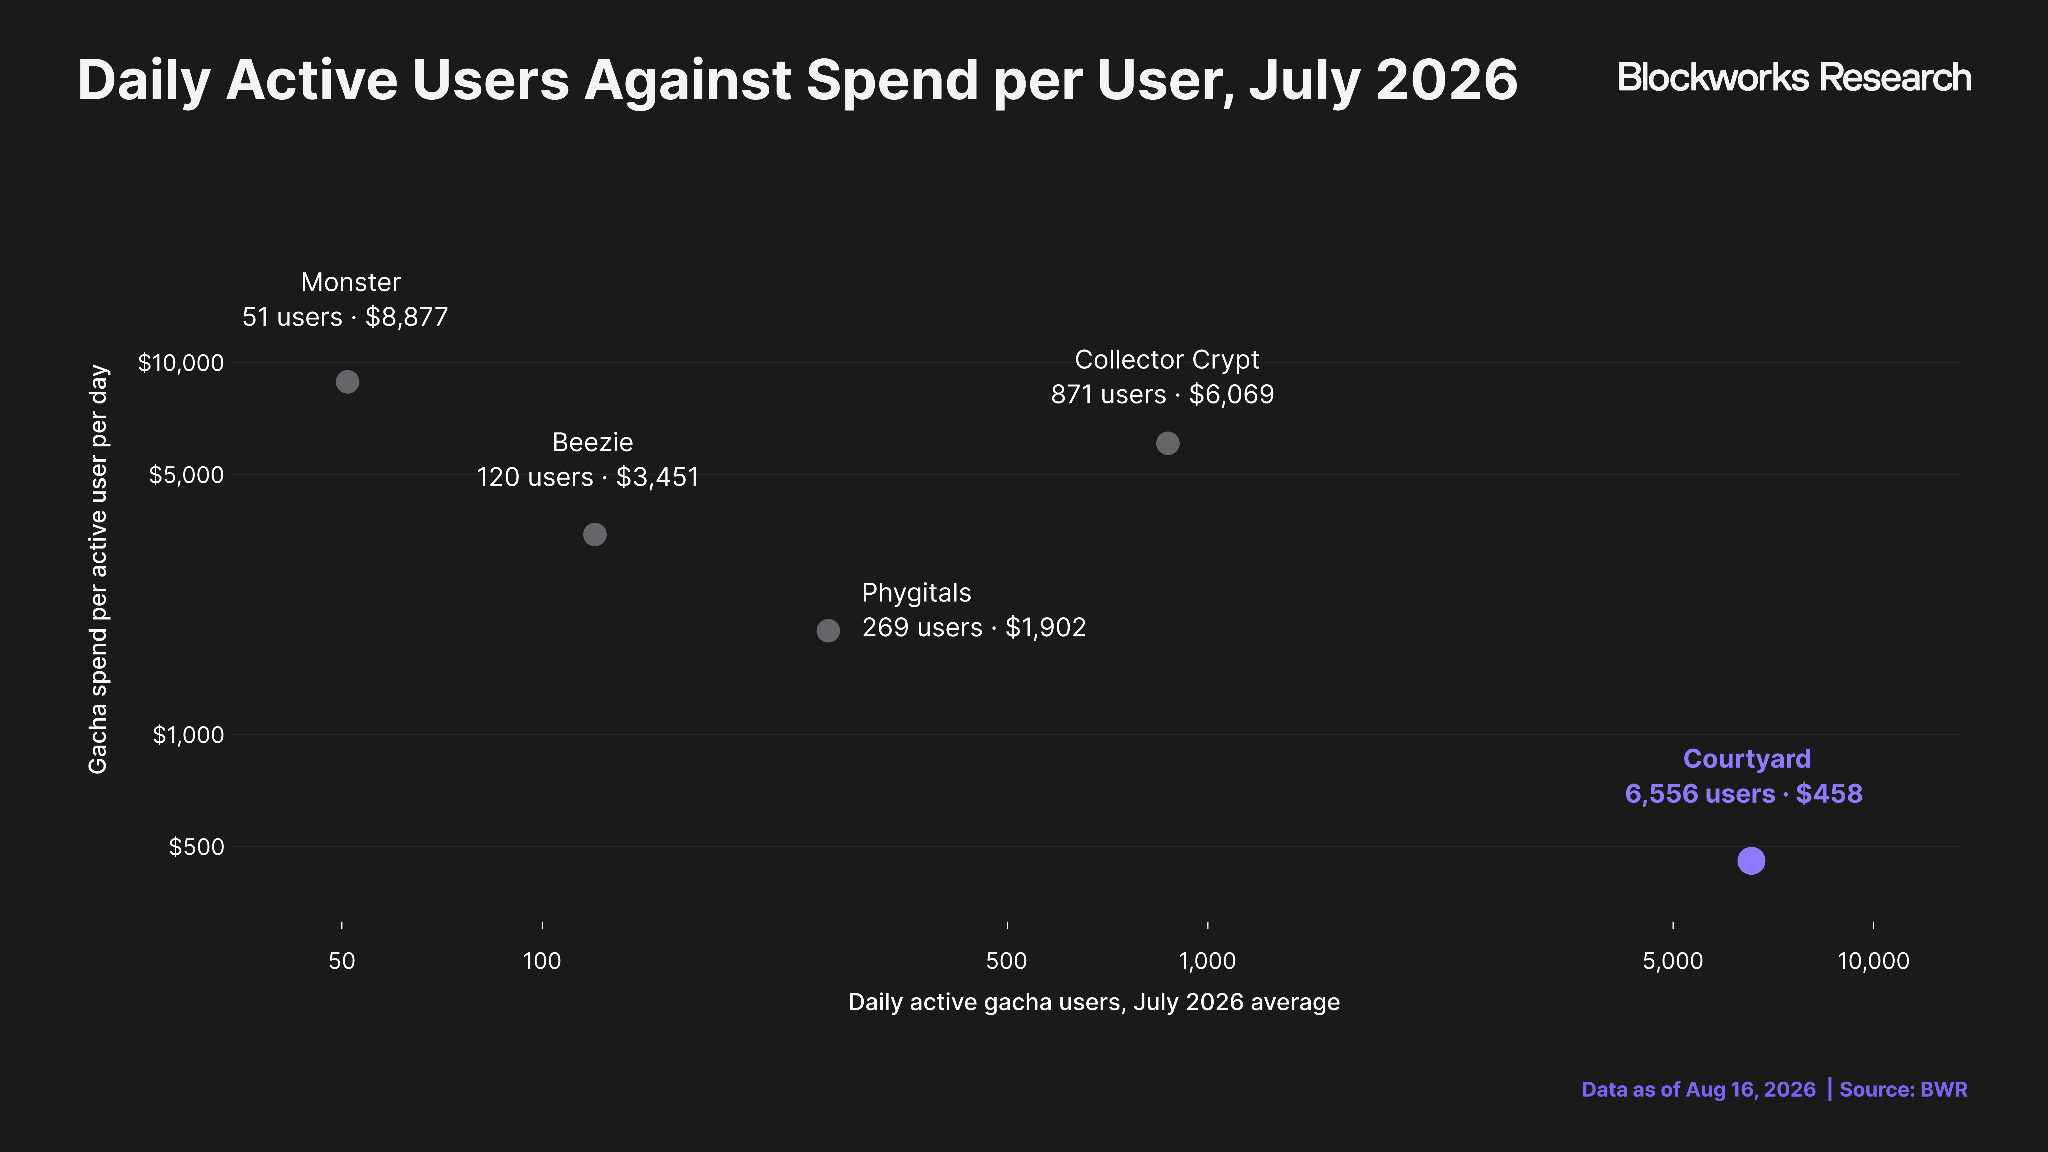
Courtyard operates a retail marketplace with a gacha front end. Gross activity grew 6.8% MoM in July to $85.3 million, its highest month to date. It had 6,556 daily active users in July, each spending an average of $458 a day, which is 7.5x Collector Crypt's consumer base at a thirteenth of the spend per consumer. Its revenue is the least concentrated in the group, with 13.7% coming from wallets above $1 million lifetime. Its marketplace cleared 80,888 transactions in July, 47x Beezie’s count and 73x Phygitals’.
Phygitals is contracting fastest. Gross activity fell 32.0% MoM in July to $14.9 million, and 77.5% from May’s $66.2 million. Its native marketplace fell 76.4% MoM to $110,673, and 88.4% across the same two months. It runs on Solana and operates a storefront on Fanatics Collect, one of the largest trading card secondary marketplaces, with cross-listing that lets a card sell on either venue. The partnership has been live since April 2026, but it has not slowed the decline in the activity this report can measure. Fanatics volume is offchain and outside this dataset, and Phygitals’ storefront listings there are concentrated in a couple hundred low-value slabs.
Beezie has the smallest gross activity in the group, and it ends up on the buying side of both exits. A user can sell a card back through the buyback or list it on Beezie’s marketplace, but in July Beezie’s own balance sheet funded most of both. Its 92.9% buyback ratio matches Collector Crypt's, and 85.5% of its marketplace volume came from its own team repurchasing inventory. Gross activity fell 30.0% MoM in July to $12.9 million from June’s record $18.4 million, its first monthly decline since November, when activity was $1.6 million. Of its 120 daily active users, only 15.9% were new, the second-lowest in the group behind Monster’s 11.4%. Recurring users also fell 24.8% on Base between June and July, so the retained base is shrinking rather than compounding. It originally launched on Flow, then expanded to Base in December 2025 and Solana in May 2026.
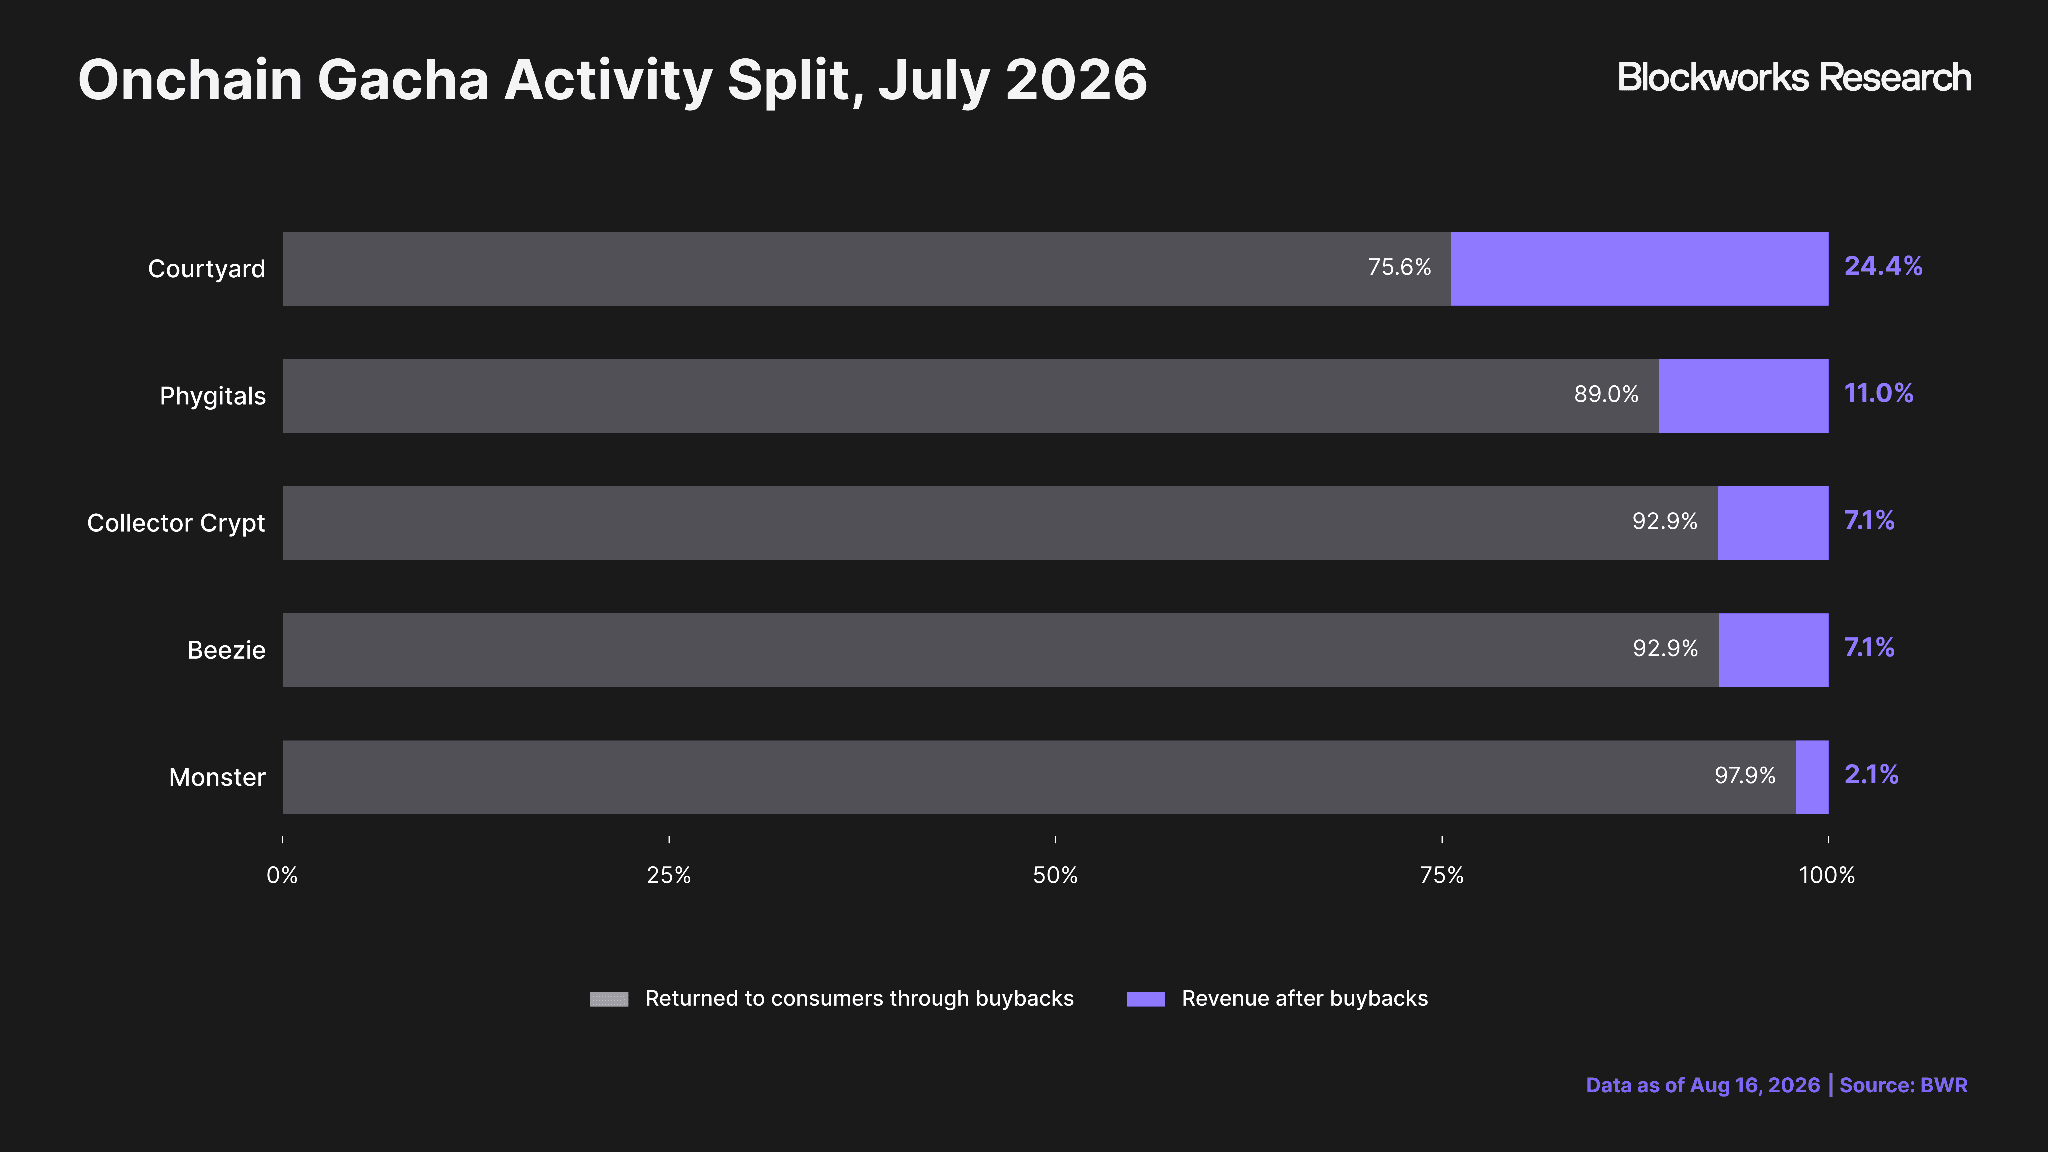
Monster is the category’s most concentrated platform and the most aggressive buyer of its own volume. It grew 14.6% MoM in July to $14.5 million, its highest month since launching on MegaETH, but returned 97.9% of that through buybacks, the highest ratio in the group, leaving $304,295 at a 2.1% net gacha margin. Its 51 daily active users spent $8,877 each per day, the most in the category, and 54.7% of its revenue came from 0.52% of its wallets. It added an average of 5.8 new users a day in July, compared with Courtyard’s 2,382 a day.
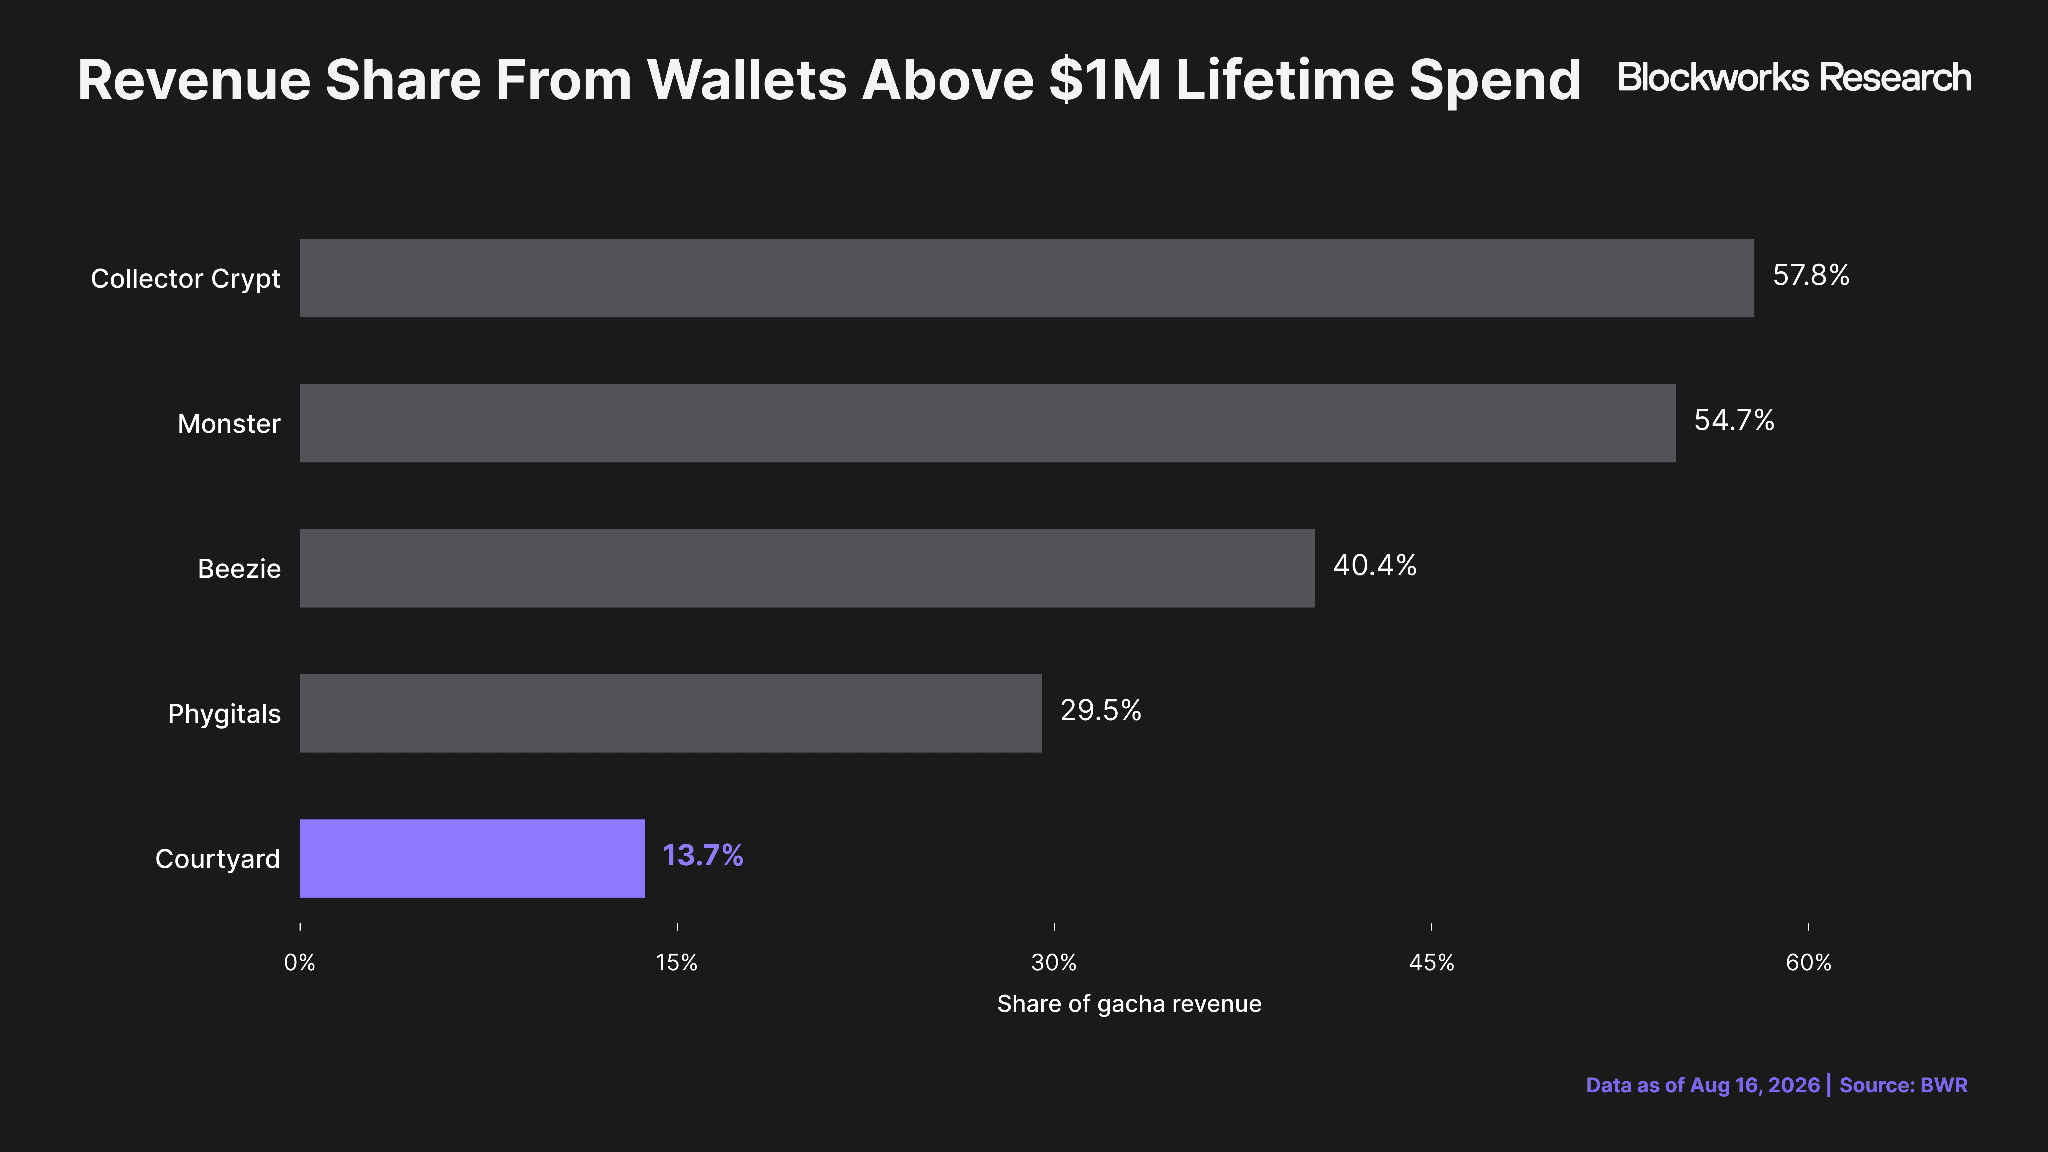
Collector Crypt’s $156.8 million and Courtyard’s $85.3 million are not comparable dollars. Collector Crypt reflects several hundred daily accounts recycling balances through a 92.9% buyback across partner surfaces. Courtyard reflects several thousand retail accounts buying packs and trading the cards with each other at an average sale price of $65. Those differences in activity composition, monetization, and liquidity shape which platform is performing most strongly.
Who Is Winning and Why
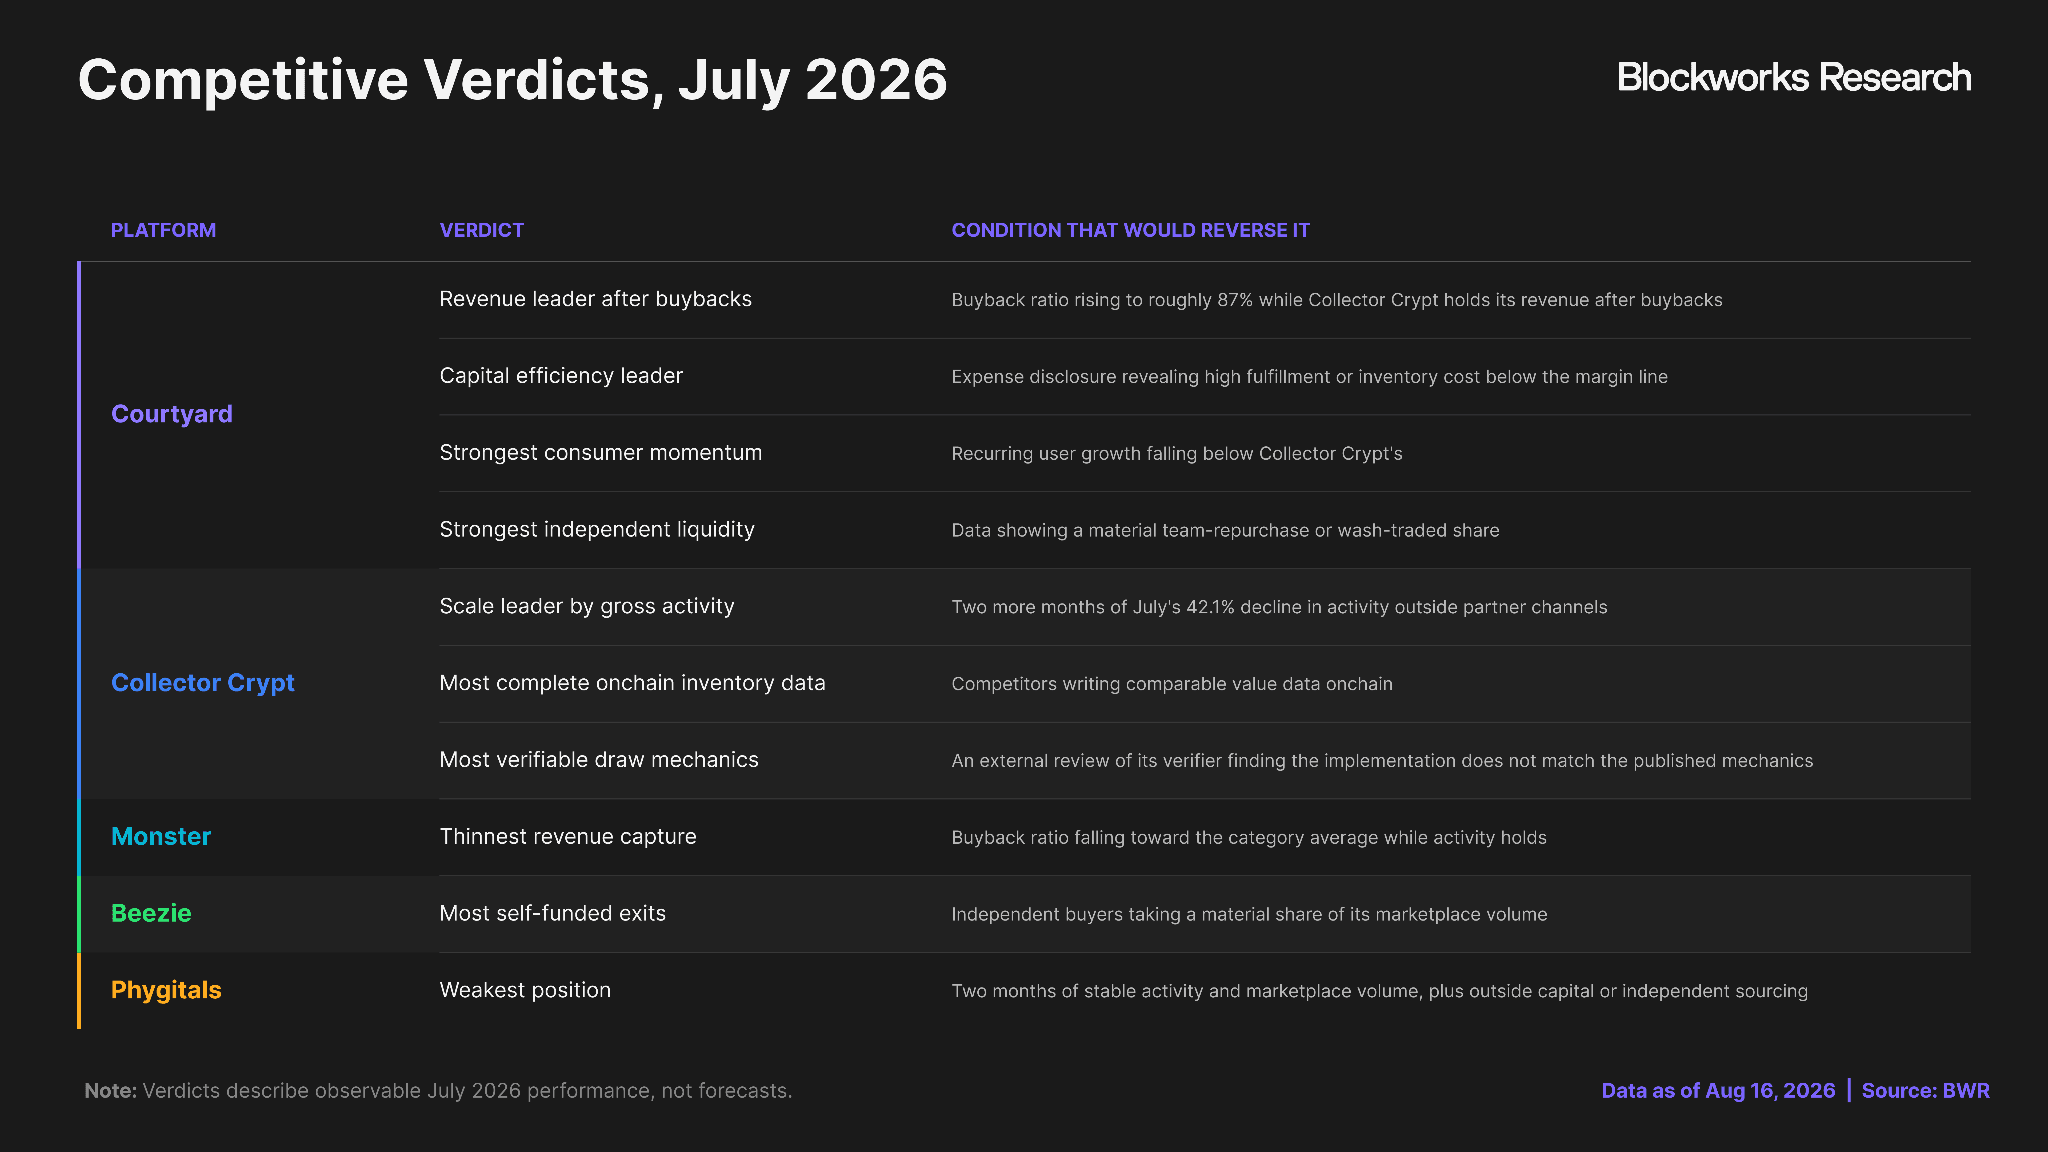
Courtyard is the observable leader on every performance measure except gross activity. It earned the most revenue after buybacks, and its users opened 22.8% more packs in July, the only unit growth in the category, though at a 13.1% lower average pack price of $77.22 against $88.82 in June. Its recurring consumer count rose 35.1% MoM against Collector Crypt’s 10.5%, its new users rose 128% against Collector Crypt’s 51%, and its daily active users rose 59% against Collector Crypt’s 19%. Courtyard also operates the only secondary market in the group at retail scale. Its 24.4% net gacha margin is more than 3x the margin at Collector Crypt and Beezie, 2.2x Phygitals’, and 11.6x Monster’s.
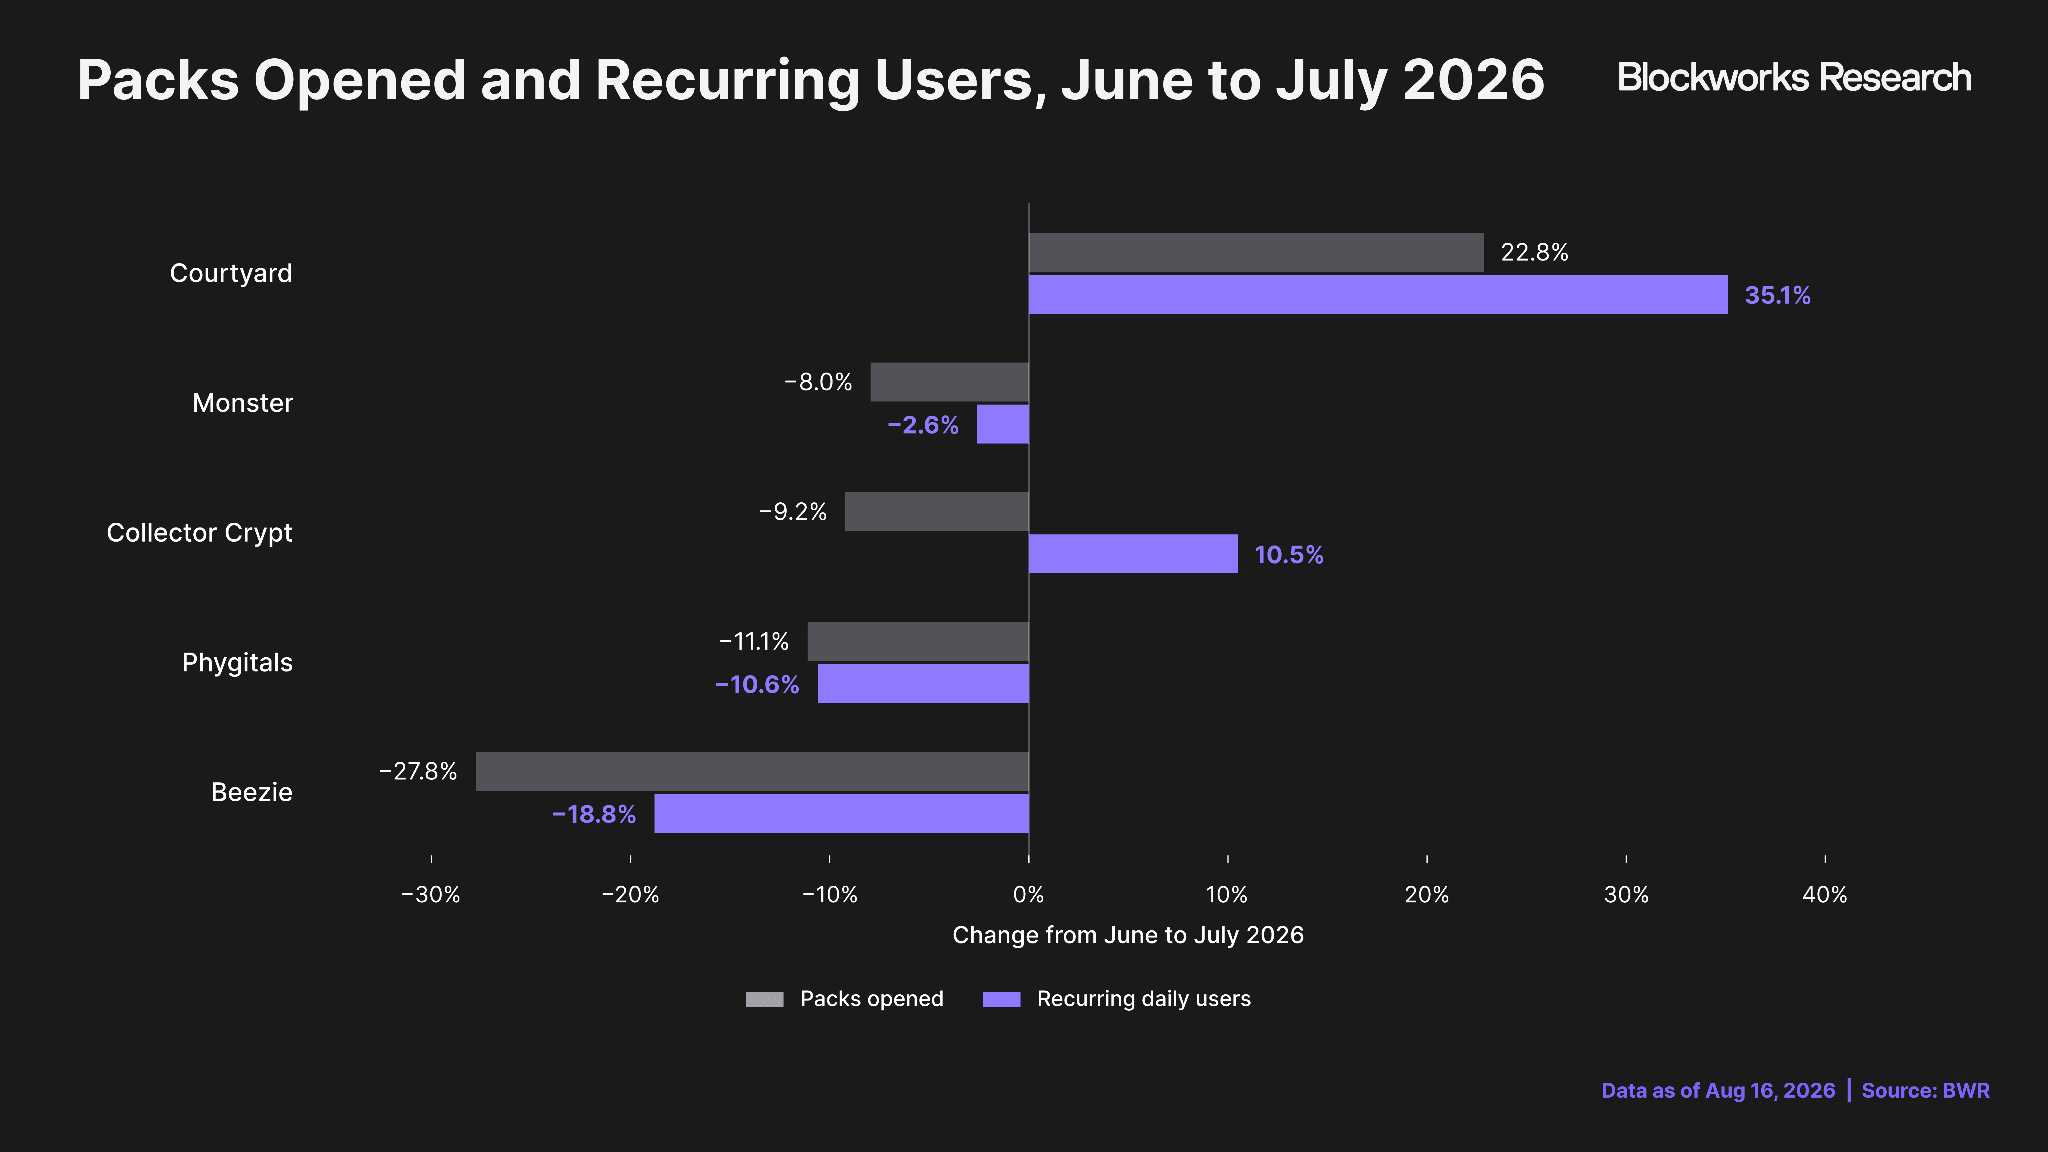
Those results come from who Courtyard is selling to. Courtyard has the category’s largest web2 base, and its customers trade cards with each other at a scale no other platform reaches. A low buyback quote gives a consumer a reason to keep or resell rather than sell back. A zero-fee marketplace serves someone selling to another buyer, and although all five platforms accept card payments, Courtyard’s consumers use them at multiples of the rates seen elsewhere. Each choice selects for the collector and against the trader, and the collector is the customer whose activity does not disappear when another sector starts performing.
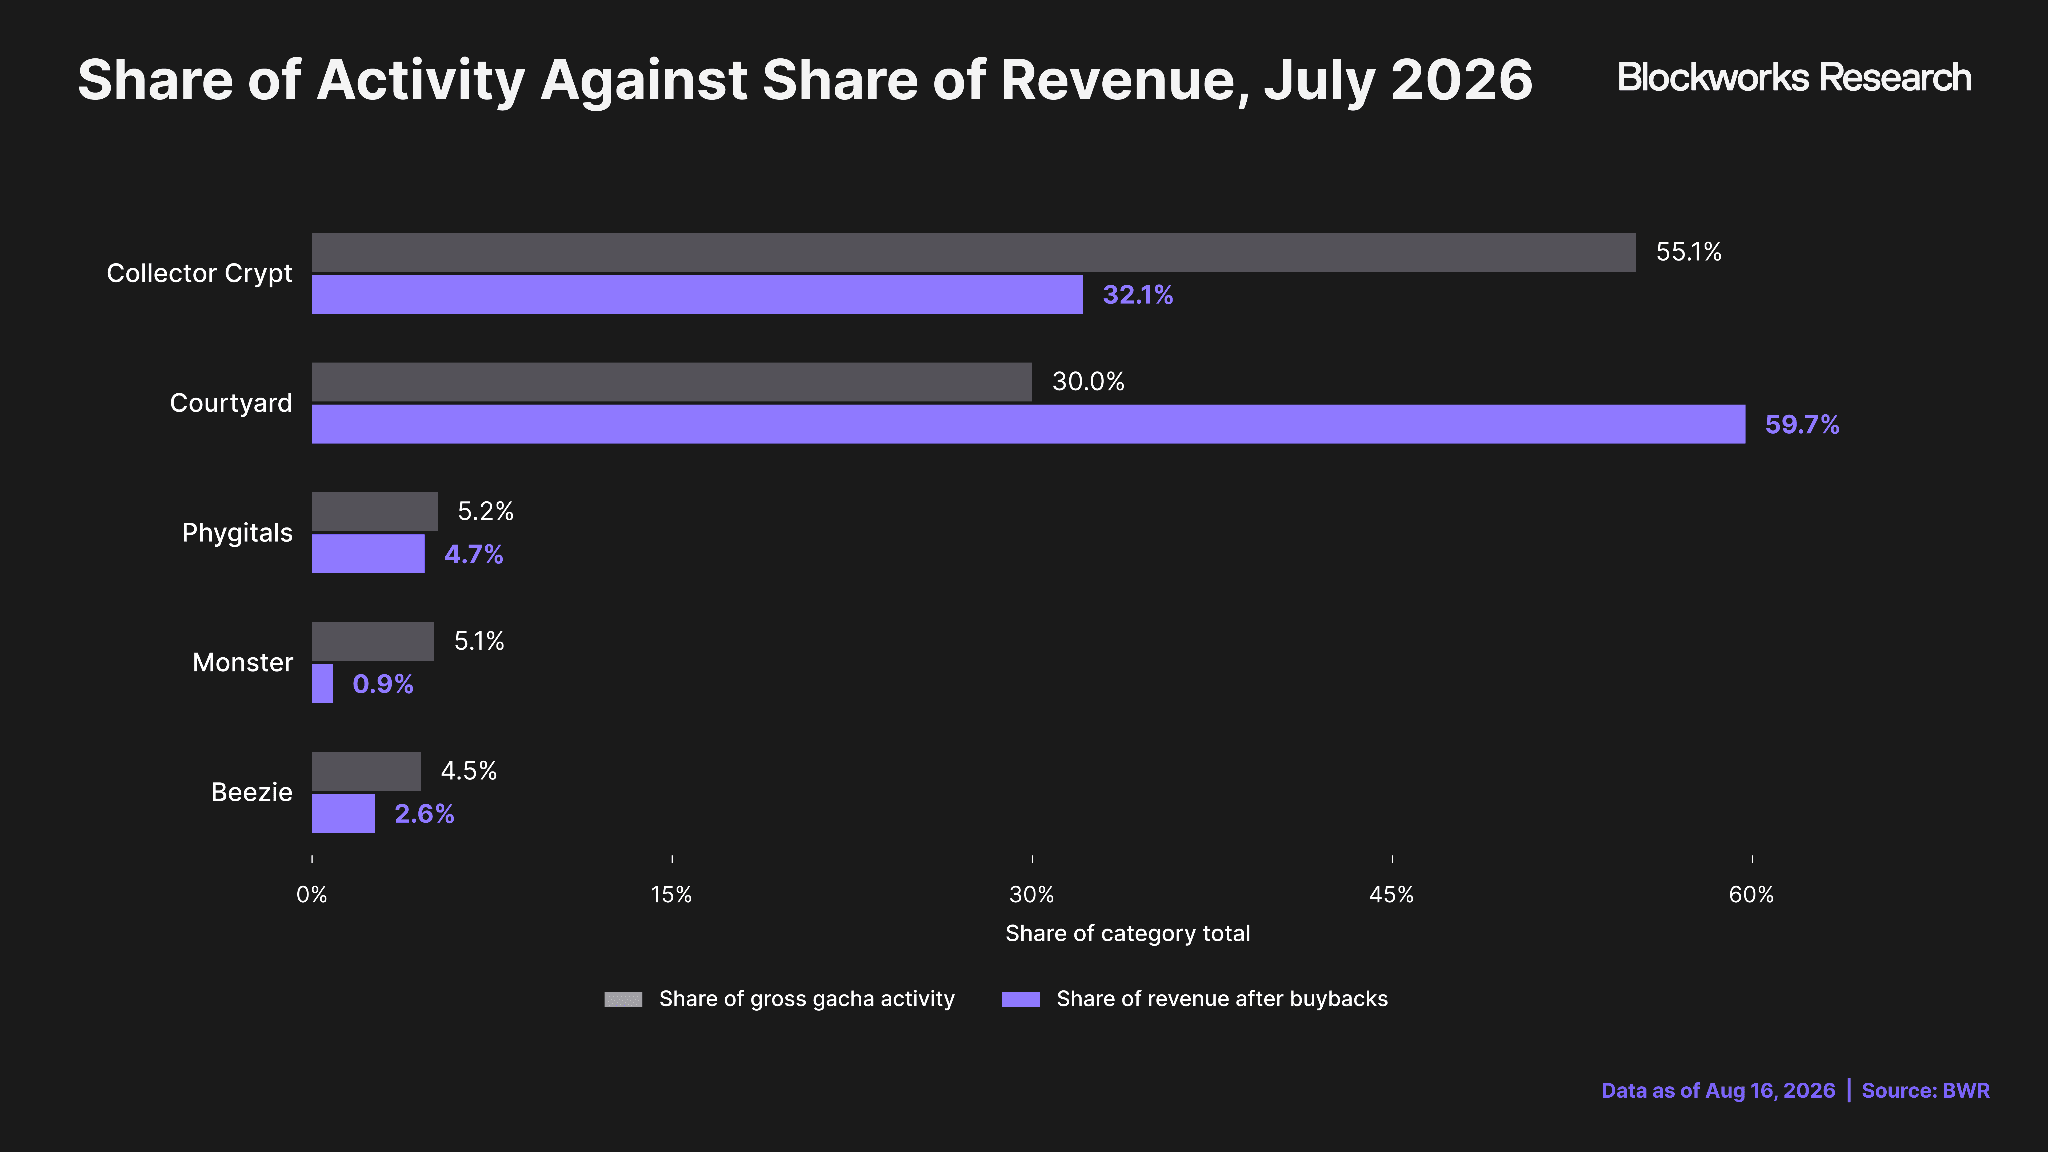
Part of Courtyard’s margin advantage comes directly from its buyback structure. The platform offers an instant buyback at 90% of fair market value and charges a 6% fee on the payout, leaving an effective quote of 84.6%, the lowest in the category. Courtyard’s realized buyback ratio was 75.6% in July, 17.3 percentage points below Collector Crypt’s 92.9%. The lower quote explains part of that gap, while differences in pack construction, consumer buyback behavior, and the alternative exit route likely explain some of the remainder.
Collector Crypt stands out most clearly in onchain transparency and distribution reach. It writes each collectible’s insured value into the token metadata and does not burn the token when it repurchases, so its inventory is reconstructable from onchain data. It maintained 100% gacha machine uptime through July, and redeemed 6,126 collectibles carrying $2.94 million of insured value. It supplies packs into 14 partner surfaces, the largest being Jupiter, Solflare, and Slabz.
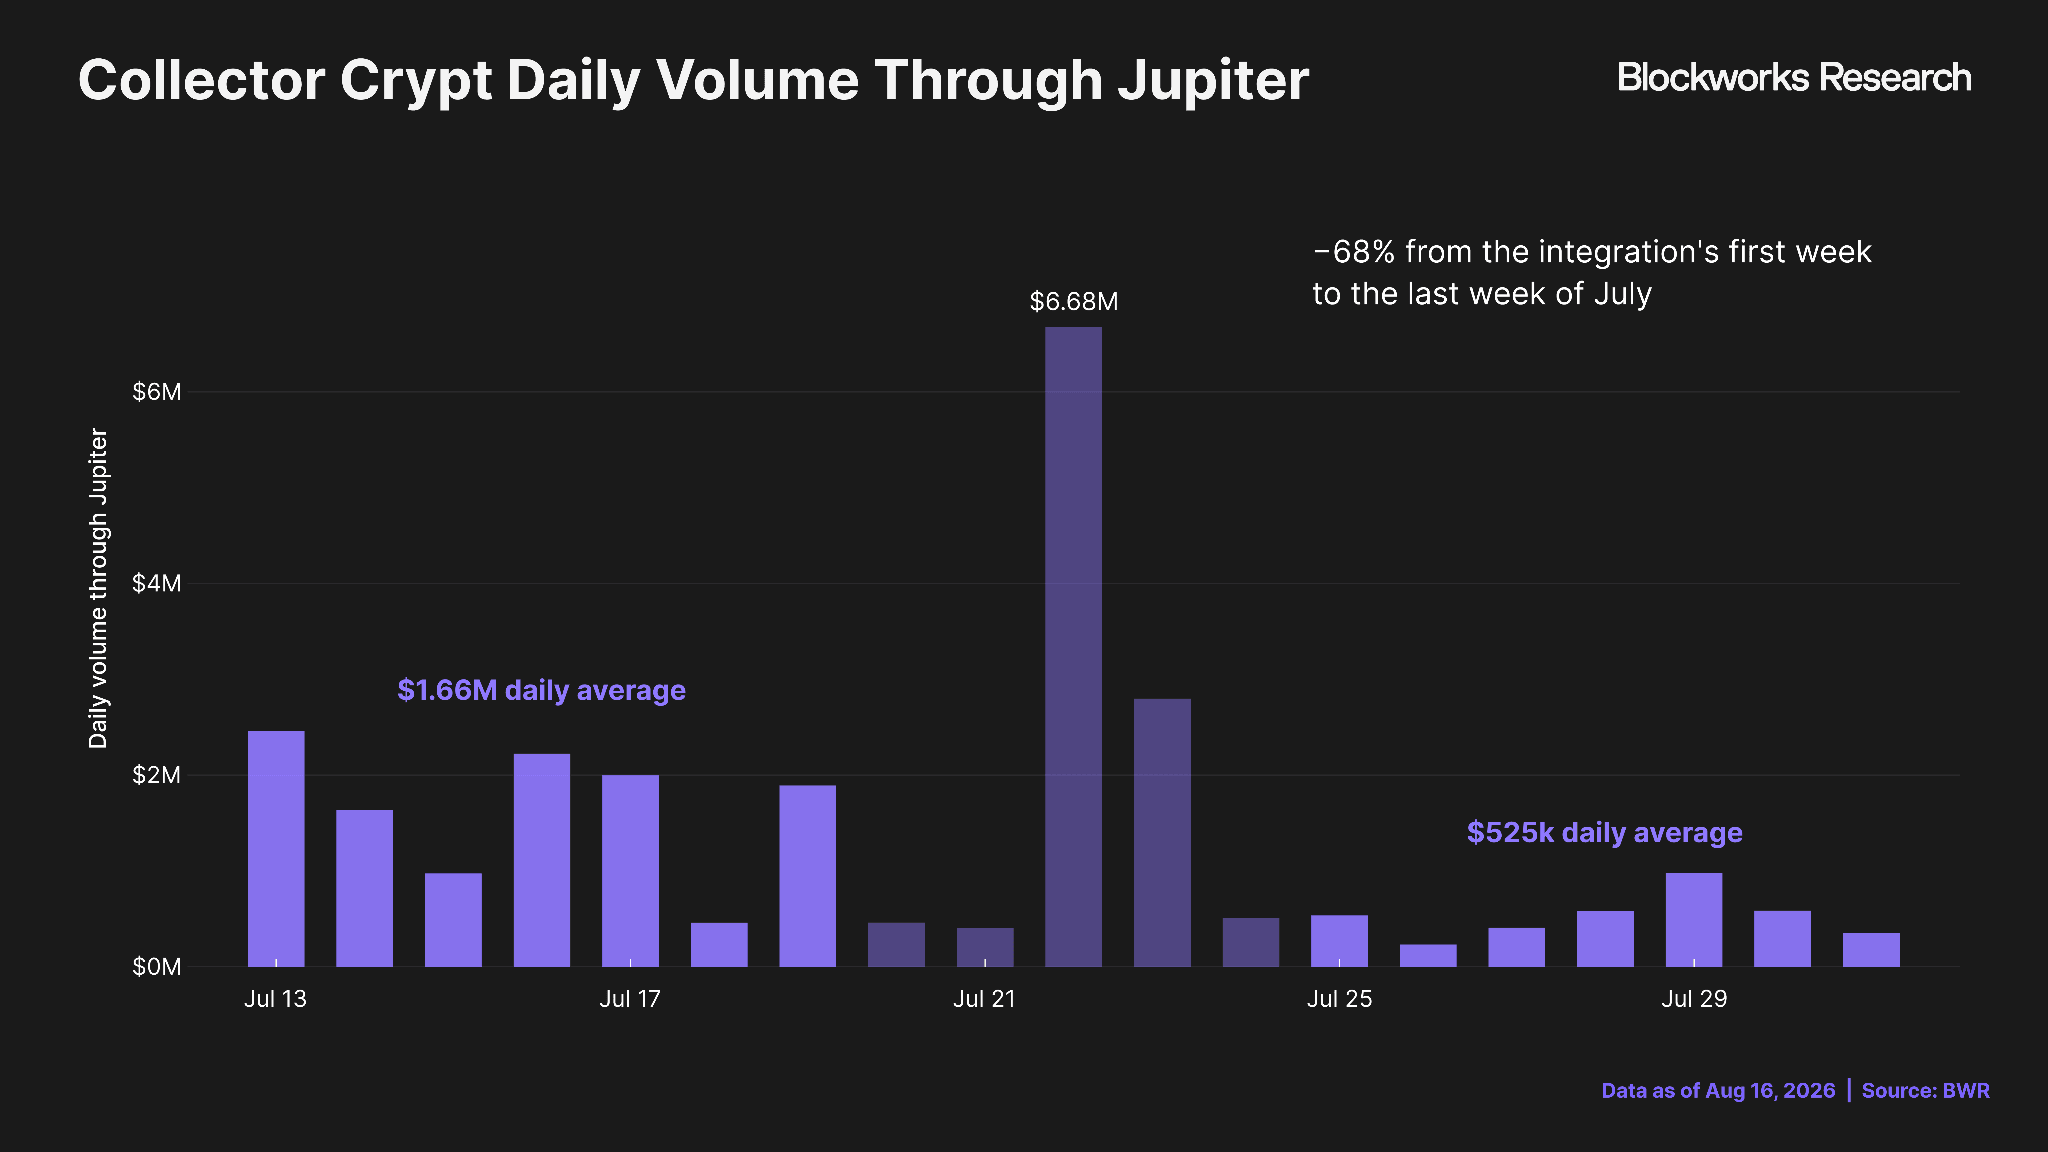
Collector Crypt's July growth profile is weaker once partner-sourced activity is separated from activity generated through its own channels. Partner channels supplied 25.9% of gross activity, and excluding them, July declined 42.1% MoM rather than 25.9%. Both figures compare to a June that Collector Crypt inflated with a quarterly airdrop and a $500,000 giveaway campaign. Partner channels have grown quickly in absolute terms. Partner spend rose from $2.4 million in May to $40.6 million in July, and most of that came from a single Jupiter integration that produced $26.2 million before decaying inside three weeks, from $1.66 million a day in its first week to $525,000 a day in the last week of July. The user base it opened held up better than the volume. Daily gacha users on Jupiter who were not already Collector Crypt users averaged 583 a day in launch week and 217 a day in the final week of July, so the channel settled at roughly 37% of its launch level. Against Collector Crypt’s own 871 daily active users, that is a material addition, though incentive campaigns for top spenders were still running on Jupiter through July.
Courtyard leads on revenue, units, and users, while Collector Crypt leads on a volume figure that its own buyback partly recycles. Testing that distinction means following what happens to a dollar after it enters a gacha machine.
Revenue Quality and Inventory Economics
Gross gacha activity substantially overstates the economic value these platforms retain. Buyback data makes that gap directly observable.
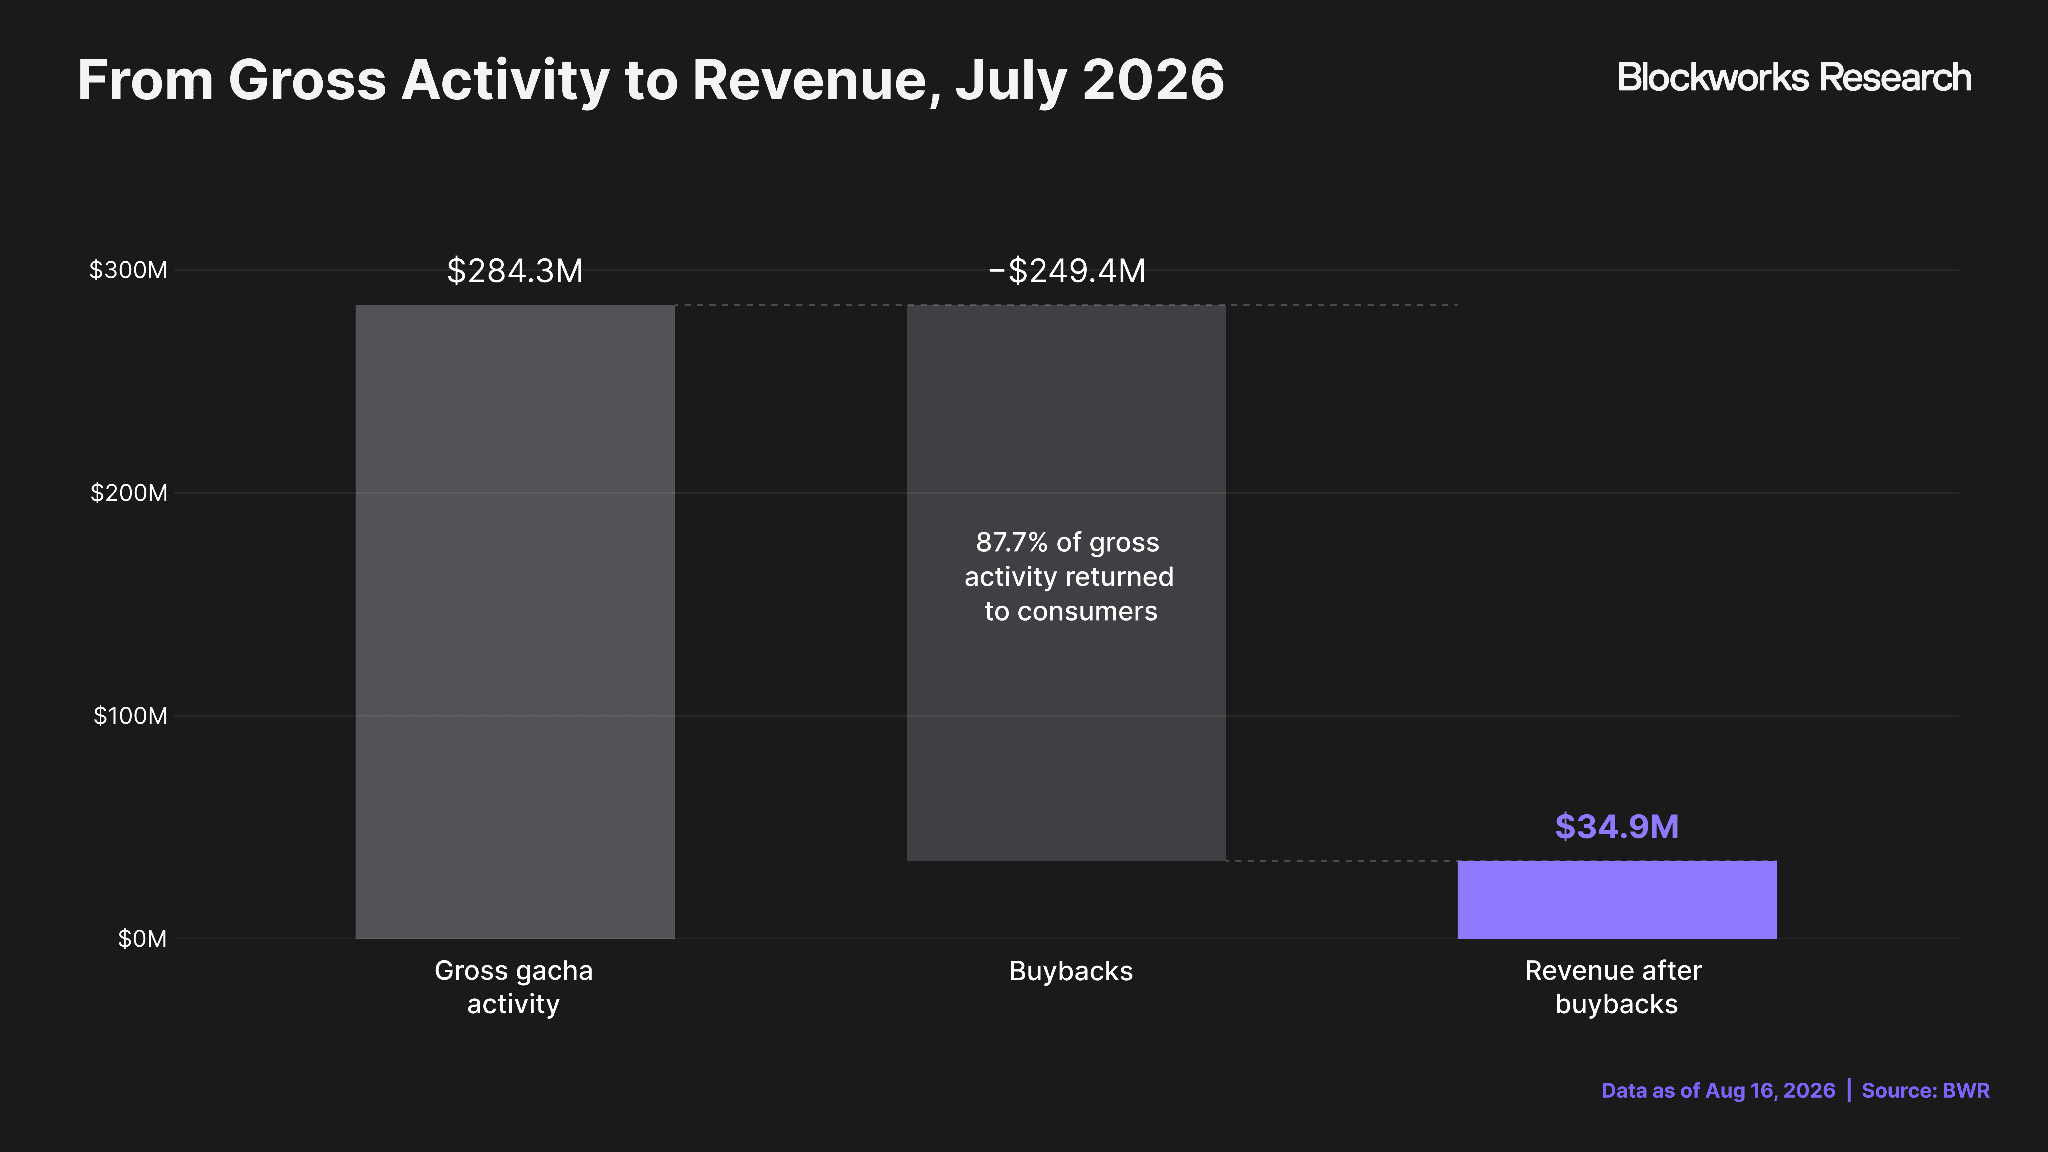
Buybacks remove 87.7% of gross activity across the five largest onchain gacha platforms. That disqualifies gross activity as an accurate measure of consumer demand. Because consumers can spend buyback credit on further purchases, the same external dollar can be counted several times in gross activity, and no dataset contains deposits, withdrawals, or credit respending. Balance velocity therefore cannot be calculated, and any figure presented for it would be manufactured. The buyback ratio is the available proxy. At 92.9% for Collector Crypt and Beezie and 97.9% at Monster, it implies substantial recycling but not actually how many times a dollar gets reused.
What survived the buyback is $34.9 million, close to what pump.fun earned in the same month. pump.fun recorded $32.7 million of revenue in July 2026 produced under a different cost structure. Pump holds no inventory, funds no consumer exits, insures nothing, and ships nothing. Every dollar of gacha revenue after buybacks must still absorb the cost of the card itself, grading, custody and insurance, fulfillment, and payment processing, and the platforms book that revenue before knowing what the returned inventory will resell for.
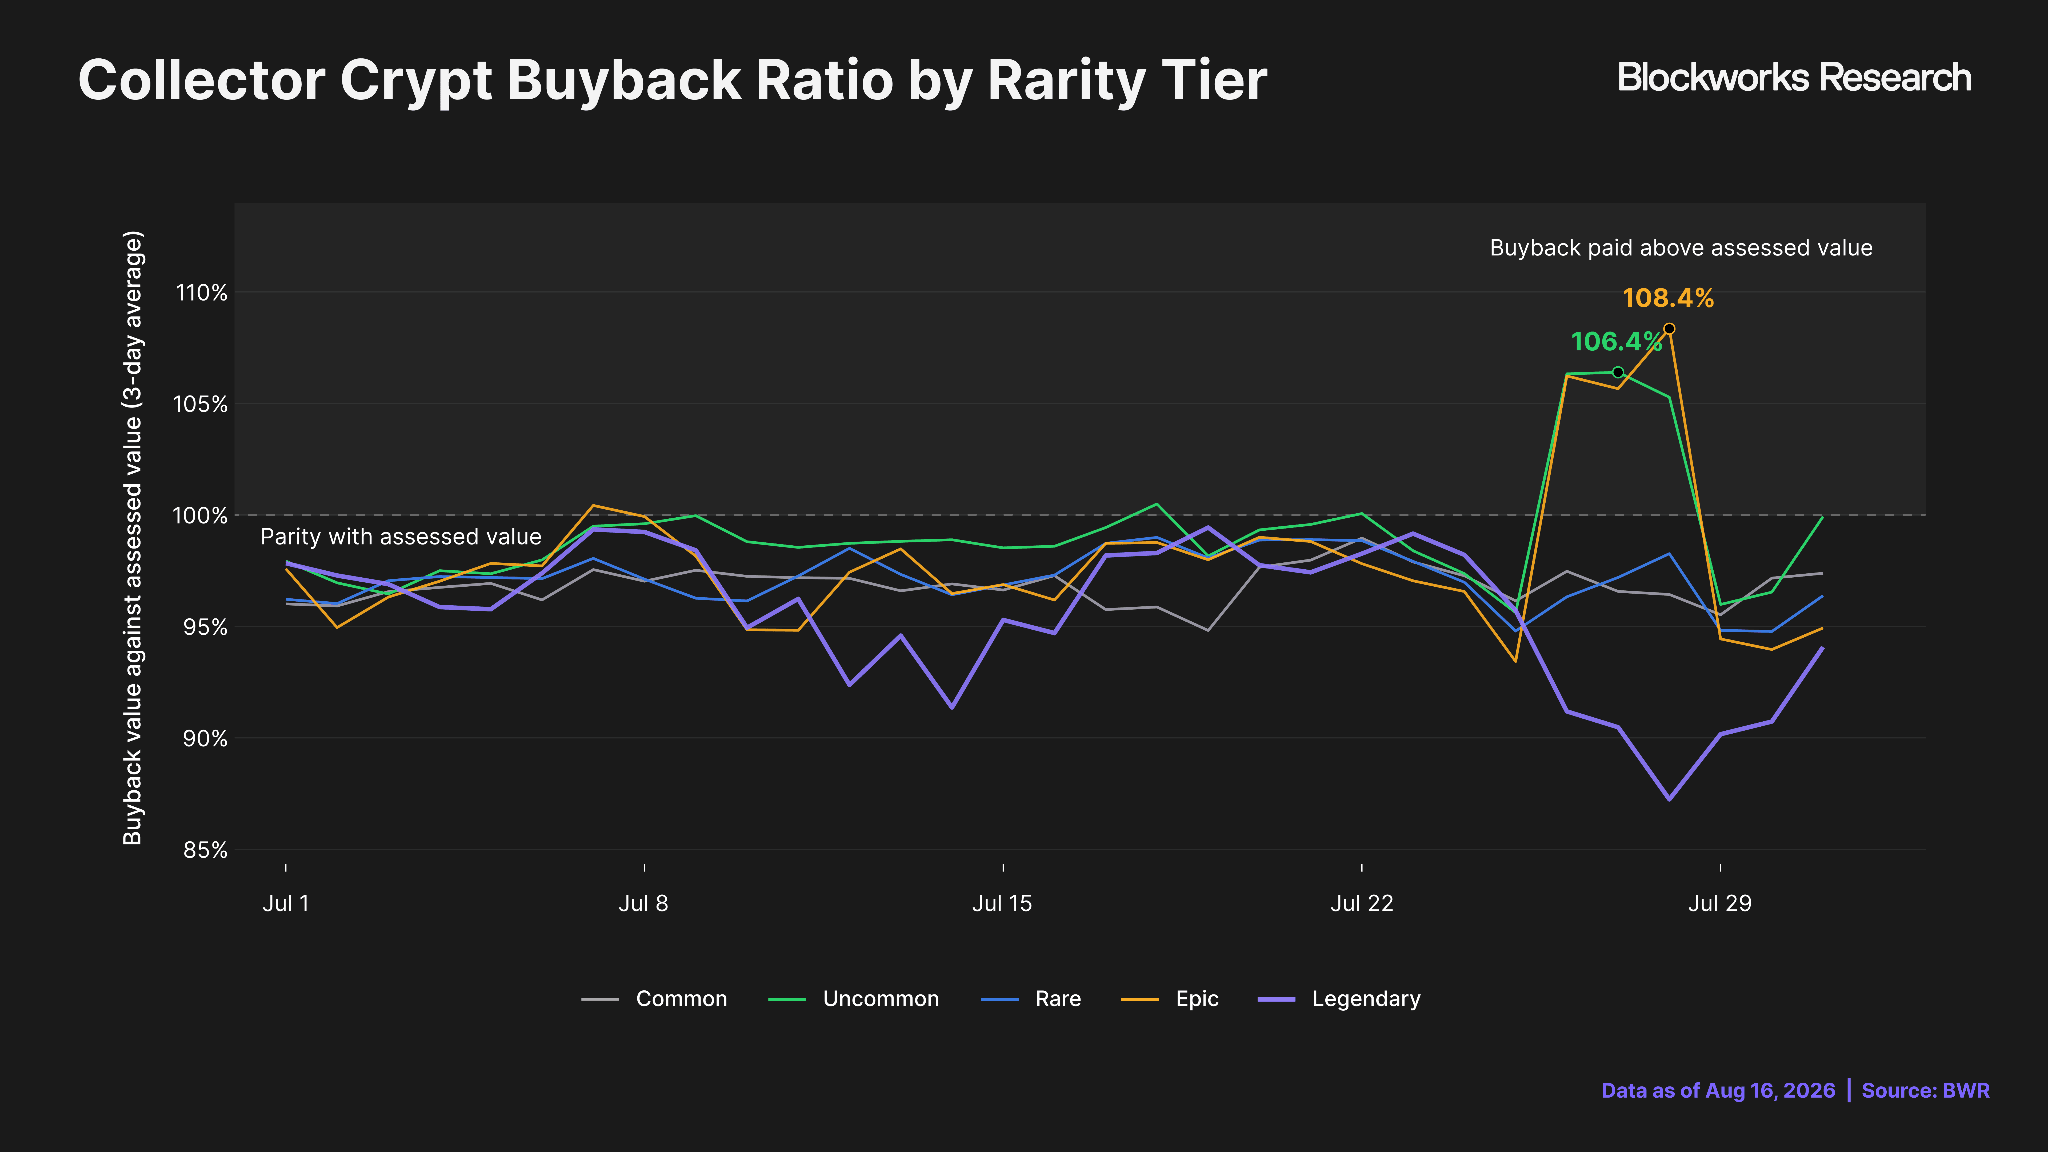
Whether revenue after buybacks becomes profit depends heavily on inventory economics. Consumers decide whether to accept a buyback after seeing the outcome, creating selection risk for the platform. At Collector Crypt, July buyback ratios averaged between 95.6% and 99.1% across rarity tiers, compared with legendary buybacks in the high eighties through much of 2025. Individual days ran wider, with uncommon and epic paying above assessed value in late July. The platform is therefore repurchasing inventory across the quality spectrum rather than primarily absorbing lower-tier outcomes.
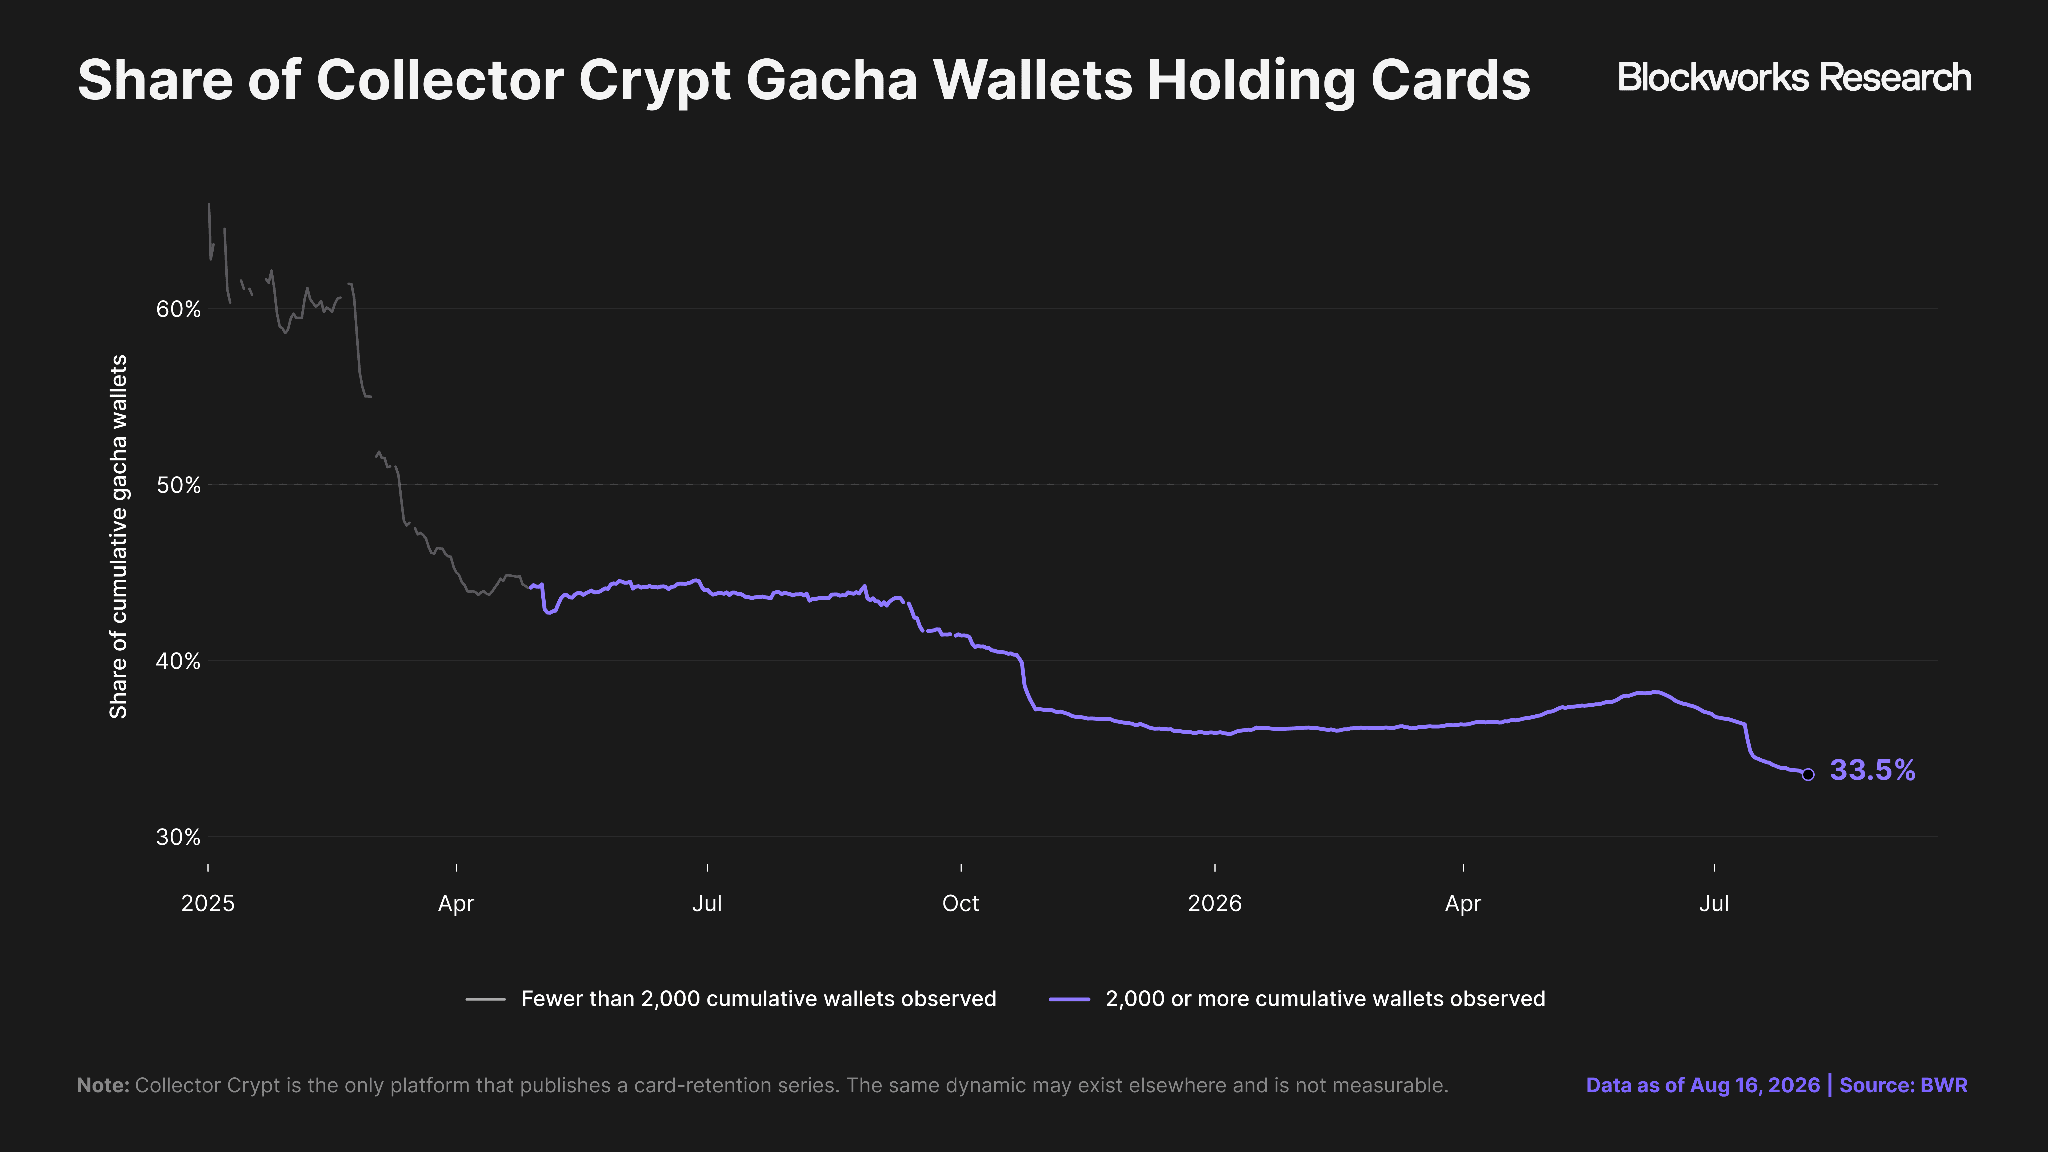
Collector Crypt is the only platform that publishes whether its users still hold the cards they pulled. Of every wallet that has ever opened one of its packs, 33.5% still hold at least one card, down from 59.4% in January 2025. The buyback is the main reason. It absorbs 92.9% of what the platform sells, while its secondary marketplace handles volume worth only 1.40% of its gacha activity.
The disclosures cannot answer whether that is expensive for Collector Crypt. Inventory acquisition costs, realized resale proceeds, holding periods, and working-capital requirements are not available for all five on a comparable basis. The available data establishes activity, buyback intensity, and inventory direction, but not whether revenue after buybacks converts into profit. That uncertainty raises the value of the capabilities that can improve unit economics, reduce balance-sheet dependence, and build durable advantage as the category matures.
How an Onchain Gacha Platform Builds a Moat
The core gacha product is easy to replicate. The randomized interface, tokenization layer, and buyback mechanism are already shared across competing platforms, and GameStop reproduced the entire product in April 2026 without using a blockchain at all. Collector Crypt distributes packs through 14 partner surfaces, and Phygitals holds Collector Crypt-originated slabs and repackages them into its own products. Neither the interface nor access to tokenized inventory creates a durable advantage on its own.
The more defensible capabilities improve economics as the platform scales. Three stand out: (1) independent liquidity, (2) owned distribution, and (3) inventory sourcing, underwriting, and curation.
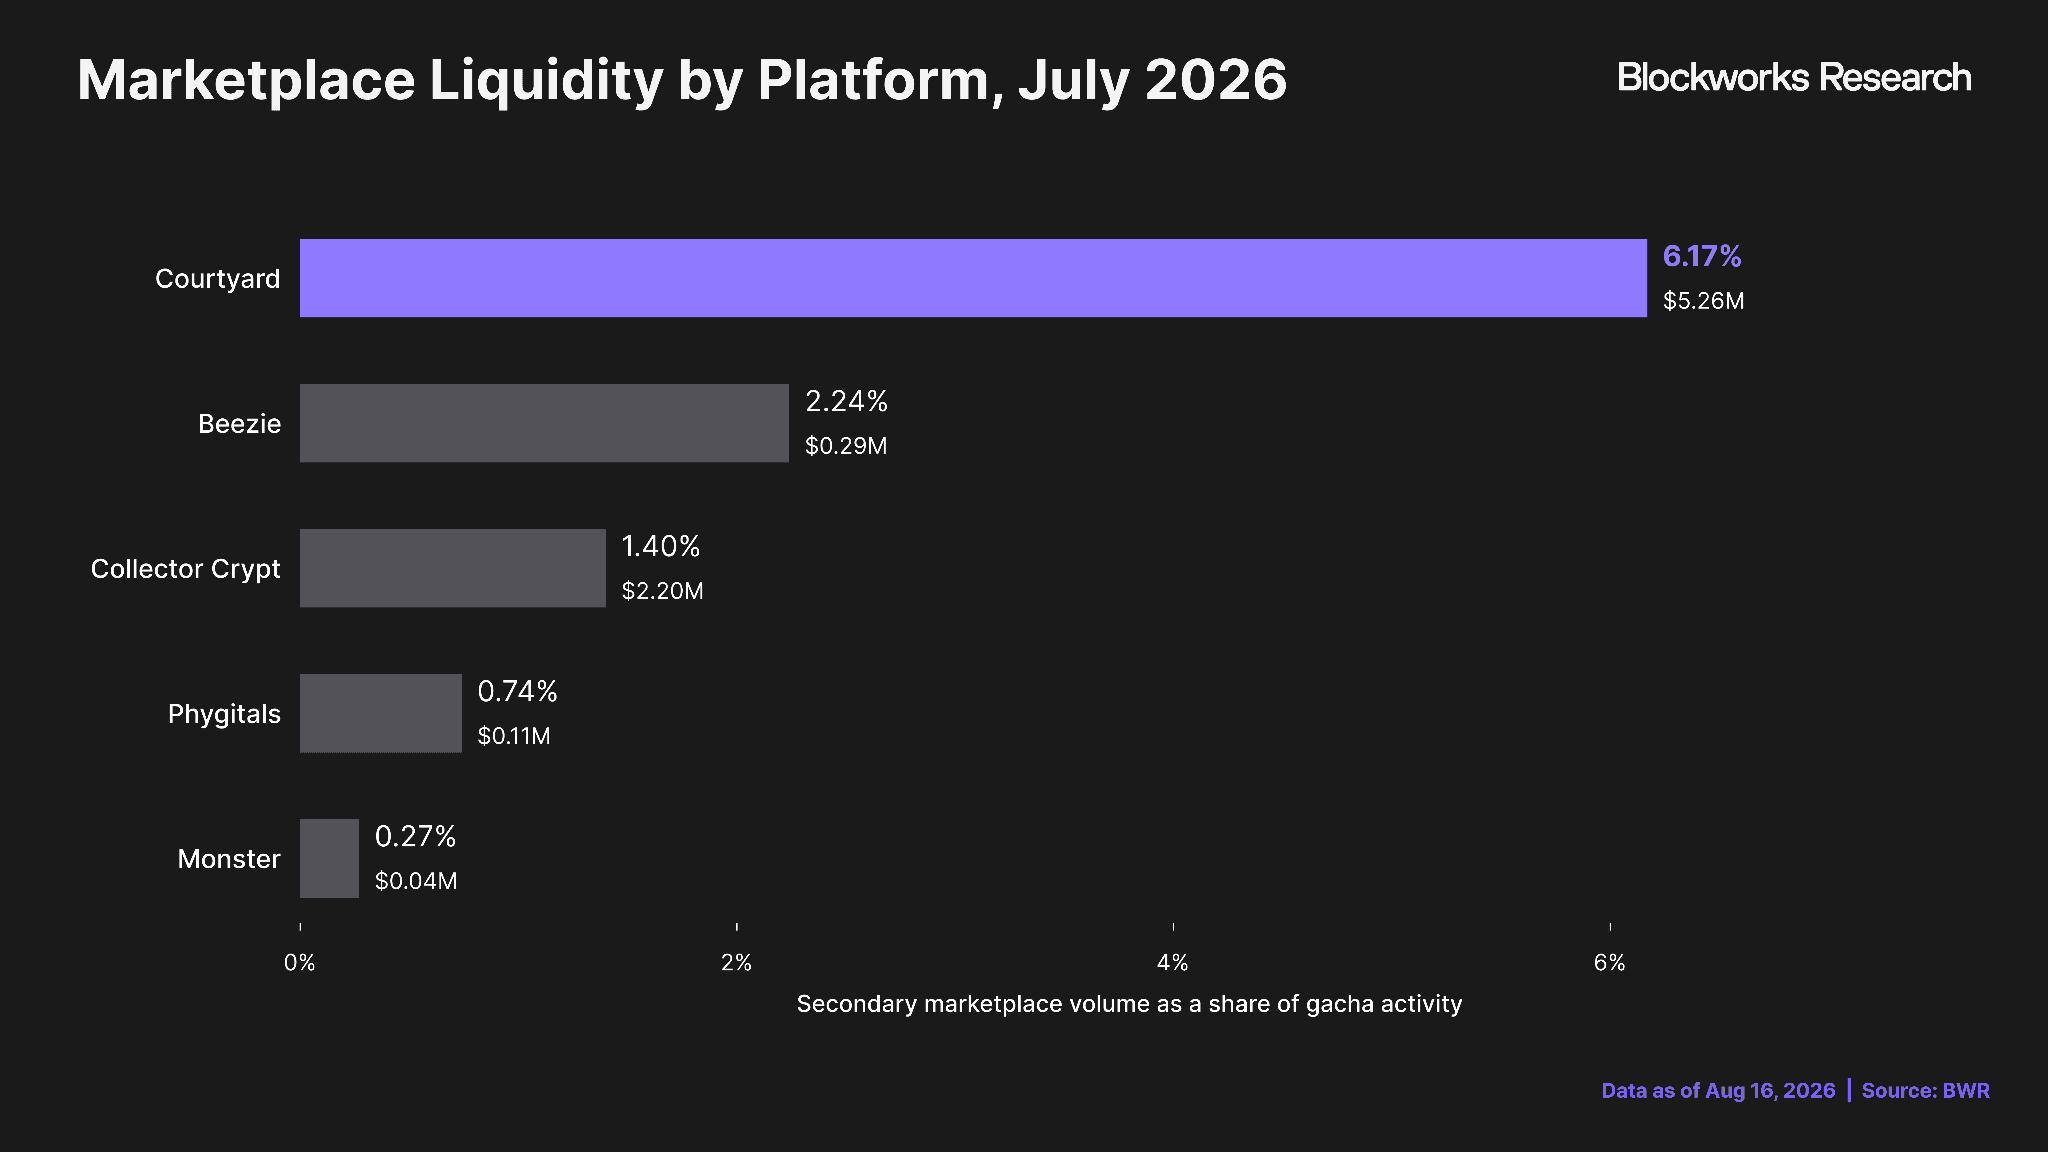
Independent liquidity is the clearest observable advantage. Courtyard is the only platform where secondary trading represents a meaningful share of the core business. It cleared $5.3 million of marketplace volume in July, twice the $2.6 million of the other four combined and equal to 6.2% of its own gacha activity. Beezie and Collector Crypt still rely heavily on platform-funded repurchases, while Phygitals’ marketplace activity has fallen to immaterial levels and Monster’s has never reached them. That difference matters because independent buyers reduce the amount of exit liquidity the platform must finance, reduce inventory returning to the balance sheet, and generate real market prices that can improve future buyback underwriting.
Courtyard’s lead in secondary trading is partly a pricing decision. It charges nothing on marketplace sales, matched only by Monster, against 1.96% at Phygitals, 2% at Collector Crypt, and 6% at Beezie. Every dollar that shifts from the buyback to the marketplace is one Courtyard no longer has to fund and no longer earns a fee on. On July's marketplace volume, a 2% fee matching Collector Crypt's would have produced roughly $105,000. Had that same value gone through the buyback instead, Courtyard would have paid out roughly $4.5 million at its effective 84.6% quote. The zero fee is a subsidy that steers consumers toward the exit Courtyard’s balance sheet does not have to fund.
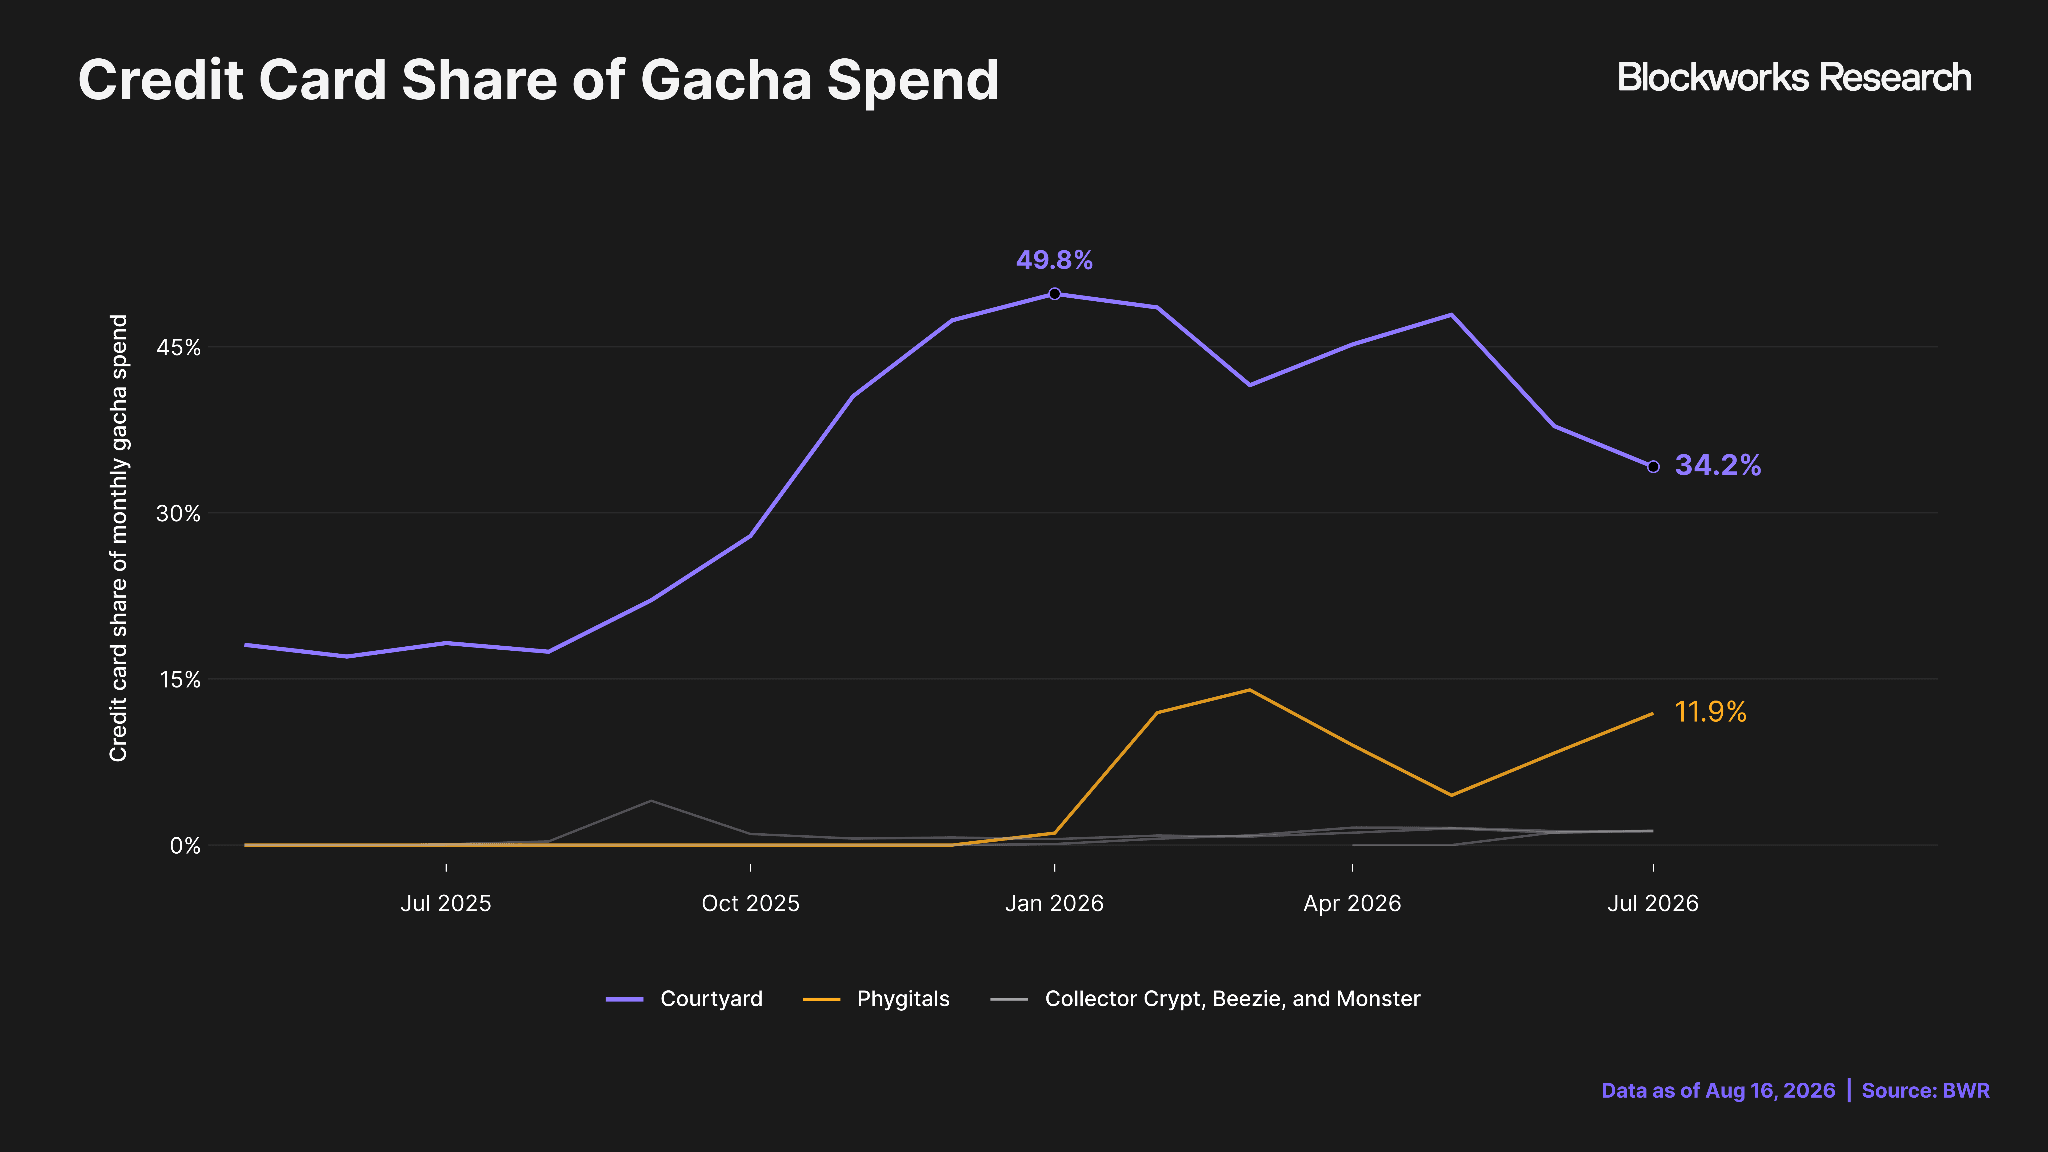
Owned distribution is the second clear advantage. Courtyard’s growth came through its own funnel, and that funnel is a consumer app rather than a web page. Its iPhone app holds a 4.6 rating across 7,500 ratings, while Collector Crypt, Beezie, and Monster operate through web interfaces and Phygitals shipped its mobile app on July 31st. Credit cards accounted for 34.2% of Courtyard’s July gacha spend, against 11.9% at Phygitals and roughly 1% at Collector Crypt, Beezie, and Monster. A buyer who arrives with a card and an email address never needs a wallet, which reaches a far larger pool than crypto-native distribution. Courtyard averaged 2,382 new consumers a day in July, compared with Collector Crypt’s 235.
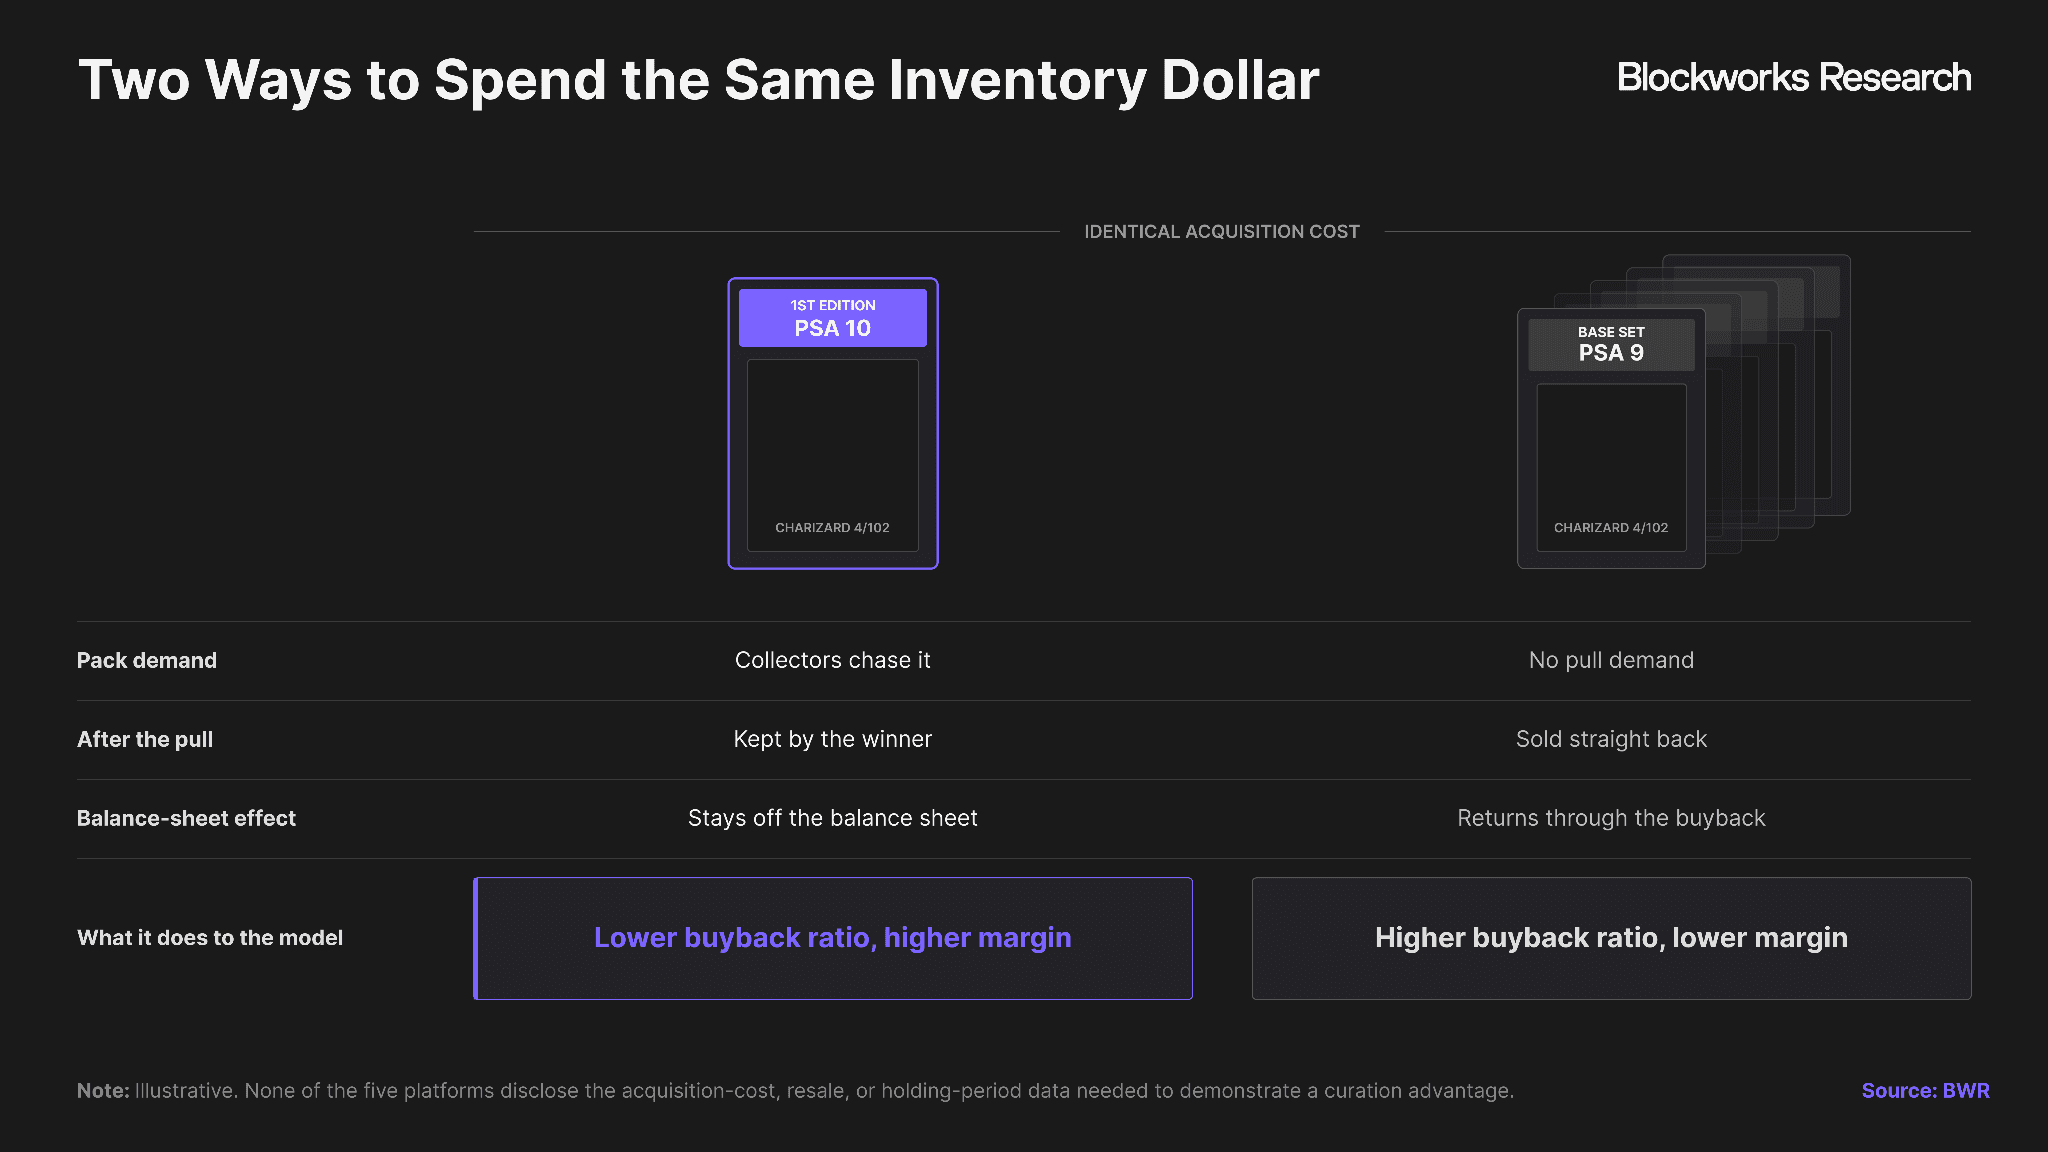
The deepest potential moat is inventory sourcing, underwriting, and curation. Buying below realistic recovery value and quoting buybacks accurately lets a platform absorb fewer markdowns and tie up less capital. Curation is the hardest of the three. A single PSA 10 first-edition Charizard and a stack of PSA 9 base-set copies can cost the same, and the Charizard is the better inventory. Collectors chase it, so it sells packs, and whoever pulls it keeps it. The base-set copies sell no packs and come straight back through the buyback. A platform curating well would therefore show a lower buyback ratio and a higher margin, which is what separates the platforms. None of the five discloses enough acquisition-cost, resale, or holding-period data to prove an advantage here yet.
Redemption reliability and verifiable draw mechanics also matter, but they are better viewed as trust infrastructure than as durable moats. Collector Crypt has the strongest evidence of verifiable draw mechanics, while redemption data show that multiple platforms can successfully convert tokenized claims into physical assets. These capabilities can lower consumer friction and strengthen credibility, but they are ultimately replicable.
July 2026 provides the first meaningful test as activity contracts, but the available data is not yet sufficient to identify a sourcing or underwriting leader. Until that evidence emerges, Courtyard leads on the most visible sources of defensibility, particularly independent liquidity and owned distribution.
Risks
Every conclusion above assumes purchases keep coming. Falling activity reduces new external funding, and weaker sentiment raises buyback acceptance and withdrawals. Both return more inventory to the platform as recovery values fall and holding periods lengthen.
July shows falling activity without a drop in collector demand. Onchain gacha activity fell 17.5%, but secondary trading card volume outside onchain platforms held at $694.7 million against $695.6 million in June, so collector demand did not weaken. Collector Crypt saw average daily spend fall 39% between the first and last weeks of July, while Courtyard reached an all-time high. Part of that decline reflects the wind-down of Collector Crypt’s June airdrop and giveaway campaign, and part reflects crypto-native capital rotating out of gacha while collector demand held.
Our current onchain gacha ranking would change under several identifiable conditions:
Courtyard’s advantage is a 75.6% buyback ratio in a category averaging 87.7%, which is also the highest cost to a consumer who sells back. Competitive pressure or weakening demand that pushes it above 85% would compress its net gacha margin toward the group average and narrow the ranking..
Collector Crypt’s recurring consumer base grew 10.5% in July, its new users 51%, and its daily active users 19%. If partner surfaces begin functioning as an acquisition funnel rather than a volume rental, Collector Crypt’s scale advantage becomes durable, and it takes the top position.
Any platform can raise buyback quotes to purchase share, but every additional point returned comes straight out of margin. Collector Crypt and Beezie return 92.9%, and Monster returned 97.9% in July for a 2.1% net gacha margin. Share acquired through uneconomic liquidity support is difficult to retain once the support is withdrawn, and it accelerates the rate at which inventory returns.
Pokémon supplied 80.8% of Collector Crypt's July pack spend. A Pokémon drawdown would reduce the value of held inventory and buyback quotes the platform can credibly support in the same month.
Custody or redemption failure would affect confidence across a platform rather than a single transaction, because the digital claim is only valuable while it remains tied to a specific, secure, and redeemable collectible. Several platforms also depend on the same graders, vault operators, and payment processors, creating the potential for a single provider disruption to affect multiple applications.
Incumbents do not need to adopt tokenization to compete for the same collector demand. eBay operates the largest card marketplace, owns TCGplayer and Goldin, has completed 80 million cumulative AI card scans as of Q2 2026, and provides free authentication above $200. GameStop has built the gacha product itself. Power Packs is the onchain gacha model without a chain, distributed through a retailer that already owns the storefront, the grading relationship, and the fulfillment.
Conclusion
Courtyard is the strongest-performing onchain gacha platform as of July 2026. It generated the most revenue after buybacks, grew while the category contracted without raising its buyback ratio, operates the only secondary marketplace with meaningful retail activity, and has built the strongest direct consumer distribution of the top five. The main limitation is data visibility below revenue after buybacks. The available onchain data do not capture the costs needed to determine whether Courtyard's 24.4% net gacha margin translates into underlying profitability.
Collector Crypt remains the leader in gross activity and stands out for its onchain inventory transparency and the breadth of channels it supplies, but its July performance was increasingly dependent on partner channels. Partner surfaces contributed 25.9% of gross activity; activity excluding those channels fell 42.1% MoM against a June inflated by its own airdrop and giveaway campaign while still running above May and April, and Jupiter volume declined sharply within weeks of launch. Phygitals and Beezie remain much smaller, are contracting, and rely heavily on platform-funded liquidity, weakening the connection between reported activity and underlying economics. Monster grew past Beezie in July, but only on a 97.9% buyback that left it at 0.9% of the five platforms’ combined revenue after buybacks.
Across the five platforms, 87.7% of gross activity returned to consumers through buybacks. What happens below that line cannot be assessed, because acquisition cost, resale proceeds, and holding periods are not available across all five. Onchain gacha has shown that tokenized physical collectibles can generate substantial consumer activity and application revenue. It has yet to demonstrate that the inventory and buyback cycle can consistently produce profit. July was the category's first monthly decline since February, from a June record that incentives at the largest platform helped set, and the next several months should provide a clearer test of which models can sustain attractive economics.
The information contained in this report and by Blockworks Inc. and related affiliates is for general informational purposes only and is not intended to provide legal, financial, or investment advice. The report should not be construed as an offer or solicitation to buy or sell any security, token, or financial instrument and does not represent any recommendation or endorsement of any investment or financial product or service. Blockworks Inc. and related affiliates are not registered as a securities broker-dealer or an investment advisor in any jurisdiction or country.