This research report has been funded by MEXC Ventures. By providing this disclosure, we aim to ensure that the research reported in this document is conducted with objectivity and transparency. Blockworks Research makes the following disclosures: 1) Research Funding: The research reported in this document has been funded by MEXC Ventures. The sponsor may have input on the content of the report, but Blockworks Research maintains editorial control over the final report to retain data accuracy and objectivity. All published reports by Blockworks Research are reviewed by internal independent parties to prevent bias. 2) Researchers submit financial conflict of interest (FCOI) disclosures on a monthly basis that are reviewed by appropriate internal parties. Readers are advised to conduct their own independent research and seek advice of qualified financial advisor before making investment decisions.


The Cross Asset Shift
Key Takeaways
- MEXC’s survey shows strong Asian demand. Around 62.6% of crypto native respondents primarily trade precious metals through CEXs, while 87.2% plan to increase their TradFi trading.
- Futures lead the shift. TradFi categories now exceed 12% of CEX futures volume, while MEXC’s average daily stock futures volume across Asia rose 3,308% in Q2.
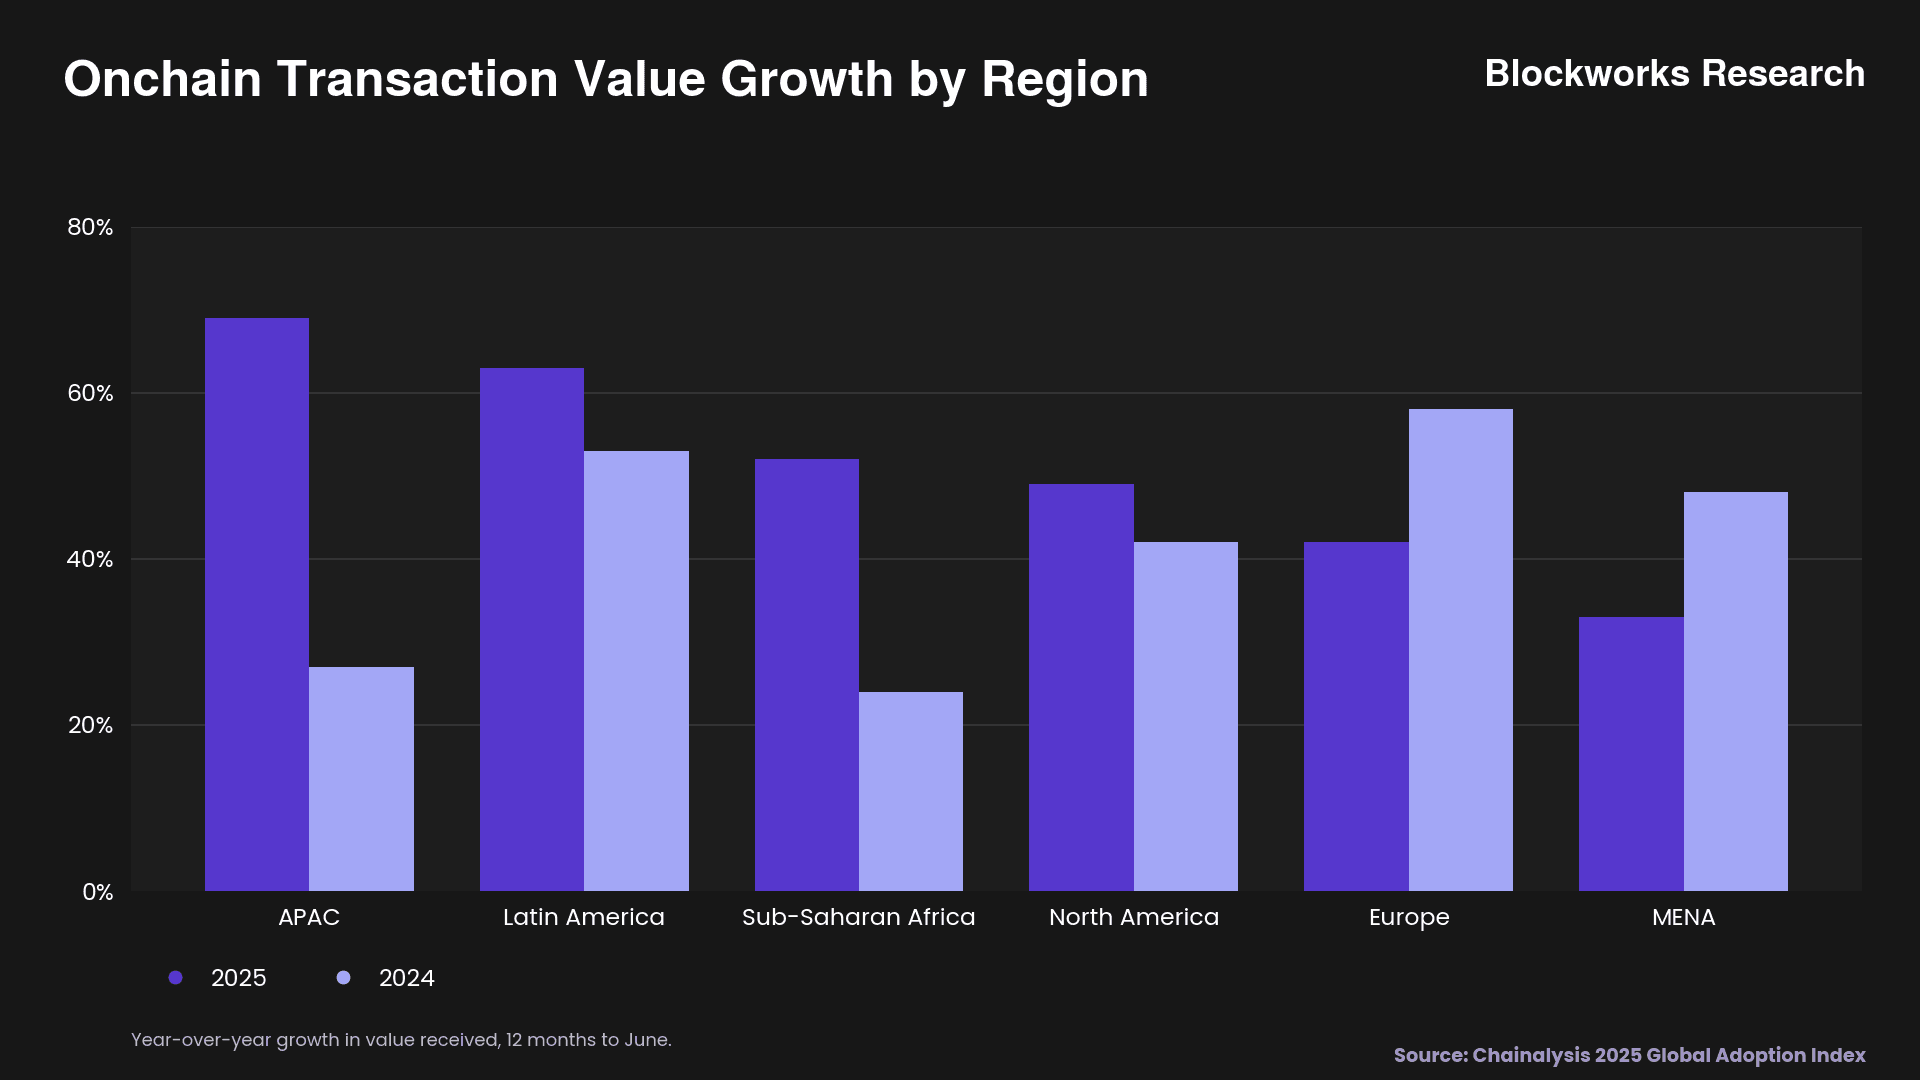
- Asia already has the crypto rails. APAC onchain value grew 69% year over year, while stablecoins let users trade crypto and traditional assets from the same account.
- CEXs reduce the steps between an event and a trade. In MEXC’s survey, 75.1% of Asian users had encountered a major event while traditional markets were closed.
- Gold is the clearest early case study. Precious metals open interest peaked at $1.98B in May and remained at $1.69B at the end of June, accounting for 36.2% of total TradFi perpetuals open interest.
- Future growth requires deeper spot markets, better education, stronger leverage safeguards and reliable weekend liquidity. MEXC Ventures has identified tokenization, trading infrastructure, custody and settlement as key investment areas for further scaling TradFi markets
Introduction
Some of the best trades of this cycle have been outside crypto. Since the start of 2025, BTC has fallen 32%, while Gold, QQQ and SPY have gained 64%, 42% and 32%, respectively. AI and memory stocks have also attracted much of the speculative attention that once flowed into crypto markets.
Crypto traders have adapted. Instead of waiting for another broad crypto rally, many are using CEXs to trade equities, commodities and indices. Exchanges have supported this shift by listing spot and perpetual markets linked to traditional assets, allowing users to trade them through the same accounts and stablecoin balances they already use for crypto.
Asia provides a clear view of this change. The region combines strong demand for assets such as gold and US equities with high crypto adoption and greater friction across traditional brokerage channels. In collaboration with MEXC Ventures, this report examines how visible the shift has become, why futures currently dominate trading activity and what CEXs need to build for these markets to develop beyond leveraged trading.
The Shift Is Already Visible in Asia
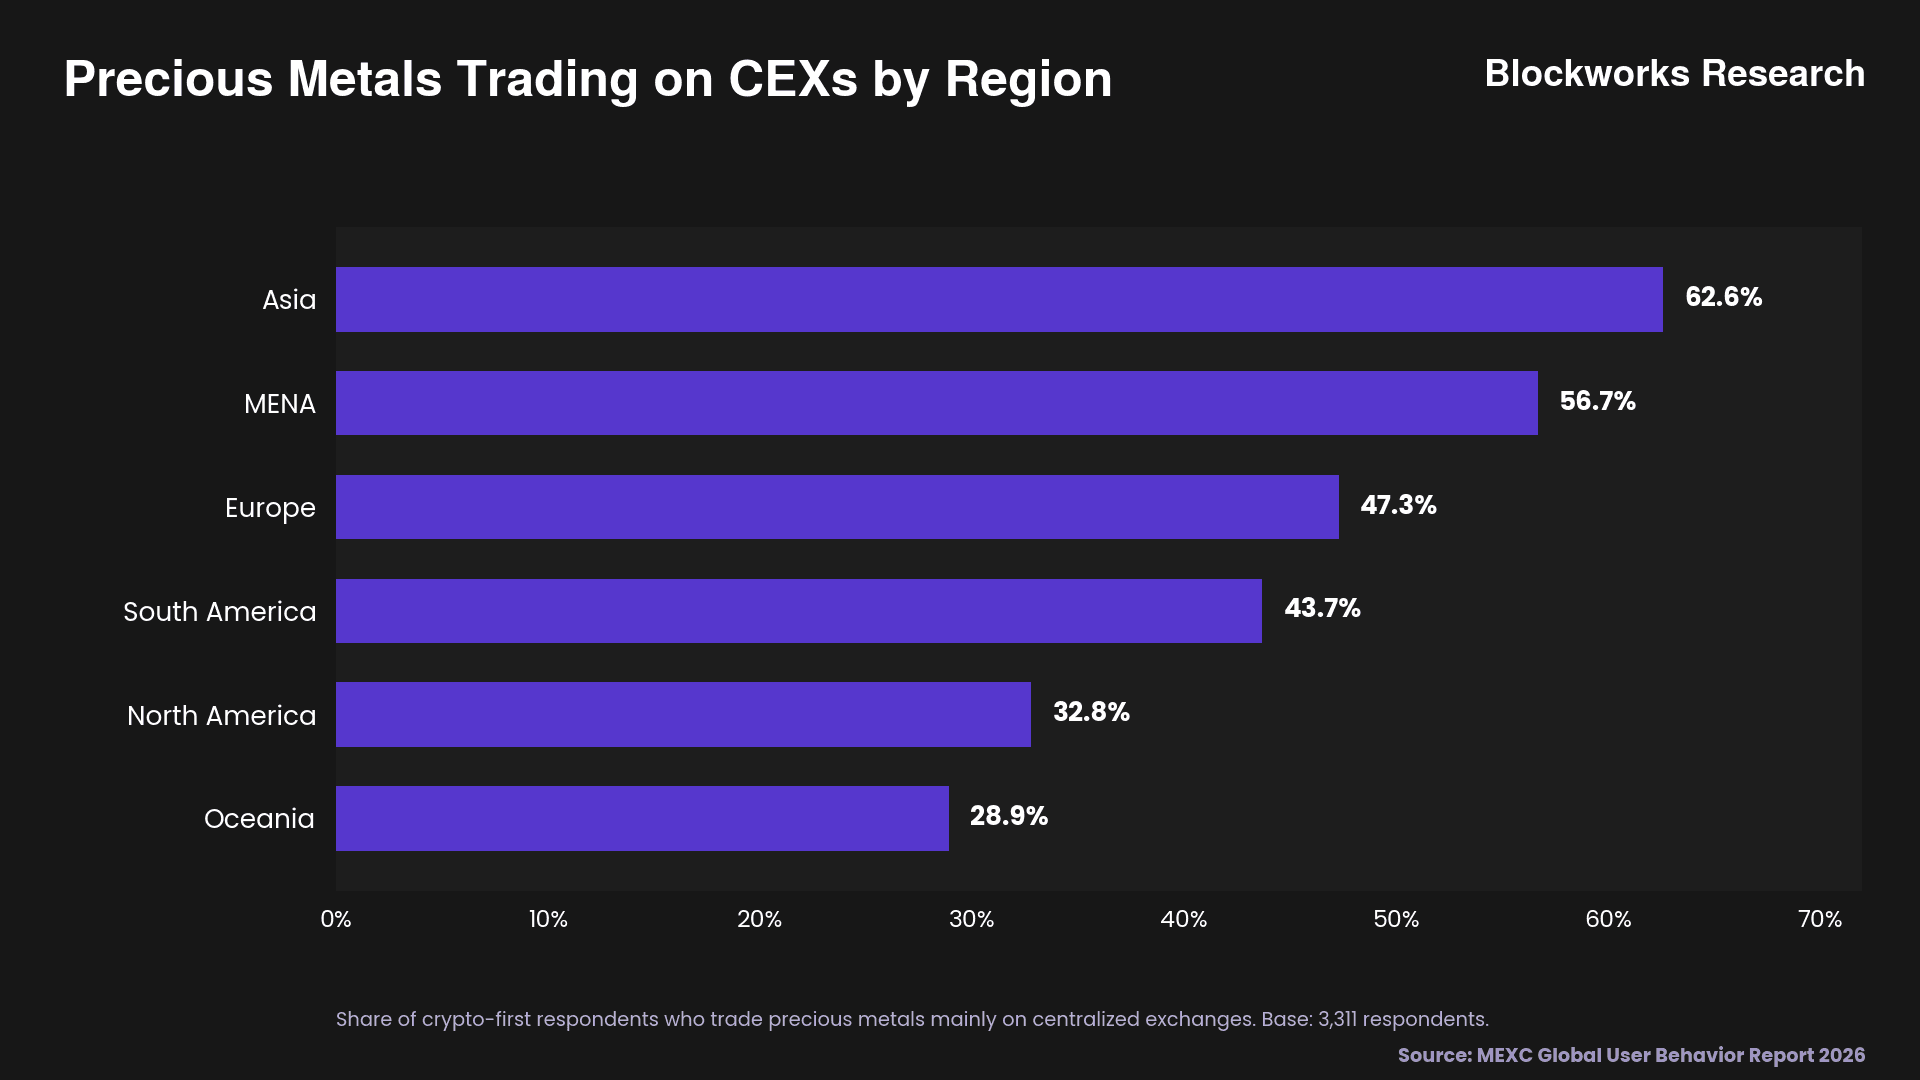
MEXC’s survey suggests this shift is already underway. Among Asian crypto native respondents, 62.6% primarily trade precious metals through CEXs. This was the highest share across all regions and well ahead of MENA and Europe.
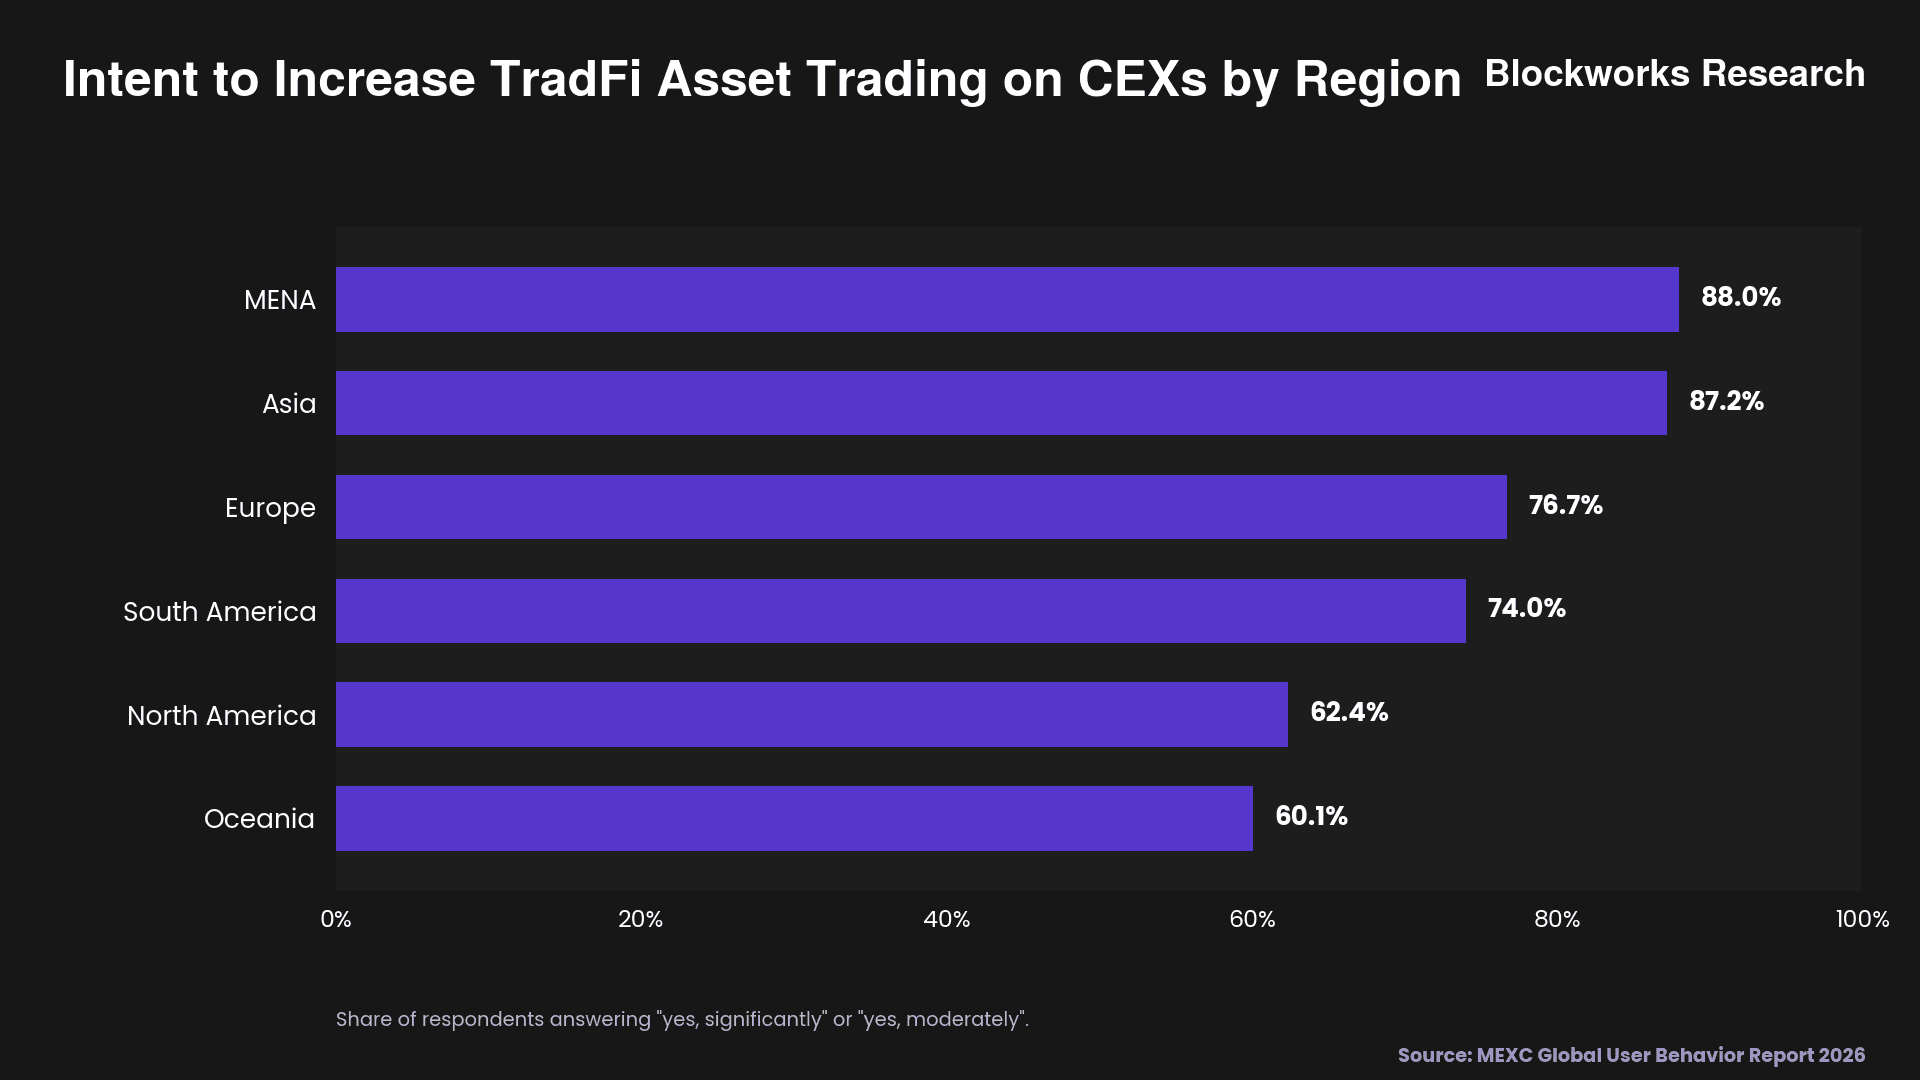
The demand also appears likely to grow. Around 87.2% of surveyed Asian users plan to increase their trading of TradFi assets on CEXs, only slightly below MENA at 88%. MEXC’s trading activity in Southeast Asia suggests some of that intent is already converting into trades. Average daily users trading stock spot products rose 153% in Q2 2026 from Q1, while average daily volume increased 348%. The momentum continued through August. Compared with Q2, Q3 average daily users increased another 159%, while average daily volume rose 87%.
The more revealing question is how these users are trading. Spot markets still account for a small share of activity, while futures have attracted significantly more volume. That difference provides the first clue as to what is driving the shift.
Futures Are Driving the Shift
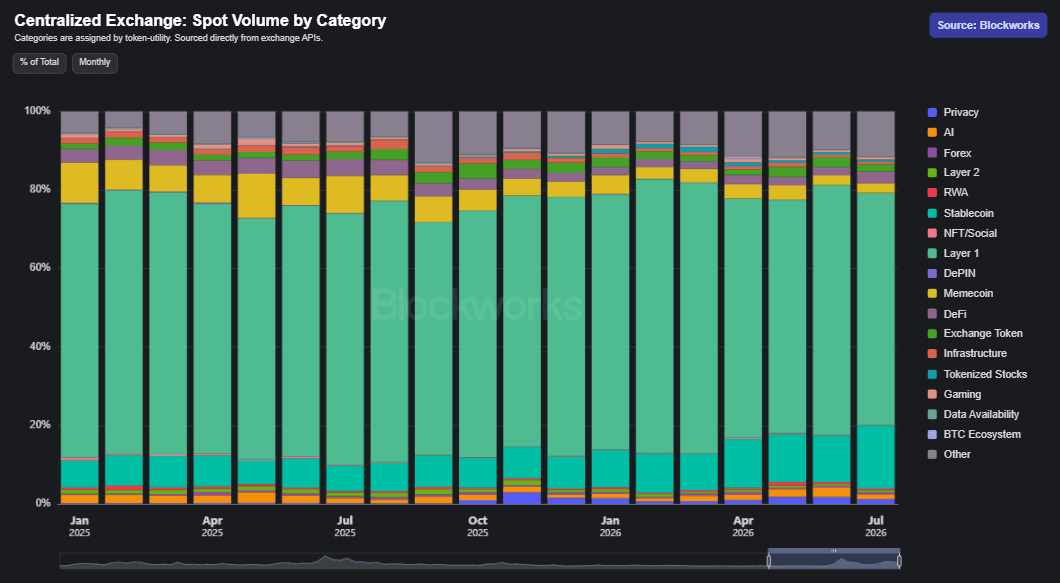
The difference between spot and futures provides the clearest indication of how CEX users are trading traditional assets. Across CEX spot markets, RWAs, forex and tokenized stocks account for less than 2% of monthly volume. Crypto assets continue to dominate, leaving these newer categories as a small part of the overall spot market.
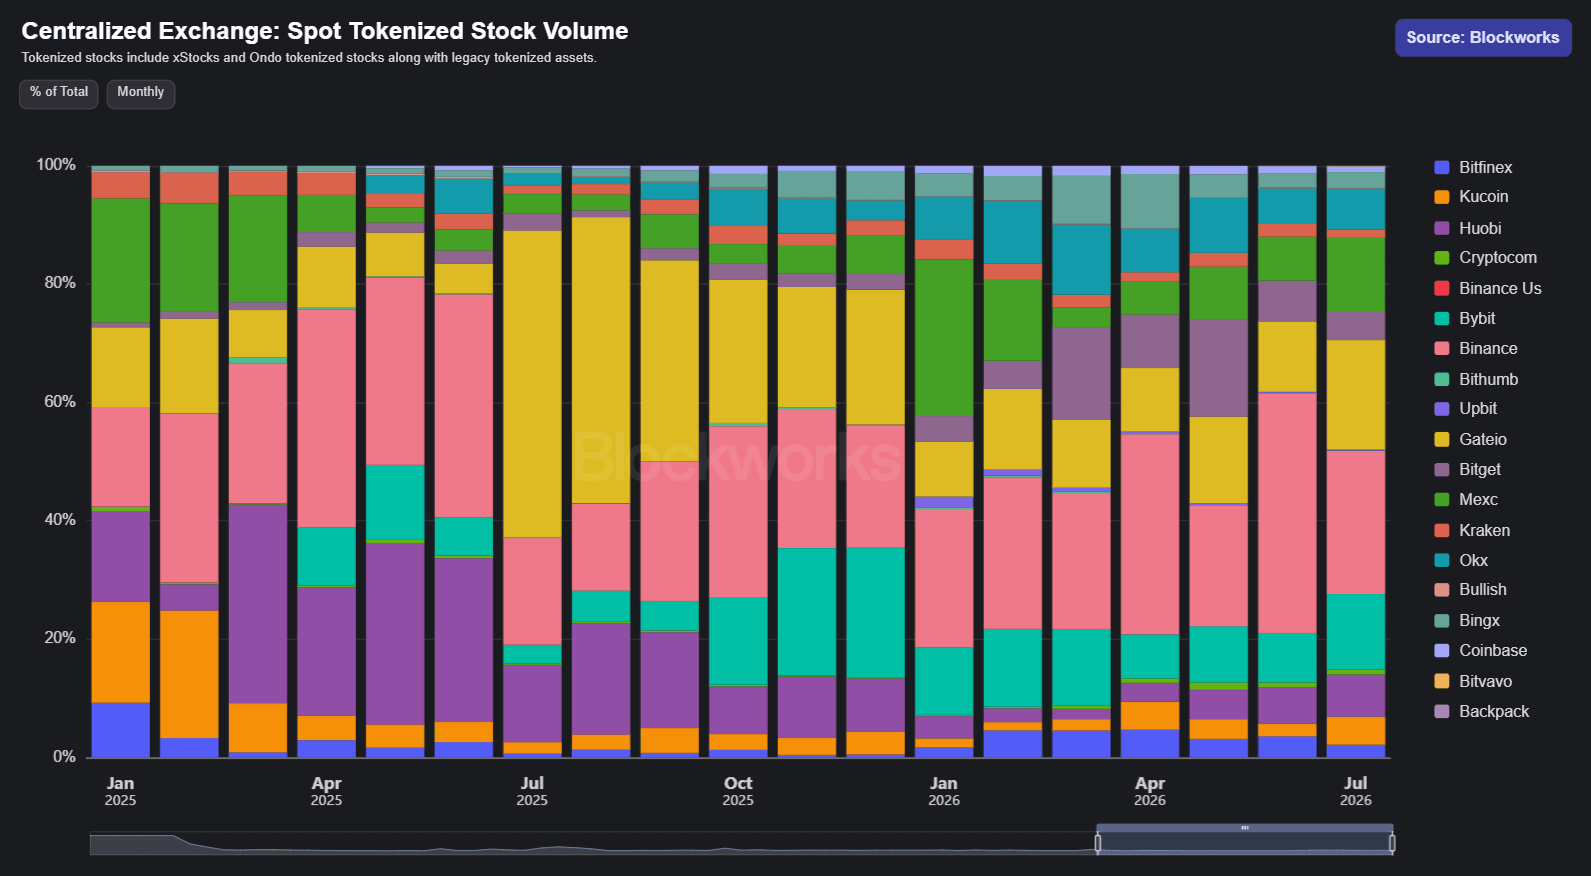
Tokenized stock volume is also concentrated across a small group of exchanges. MEXC has remained one of the leading venues since 2025. In July, it processed $427M in spot tokenized stock volume, ranking fourth behind Bybit, Gate and Binance.
The broader trend in spot is less encouraging. RWAs, forex and tokenized stocks generated around $9.5B in July, down from more than $30B in October 2025. Tokenized stock volumes have grown during parts of this period, but declines across forex and RWAs have pulled the combined market lower.
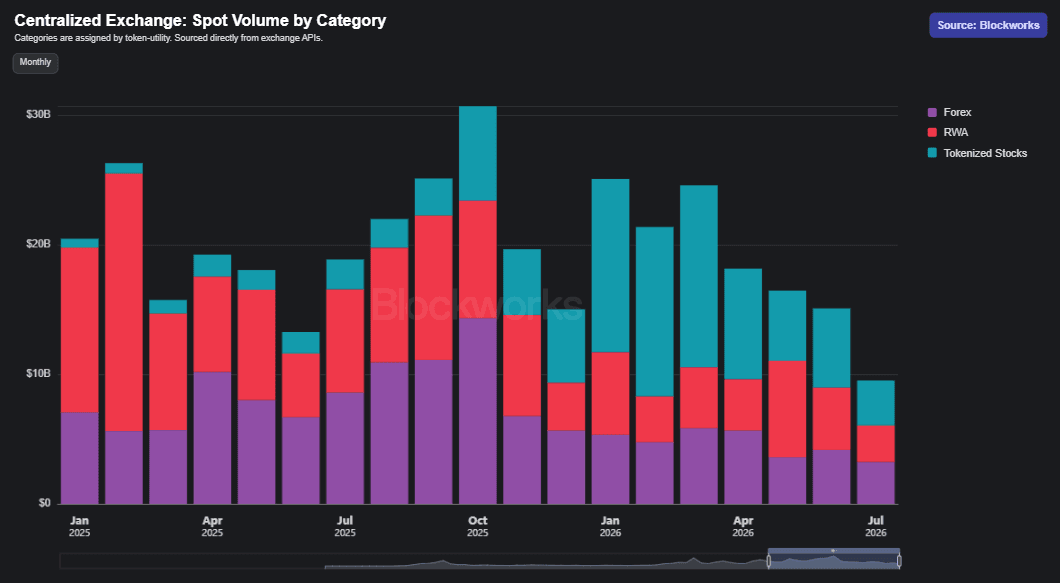
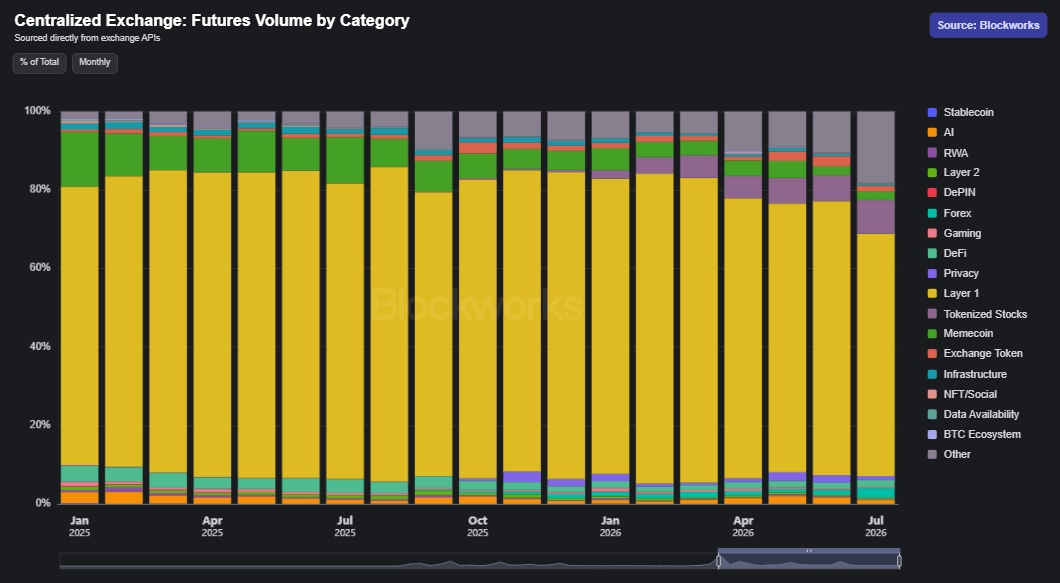
Spot data indicate that demand exists, but it has yet to produce a broad shift in CEX spot activity. Futures markets, on the other hand, have developed much faster. RWAs, forex and tokenized stocks now account for more than 12% of monthly CEX futures volume.
In July, the three categories generated close to $400B, their highest monthly total over the period shown.
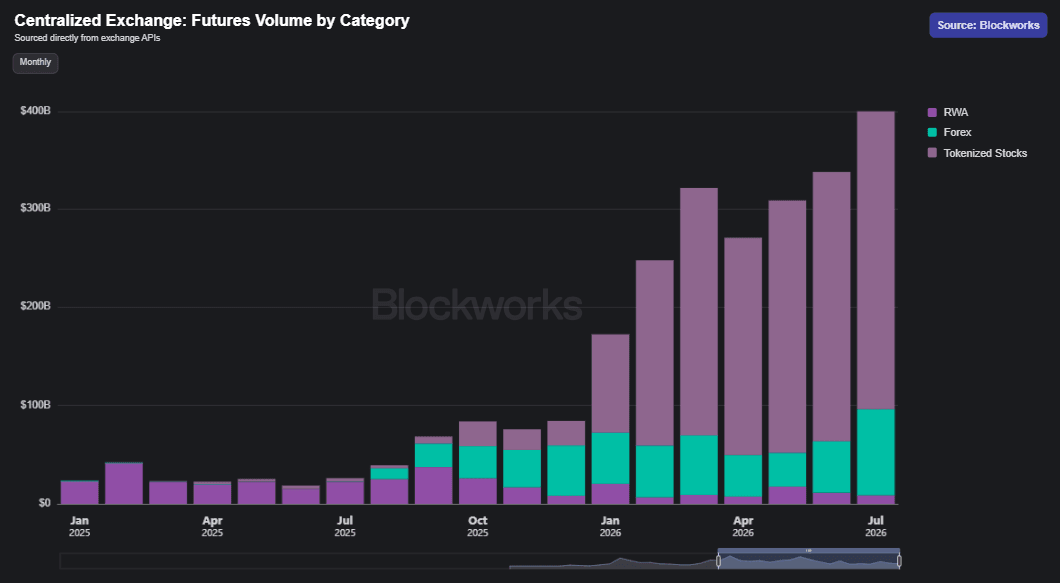
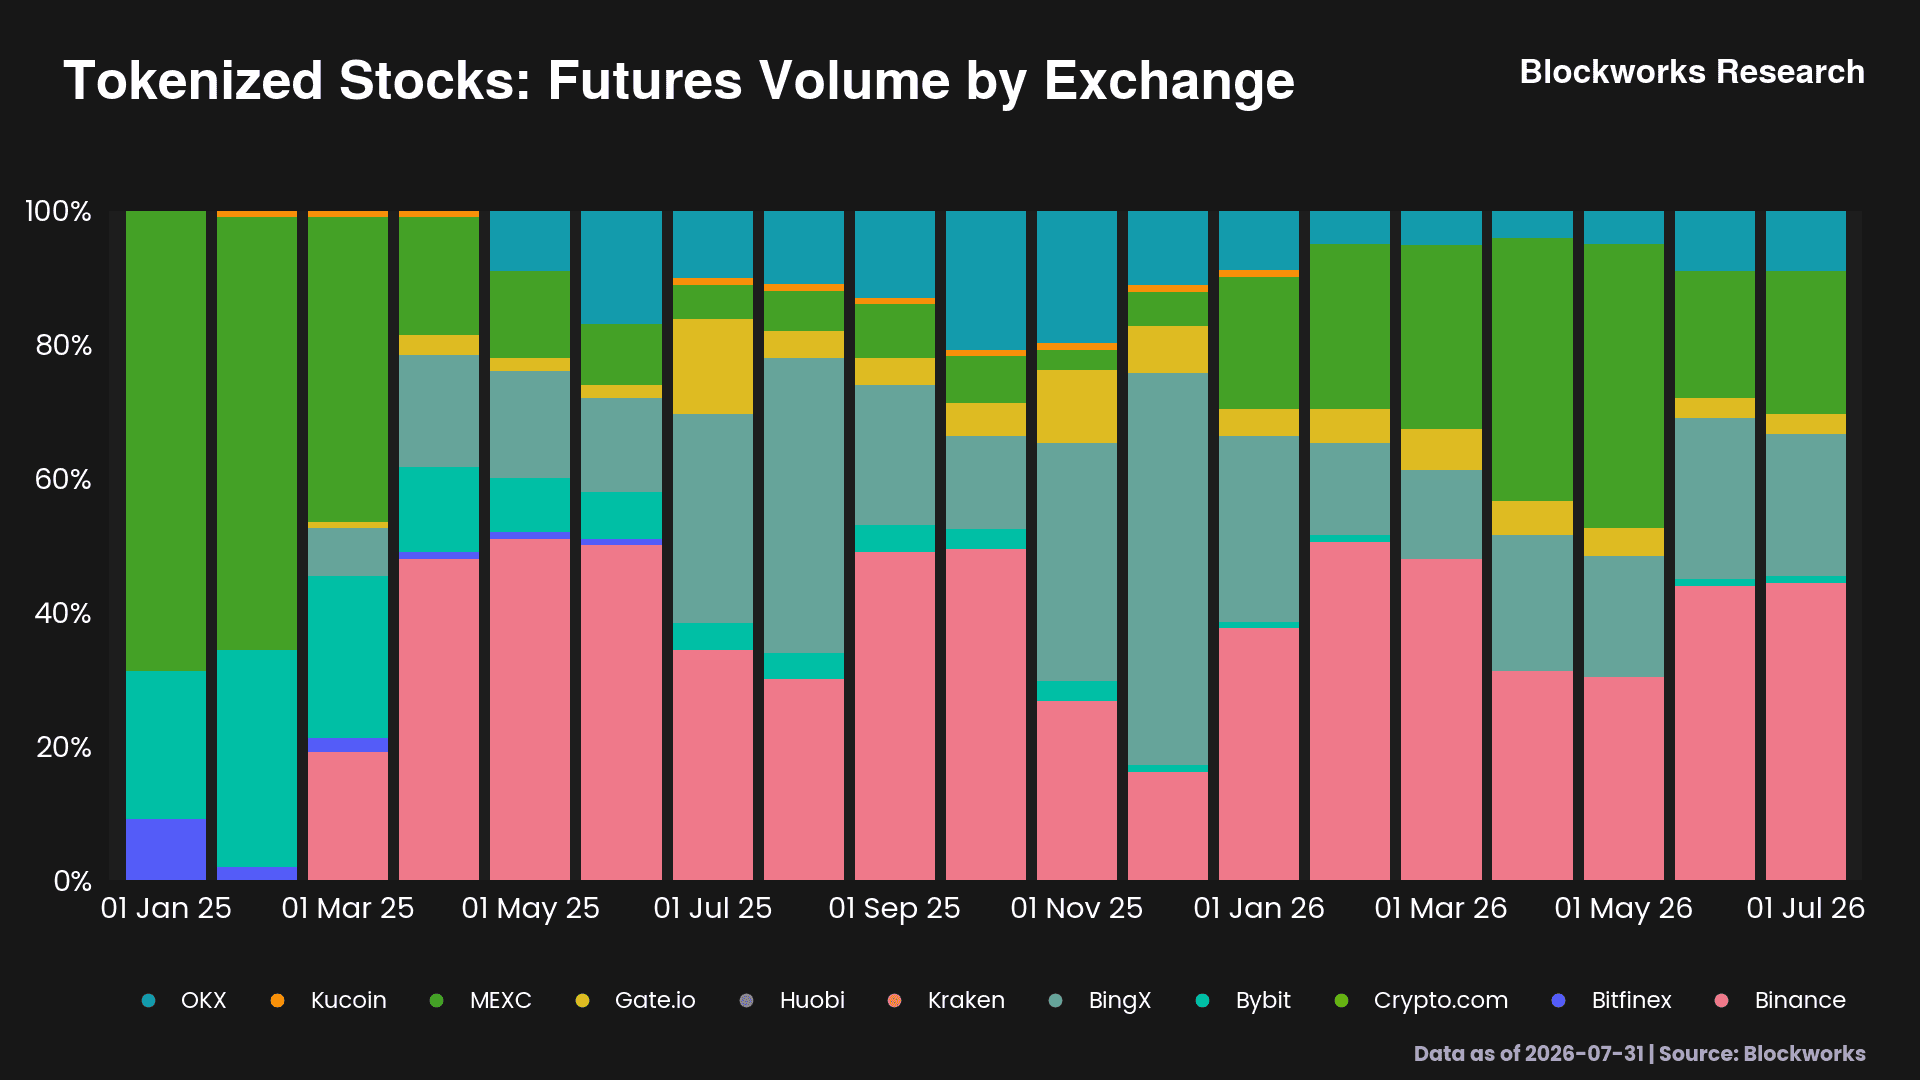
Tokenized stocks have driven most of this growth. Futures volume across the category accelerated throughout 2026 and is now several times larger than the equivalent spot market. Binance remains the leading venue, while MEXC and BingX each account for around 20% of tokenized stock futures volume.
MEXC’s Asia data mirrors this market-wide trend. In Q2 2026, average daily users trading stock futures rose 386% from Q1, while average daily volume increased 3,308%. Through August, Q3 users grew another 51% from Q2 and volume more than doubled, rising 102%.
Growth initially ran fastest in Southeast Asia, where Q2 volume rose 6,648% and users increased 399%. East Asia recorded 1,957% volume growth and a 465% increase in users. The pattern shifted in Q3. Through August, East Asian volume rose another 186% from Q2, compared with 50% in Southeast Asia.
Taken together, the data shows that Asian users are turning to CEXs for traditional assets, but futures remain the main way users are trading them.
The appeal is easy to understand for someone already familiar with crypto markets. Perpetuals allow traders to move between long and short exposure, take larger positions with less upfront capital and avoid managing an expiry date. The user can also trade Nvidia, gold or an equity index through the same interface and stablecoin balance already used for crypto.
The popularity of leverage also needs to be viewed within the financial circumstances facing younger investors across Asia. Traditional paths to wealth accumulation have become harder in many of the region’s major cities. Housing provides the clearest example. In Hong Kong, the median apartment price was 23.4 times median annual household income in 2025.
For younger investors starting with limited savings, markets can feel like one of the few available ways to accelerate wealth creation. Products that provide meaningful exposure from a small amount of capital naturally attract attention. The same structure also magnifies losses when the trade moves in the wrong direction.
South Korea showed how quickly this demand can build and unwind. Single stock leveraged ETFs tied to Samsung Electronics and SK Hynix became a major source of market activity within months of launching. These products accounted for 33.4% of KOSPI trading on July 30 as the market experienced a sharp reversal. Regulators responded by raising deposit requirements and restricting new listings. By August 1, the products’ share of trading had fallen to 5.4%.
Futures have given CEXs an effective entry point into traditional assets, but the current imbalance leaves much of the market dependent on leverage and short term speculation. The larger opportunity is to convert these traders into spot users and build products they continue using after appetite for leverage cools.
Asia Already Has the Crypto Rails
For many Asian crypto users, trading gold or a US stock on a CEX requires less adjustment than opening a brokerage account. From June 2024 to June 2025, onchain transaction value across APAC grew 69% year over year, the fastest rate of any region. This was also a sharp acceleration from the 27% growth recorded over the previous period. Latin America followed at 63%, while growth across North America, Europe and MENA was slower.
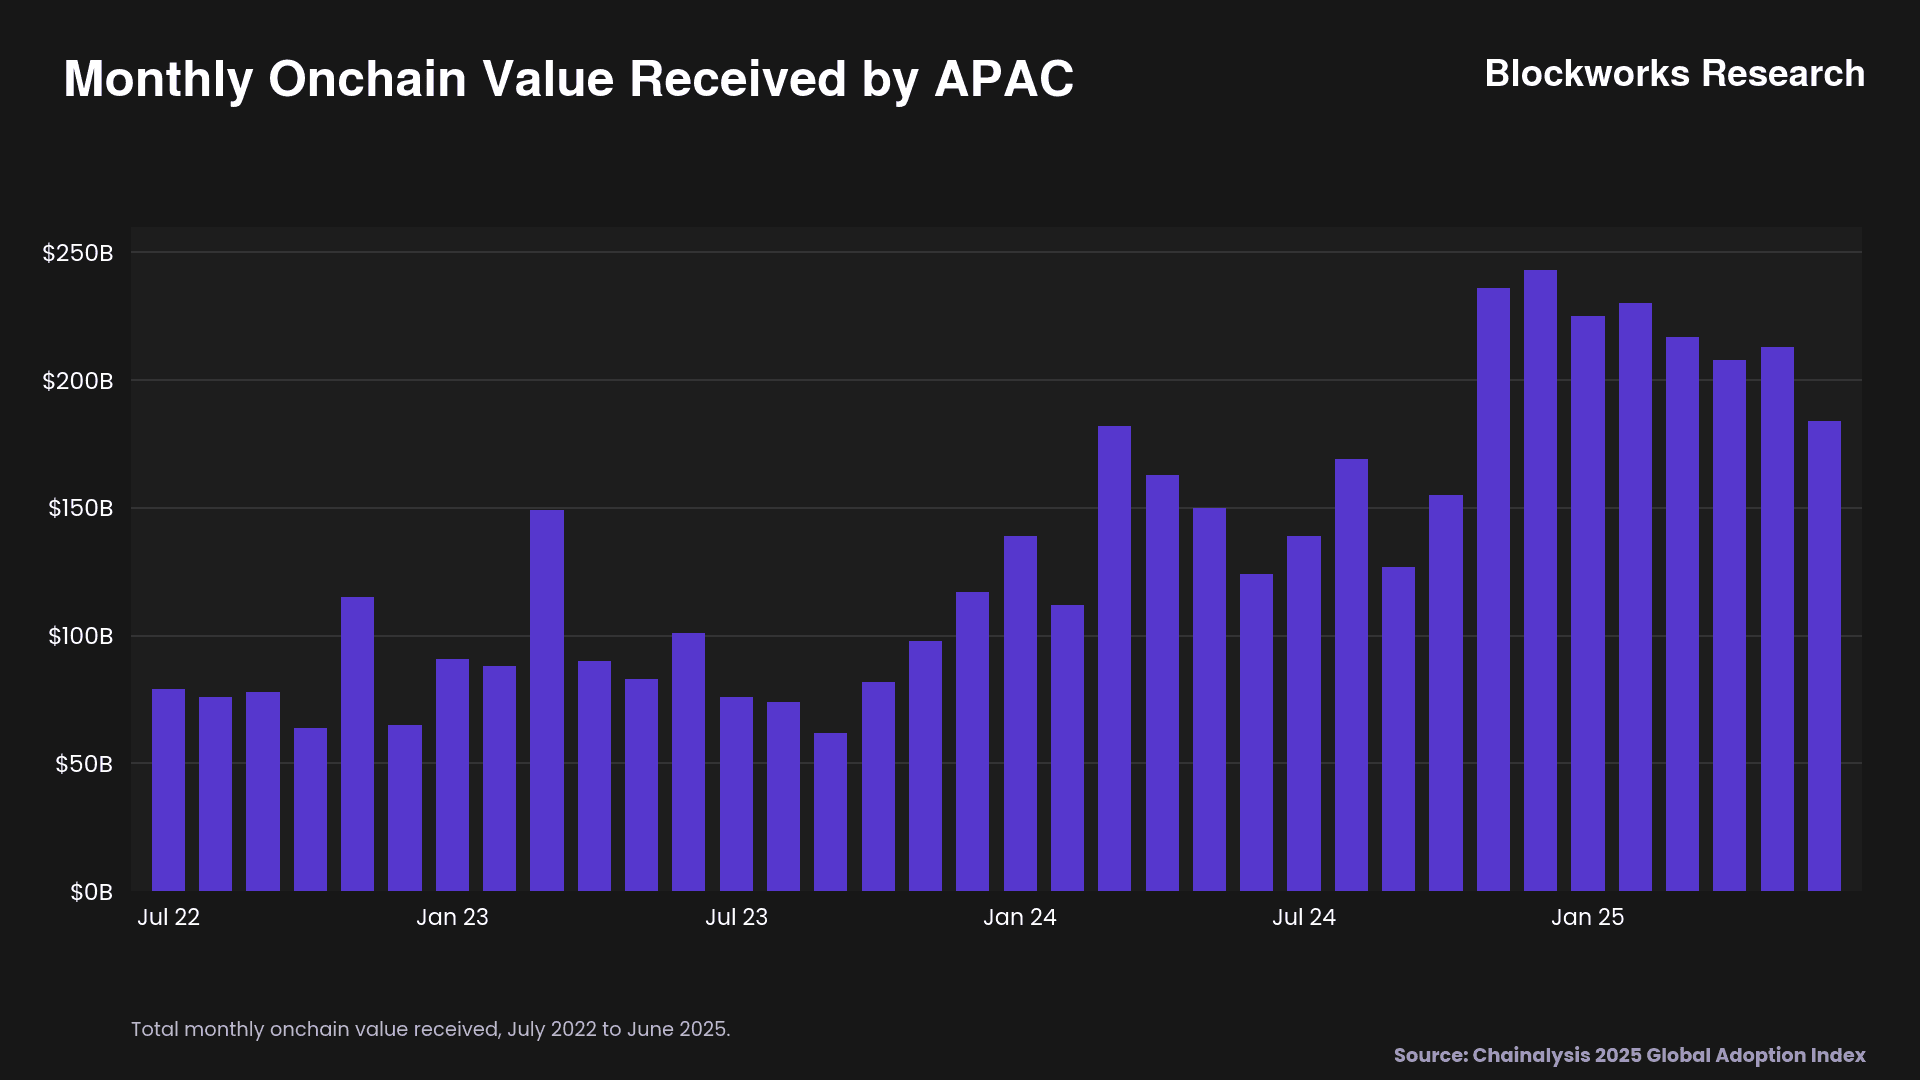
In addition, monthly onchain value received across APAC rose from around $80B in July 2022 to a peak of nearly $245B in late 2024. It remained between $185B and $230B throughout the first half of 2025.
Adoption is also spread across the region. Vietnam ranked fourth, Indonesia seventh and the Philippines ninth in Chainalysis’ 2025 Global Crypto Adoption Index. Crypto use in Asia is therefore not just limited to established financial centres such as Hong Kong and Singapore.
Stablecoins are an important part of this foundation. OECD’s research estimates that Asia accounted for roughly 30% of global stablecoin trading activity in 2025. For many users, stablecoins already function as the cash balance they use to move between trades.
A user holding USDT on a CEX can therefore move from Bitcoin into gold, equities or an index without transferring money back to a bank, opening another account or learning a new platform. The exchange already holds the balance and the user already understands the trading mechanics.
This gives CEXs an advantage as they expand beyond crypto. Adding traditional assets increases what users can do with an account they already use, while allowing the same capital to move across crypto, commodities and equities. Much of the infrastructure and user behaviour required for cross asset trading is already in place across Asia.
Where Traditional Brokers Still Add Friction
Markets can move on Saturday even when brokers cannot.
This gap has become apparent multiple times this year with various market moving events happening on the weekend. US strikes on Iran took place over the weekend of February 28, 2026, sending WTI up as much as 15% on Hyperliquid. Investors using traditional venues had to wait for markets to reopen before adjusting their positions.
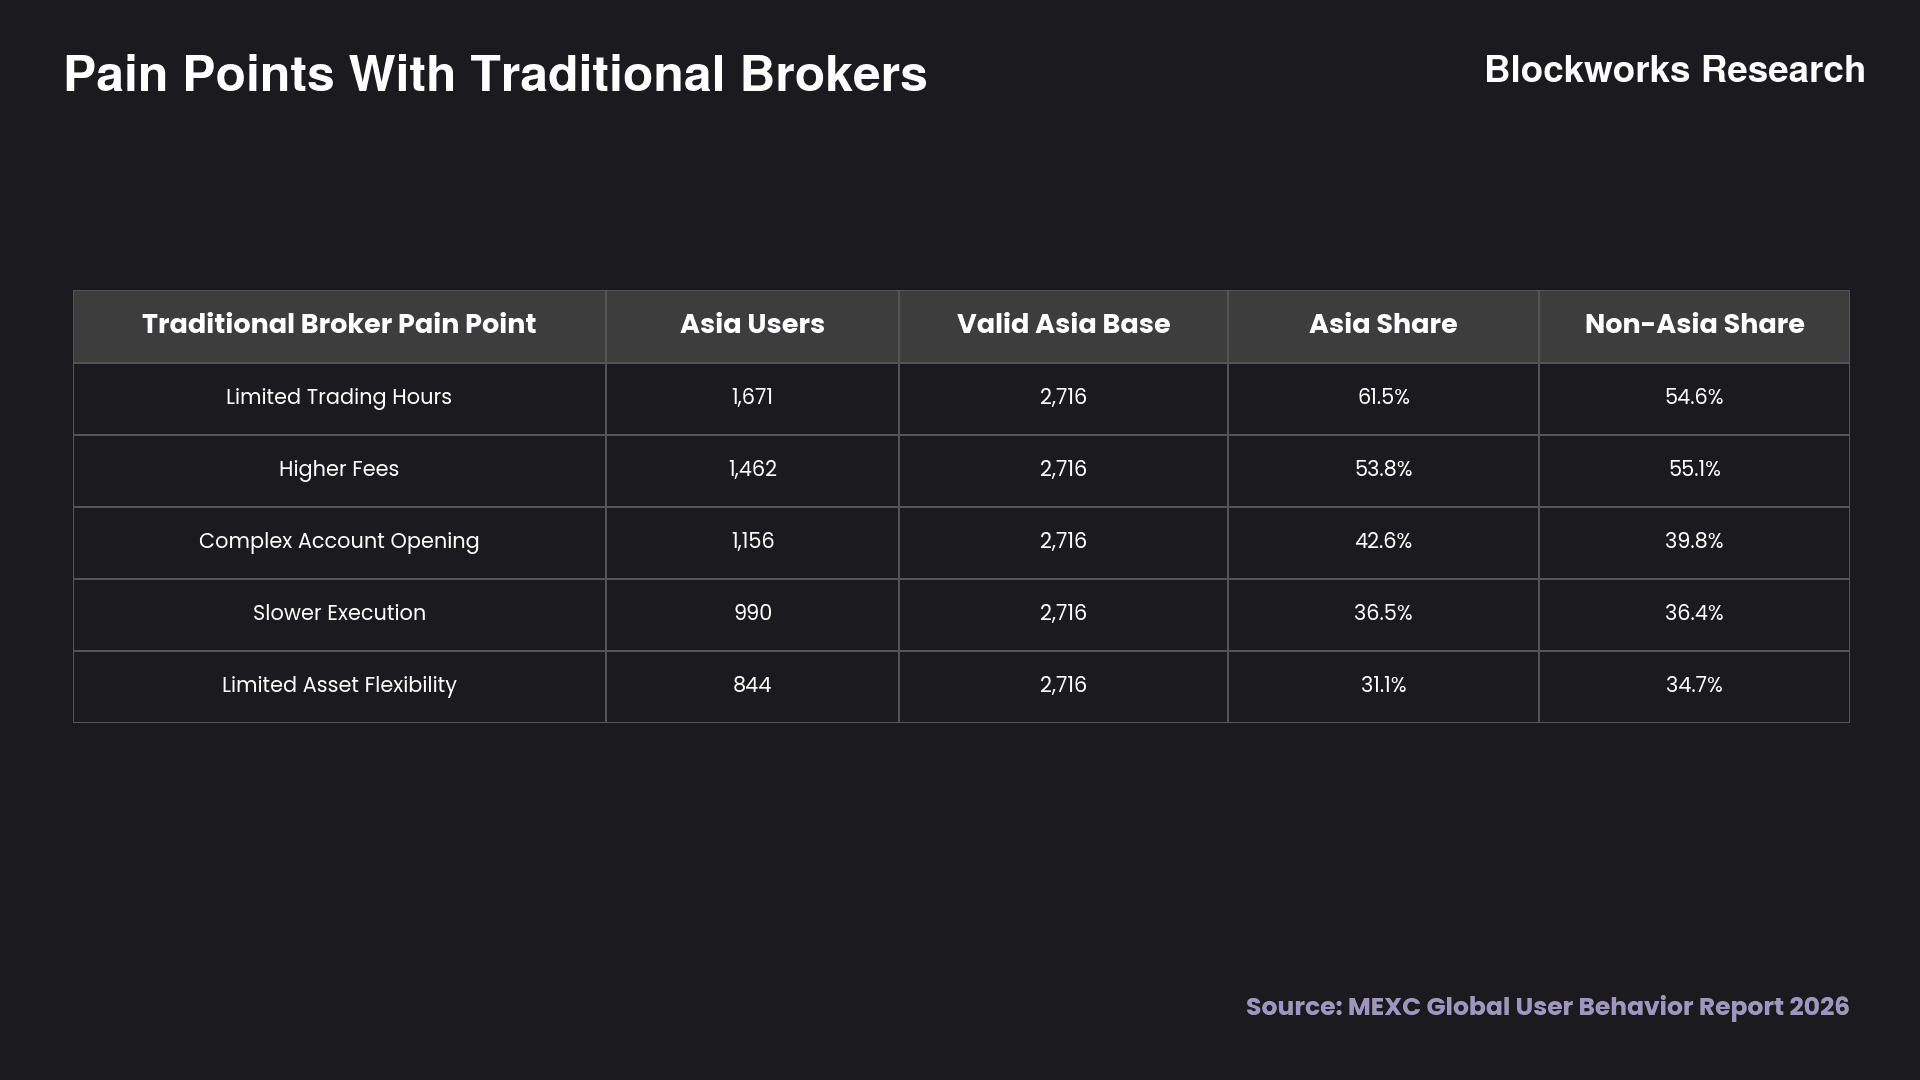
This helps explain the results of MEXC’s survey. Among surveyed Asian users, 61.5% described traditional broker trading hours as limited. More strikingly, 75.1% had encountered a major event that required trading while traditional markets were closed. In such a situation, 79% said they would consider using a crypto platform to establish a gold or oil position.
CEXs allow users to respond while the underlying market is closed. Traders can reduce risk or express a view before conventional markets reopen.
Cost is another source of friction. MEXC currently offers zero fee trading across stock futures, tokenized stocks and RealStocks through a promotional program. Binance charges 0.05% on larger direct equity orders, a fixed fee on smaller orders and taker fees of up to 0.04% on TradFi Futures.
These figures compare with Asian brokers such as Tiger Brokers, where a US equity trade can include a $0.005 per share commission, a separate $0.005 per share platform fee and a $0.003 per share settlement fee.
However, competition from CEXs and other brokers has pushed fees lower. Webull and Moomoo now offer zero commission US equity trading, meaning CEXs will not always be cheaper. Their pricing is still attractive especially for users who already hold their capital in stablecoins. Even with more low cost options entering the market, 53.8% of surveyed Asian users identified higher fees as a problem with traditional brokers.
Account opening adds a final layer. Around 42.6% of surveyed Asian users cited complex procedures. Someone already using a CEX can access an equity or commodity pair without opening and funding another financial account. The user can trade through an existing balance and interface. This matters because 83.9% of surveyed Asian users already rely primarily on CEXs for crypto trading.
The appeal of CEXs therefore comes from reducing the number of steps between an event and a trade.
Why Gold Came First
Gold was a natural starting point for cross asset trading on CEXs. Asian investors were already familiar with the asset and had a long history of using it to preserve wealth. That preference was reflected in ETF flows. In Q1 2026, Asian gold ETFs added 215 tonnes and attracted $25B in net inflows, the second strongest increase of any region.
The same preference is visible among MEXC users. Around 62.6% of surveyed crypto native users in Asia primarily trade precious metals through CEXs, the highest share across all regions. The survey also found that 87.2% of Asian users had traded CEX derivatives linked to gold, silver or other precious metals.
MEXC’s trading activity in Southeast Asia supports these findings. In Q2 2026, average daily gold futures volume rose 18% from Q1, while average daily users trading spot gold increased 42%, the fastest growth across East, South and Southeast Asia.
MEXC’s position in precious metals extends beyond Southeast Asia. CoinGecko ranked it first among six exchanges by precious metals trading volume in both April and May 2026. Its volume reached $72.12B in April and $85.15B in May, compared with Binance’s $65.52B and $57.85B over the same months.
Open interest (OI) gives a better sense of whether this demand is sticking. Volume can rise when the same capital is traded repeatedly. OI increases when new positions are opened faster than existing ones are closed. Rising OI therefore shows that more exposure is staying in the market instead of being quickly opened and closed.
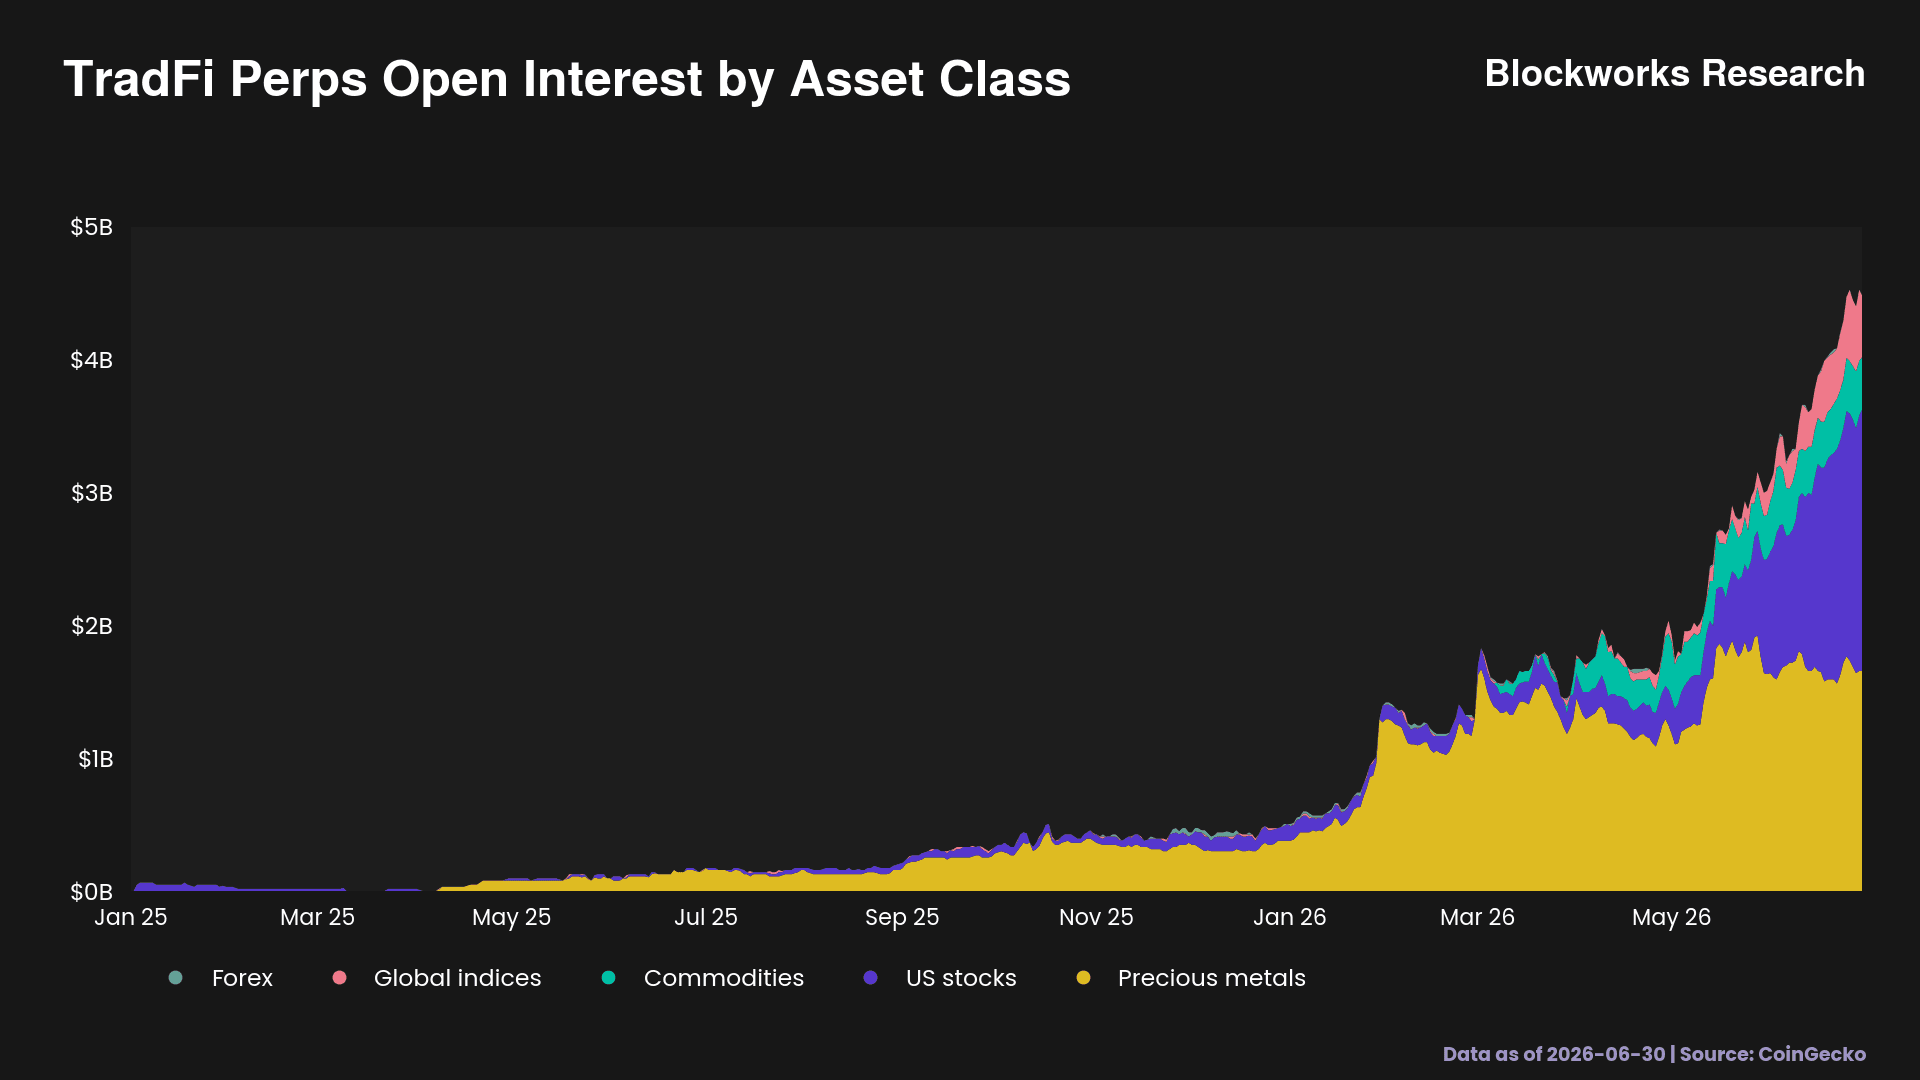
Gold was central to this build-up. Precious metals OI peaked at $1.98B in May and remained at $1.69B by the end of June, accounting for 36.2% of the total OI. Traders continued to hold significant exposure even as activity expanded into other assets.
US stocks overtook precious metals in June, but precious metals remained one of the market’s two largest categories. Combined with MEXC’s gold trading data, this suggests gold was an important entry point before users expanded into a broader range of assets.
Gold has therefore found a clear product market fit within crypto markets. It combines an asset Asian users already understand with trading infrastructure they already use. The challenge is whether CEXs can build similar demand across equities and other commodities while improving the infrastructure and safeguards around these products.
What the Next Phase Requires
MEXC’s survey suggests demand can support further growth. Around 91.9% of surveyed Asian users expect the tokenized commodities market to continue expanding. The same users are also clear about what could hold it back. Lack of knowledge was the most common concern at 51.2%, followed by market volatility at 43.8%, regulatory uncertainty at 37.2% and liquidity at 36.3%.
Building Spot Demand
Recent losses linked to leveraged trading on traditional brokerages and the popularity of leveraged ETFs have already attracted regulatory attention. Equity and commodity futures on CEXs could face similar questions around maximum leverage, user suitability and liquidation disclosures. Exchanges that rely too heavily on leveraged volume may need to adjust as these products receive more attention from regulators.
The larger opportunity is to convert interest in futures into demand for spot products. A mature cross asset market should have meaningful activity across both. MEXC’s PAXG market is already approaching this balance. From January through July 2026, PAXG generated $2.02B in spot volume and $2.03B in futures volume.
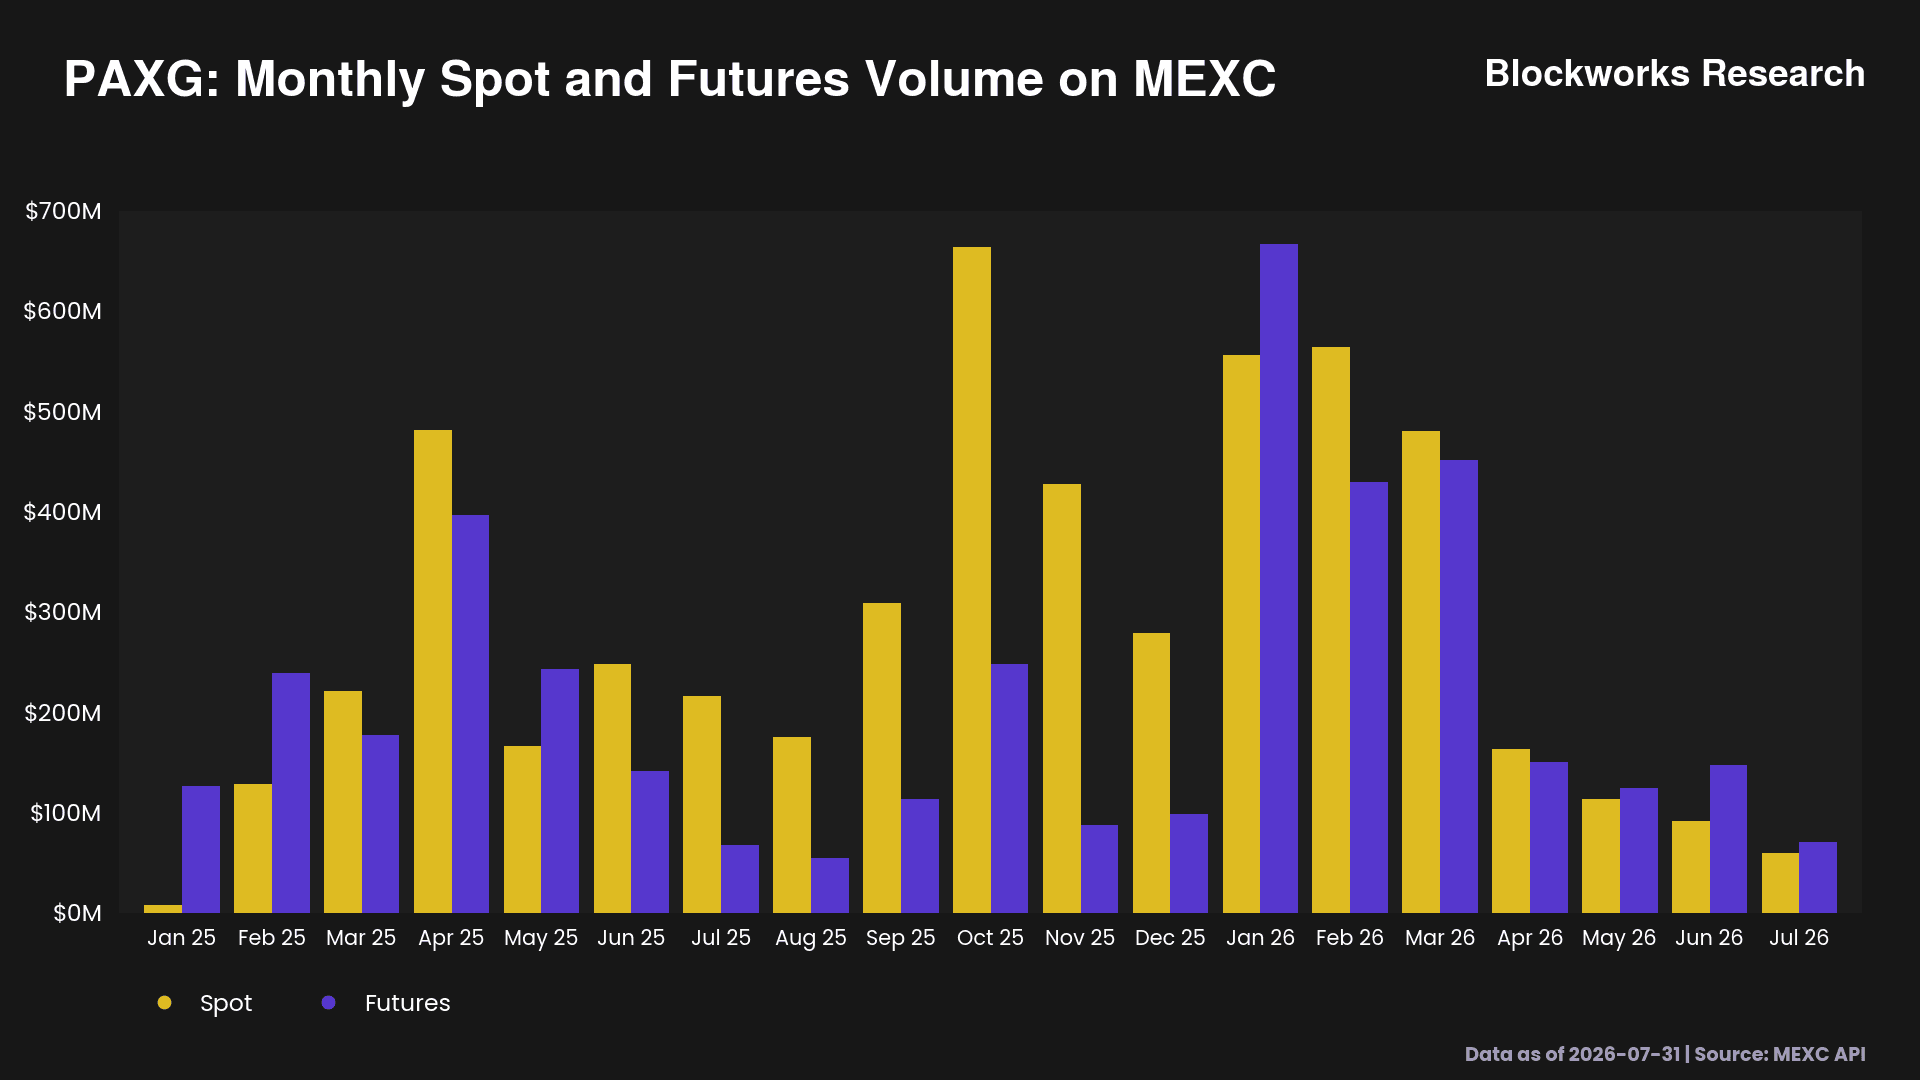
The monthly ratio between futures and spot remained between 0.8 and 1.6 over the period. The next test for MEXC is whether a similar mix can develop across more equity and commodity pairs.
Education and Price Transparency
Bringing more users into these markets also creates an education challenge. A tokenized asset and a perpetual contract can appear beside each other on the same interface while providing very different forms of exposure.
Traders need to know whether they have a claim on the underlying asset or are trading a derivative that only tracks its price. Concepts such as funding rates may also be unfamiliar to users entering from spot markets. Funding payments can reduce returns, while leverage increases the risk of liquidation. These risks are not always clear from the trading interface.
The need for transparency becomes greater when the underlying market is closed. Platforms should explain how their index and mark prices are calculated, which data sources their oracles use and how funding rates are determined. Traders also need to understand how a gap when the traditional market reopens could affect their position.
Building Weekend Liquidity
Price transparency is closely connected to weekend liquidity. During regular market hours, a market maker quoting an equity or commodity perpetual can offset its exposure through the underlying asset or a traditional futures market. That route disappears when those markets close.
The market maker must carry the exposure until trading resumes. This additional risk leads to wider spreads and smaller quoted sizes, making execution more expensive for users at the moment they may need liquidity most.
Exchanges could incentivise market makers for maintaining a minimum level of weekend liquidity. Better collateral management and access to other round the clock hedging venues could potentially reduce some of the risk.
Decentralized Venues Are Moving Quickly
While CEXs work through these challenges, decentralized venues are expanding into the same markets. Hyperliquid processed $70.8B in stock perpetual volume during July, alongside $27.3B in index volume, $16.2B in commodities and $205M in forex. Together, these markets accounted for 51% of its volume that month.
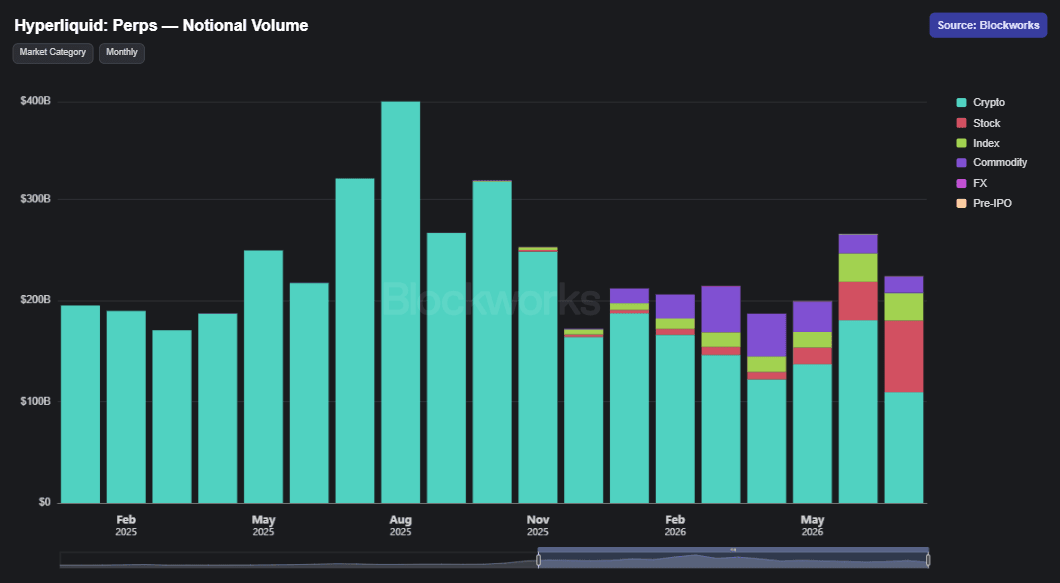
Hyperliquid’s HIP-3 framework helps explain the speed of this expansion. External builders can launch perpetual markets without waiting for a central party to approve each listing. TradeXYZ recently used this framework to launch Unitree perpetuals ahead of the Chinese robotics company’s planned Shanghai listing. This gave global traders synthetic exposure before its shares began trading.
Spot products are beginning to follow. In August, xStocks launched five tokenized US stocks and ETFs as native spot markets on HyperCore. The number and variety of traditional asset markets on Hyperliquid have grown rapidly since late 2025, increasing the competitive pressure on CEXs.
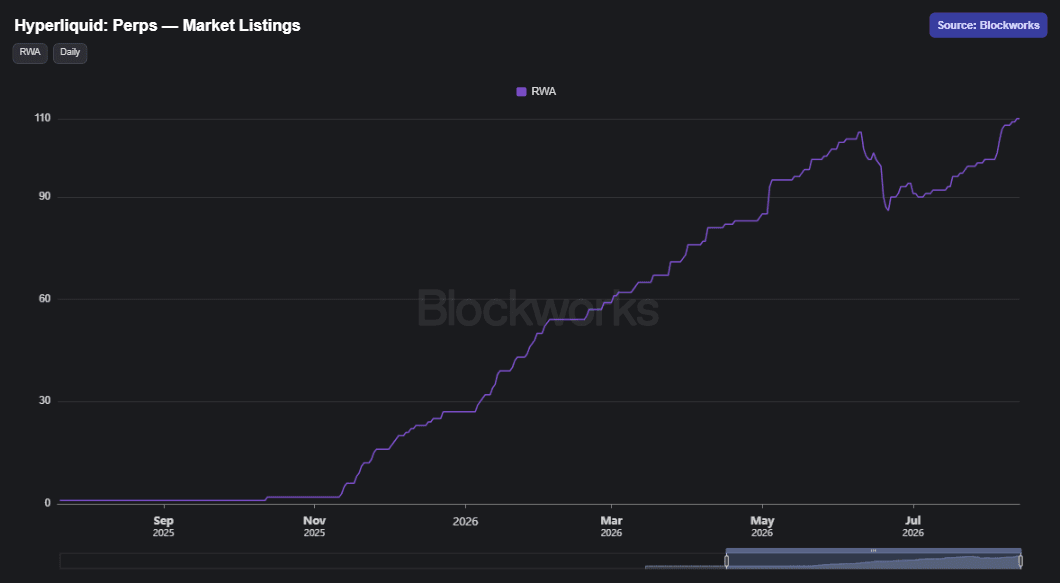
For CEXs, competing on listing speed may require looking beyond internal product development. They can invest in similar decentralized products, integrate decentralized liquidity and work directly with tokenization providers. MEXC Ventures has identified three areas where investment could support the market’s next phase: asset issuance and tokenization, trading infrastructure, and custody and settlement.
Investing in asset issuance and tokenization could give exchanges more control over listing speed and product variety, helping them compete with decentralized venues that have been quick to launch new markets. It could also enable markets that traditional brokers rarely offer, such as compute futures.
Trading infrastructure is another investable area. CEXs can back market makers, liquidity aggregation platforms, hedging venues and providers of pricing and oracle infrastructure. These investments could deepen order books and improve weekend pricing, helping CEXs offer a better experience than traditional brokers.
Custody and settlement will become particularly important as the market scales. Exchanges need to ensure that tokenized assets are properly backed, ownership claims are clear and trades can settle reliably. Stronger infrastructure across these areas will help the market develop beyond speculative futures and support greater spot adoption.
Growth from here will depend on whether exchanges can broaden spot demand while improving product education, weekend liquidity and the safeguards around leveraged trading.
Conclusion
Asia has a strong foundation for cross asset trading on CEXs. Investors in the region already have shown demand for assets such as gold and US equities, while high crypto and stablecoin adoption makes accessing these markets through an exchange feel familiar.
The next phase will depend on whether CEXs can build deeper spot markets alongside their futures products. Better liquidity, clearer disclosures and stronger safeguards around leverage will be important as more traditional assets are listed. Platforms also need to improve pricing and risk management when the underlying markets are closed.
Meeting this demand will require investment beyond exchanges. As CEXs and DEXs list more traditional assets, they will need tokenization providers that can bring products to market quickly, alongside market makers, pricing systems and oracles that support 24/7 trading. Growth in spot markets will also place greater importance on custody and settlement, where users need confidence that assets are properly backed.
If this infrastructure develops, CEXs can become an important access point for traditional assets across Asia, extending their role beyond crypto trading.
The information contained in this report and by Blockworks Inc. and related affiliates is for general informational purposes only and is not intended to provide legal, financial, or investment advice. The report should not be construed as an offer or solicitation to buy or sell any security, token, or financial instrument and does not represent any recommendation or endorsement of any investment or financial product or service. Blockworks Inc. and related affiliates are not registered as a securities broker-dealer or an investment advisor in any jurisdiction or country.