
Maple’s Missing Rally
Key Takeaways
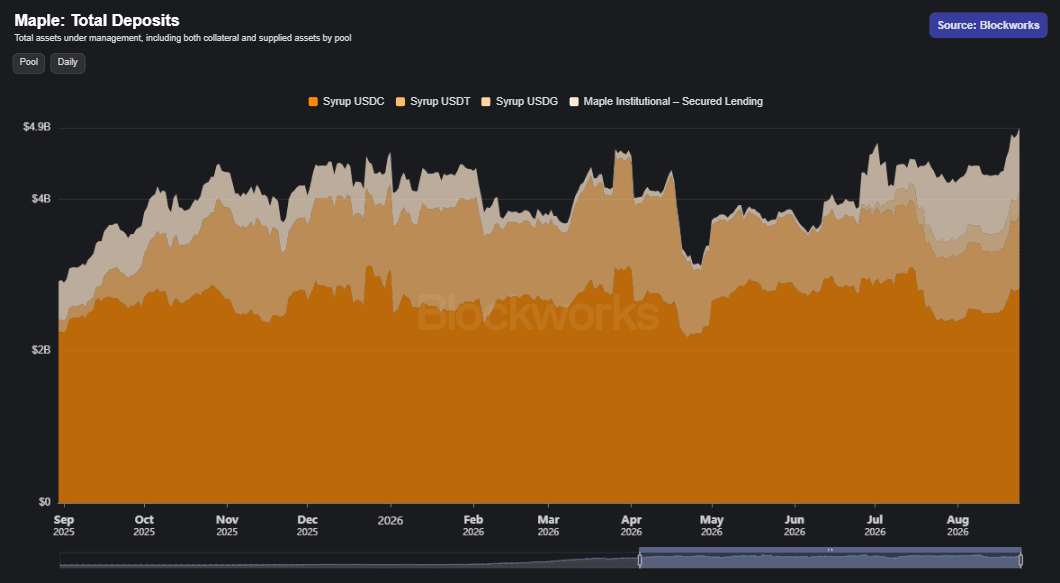
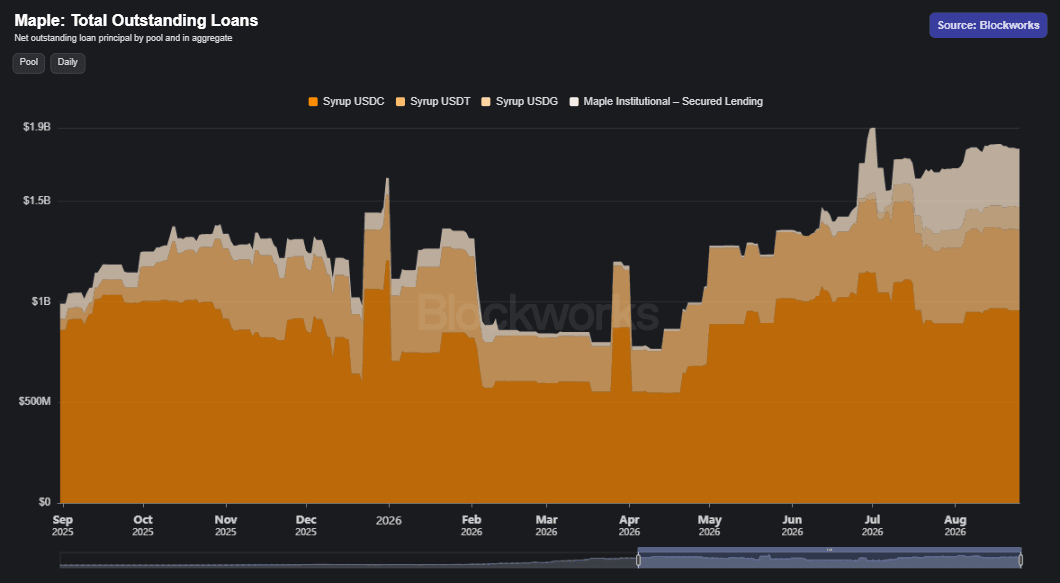
- Maple has grown through a weak lending market. Deposits increased 69% to $4.9B and outstanding loans rose 78% to $1.8B over the last year, while SYRUP fell 52% over the same period.
- Robinhood could become a major source of deposits. Its savings vault has reached $387M in two months, with 24% allocated to syrupUSDG. Our scenario implies up to $1.2B in additional Maple deposits from this product alone.
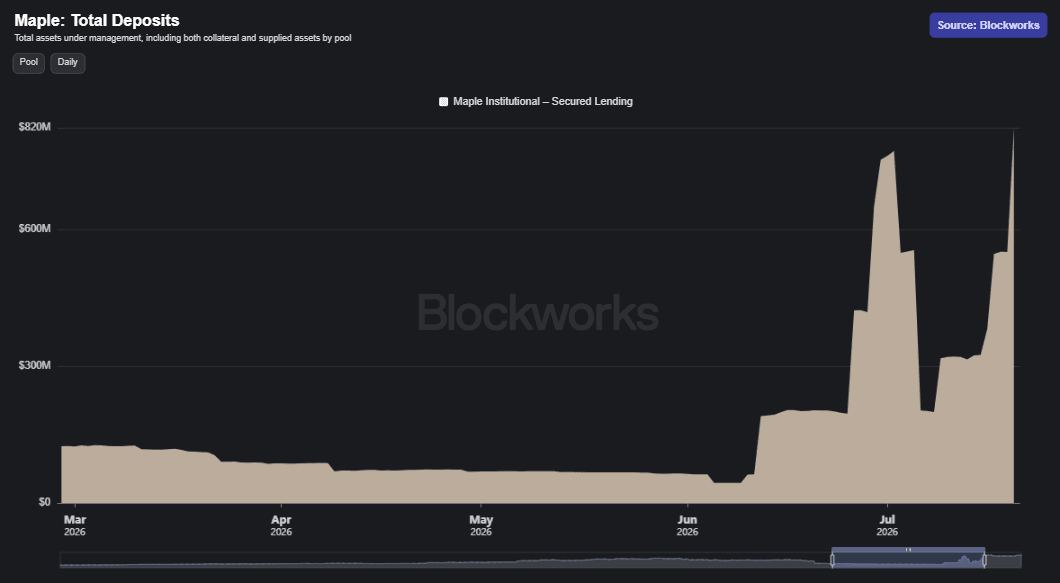
- Kraken strengthens the other side of Maple’s marketplace by sourcing institutional borrowers. Since the warehouse facility was announced, deposits in Maple Institutional have risen from $200M to $823M.
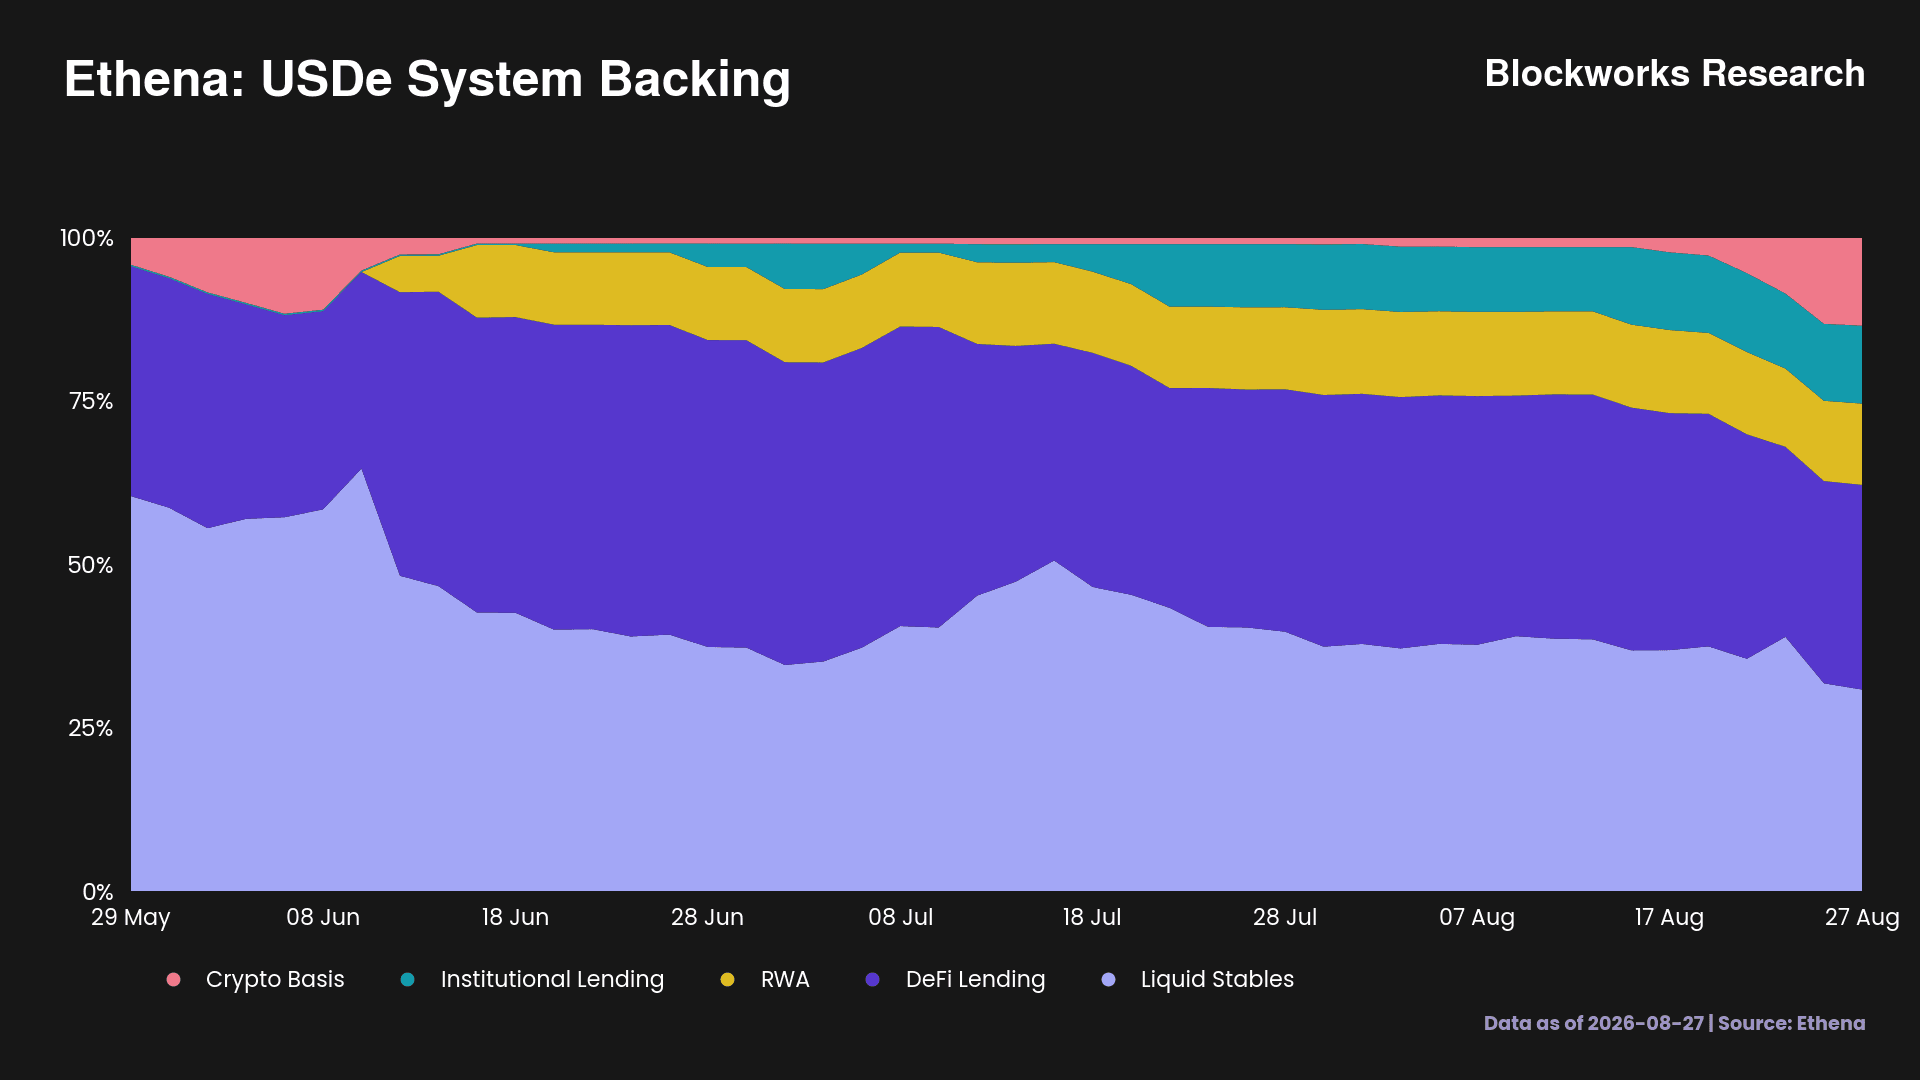
- Ethena provides another source of upside. Institutional lending accounts for 12% of USDe’s backing, with 62.5% of that capital, or roughly $302M, allocated to Maple Institutional.
- MIP-021 replaced discretionary buyback allocations with a rules-based framework tied to monthly revenue, with the first buyback under the new framework completed in August 2026. Had the framework been active over the past year, $5.1M of Maple’s $22.1M in revenue would have been used to repurchase SYRUP.
- SYRUP appears 33% to 65% undervalued relative to median peer multiples. Further fintech partnerships or renewed revenue growth could drive a rerating.
- Rate compression remains the main risk. Lower supply rates have kept revenue flat despite deposit and loan growth, which could slow buybacks and delay the rerating.
Introduction
Crypto markets have turned higher, and lending has moved with them. The sector is up 46.7% over the past week, making it the strongest performer across the sectors tracked by Blockworks Research. As market activity returns, demand for leverage and yield usually follows, making lending one of the clearest reflections of market conditions.
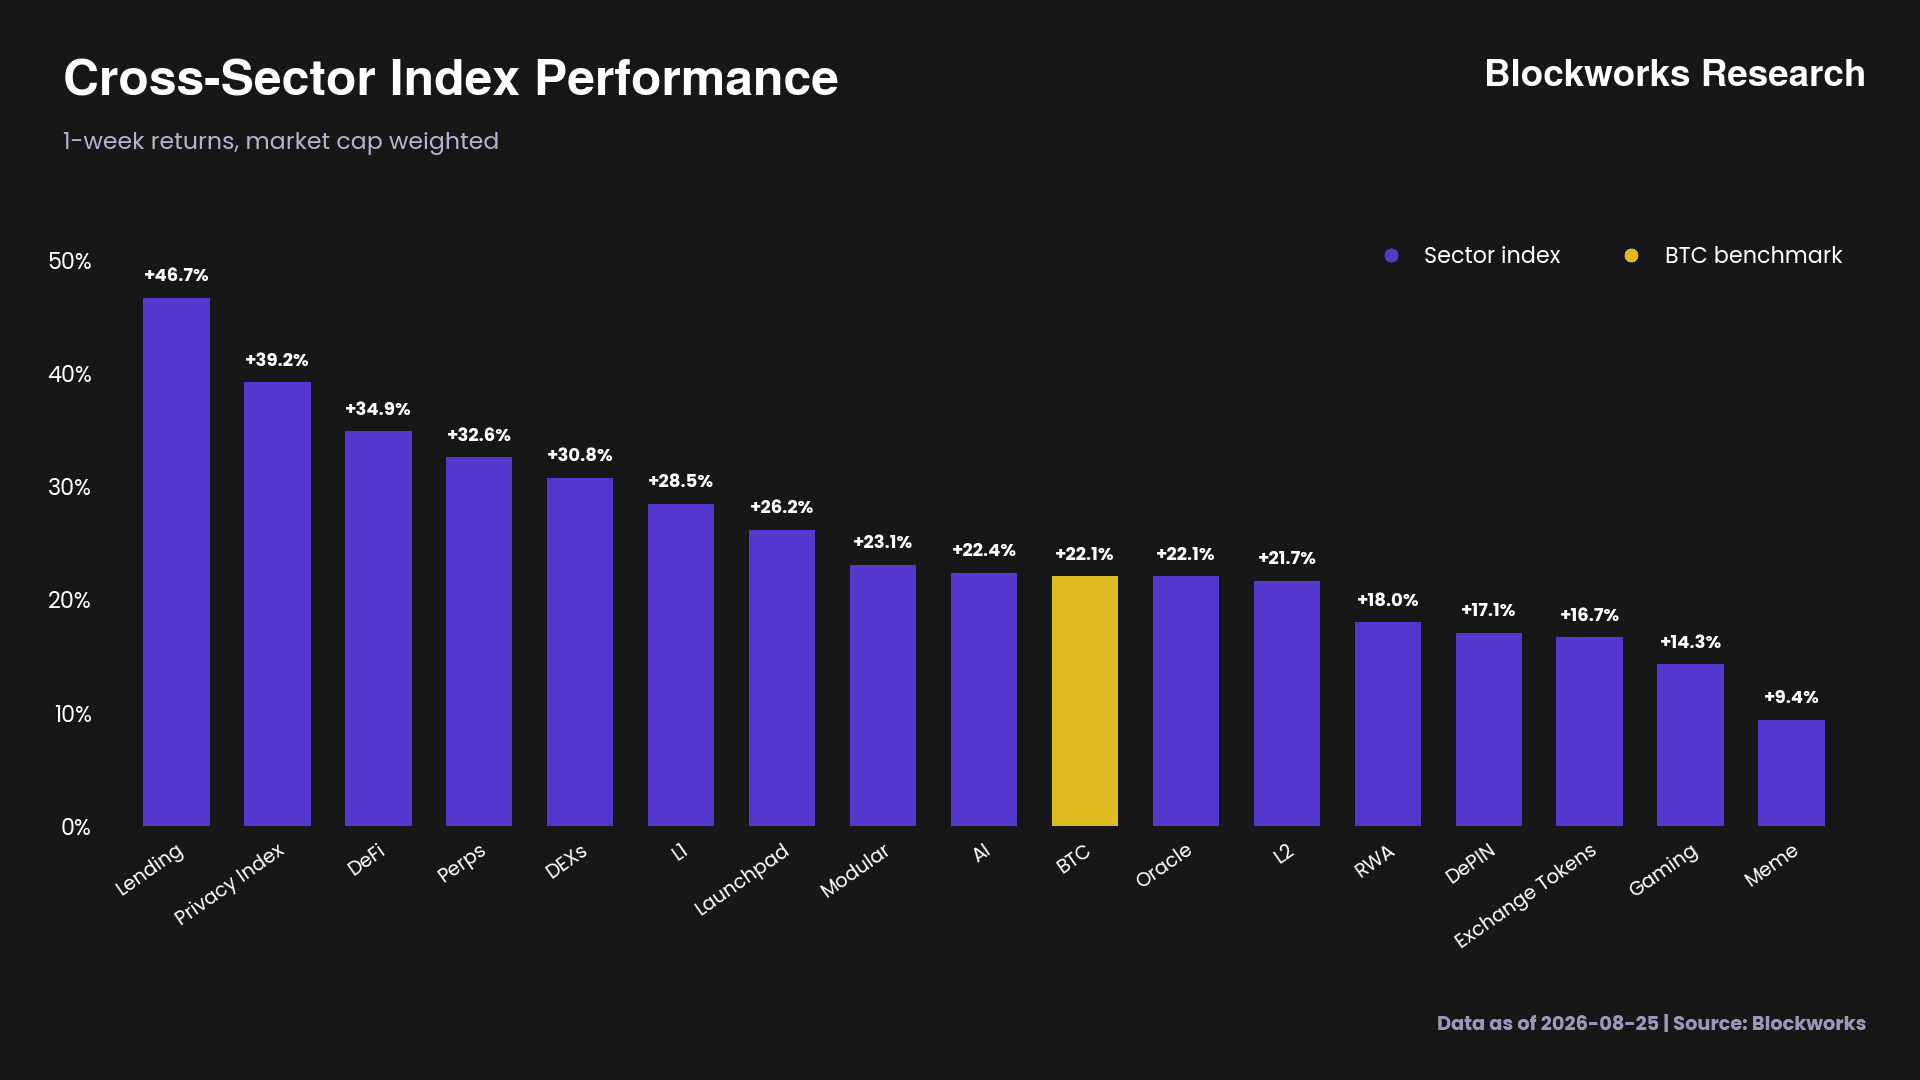
Looking deeper into the index, SYRUP has participated in the rally but continues to lag much of the lending sector. That underperformance stands out because Maple’s core metrics continued to improve through a much weaker market.
With stronger fundamentals, wider distribution through Robinhood and Kraken, and a rules-based buyback framework replacing discretionary allocations, we believe SYRUP is due for a rerating. The market has yet to price in how these new channels could drive Maple’s next phase of growth.
Growing Against the Cycle
A look at Maple’s metrics over the past year paints a strong investment case. Total deposits are up 69%, from $2.9B in September 2025 to $4.9B today.
Any concerns about Maple’s ability to source borrowing demand should also be eased by the growth in outstanding loans, which have increased 78% from $990M in September 2025 to $1.8B today. Borrowing demand fell sharply between February and mid-April, but has recovered strongly since.
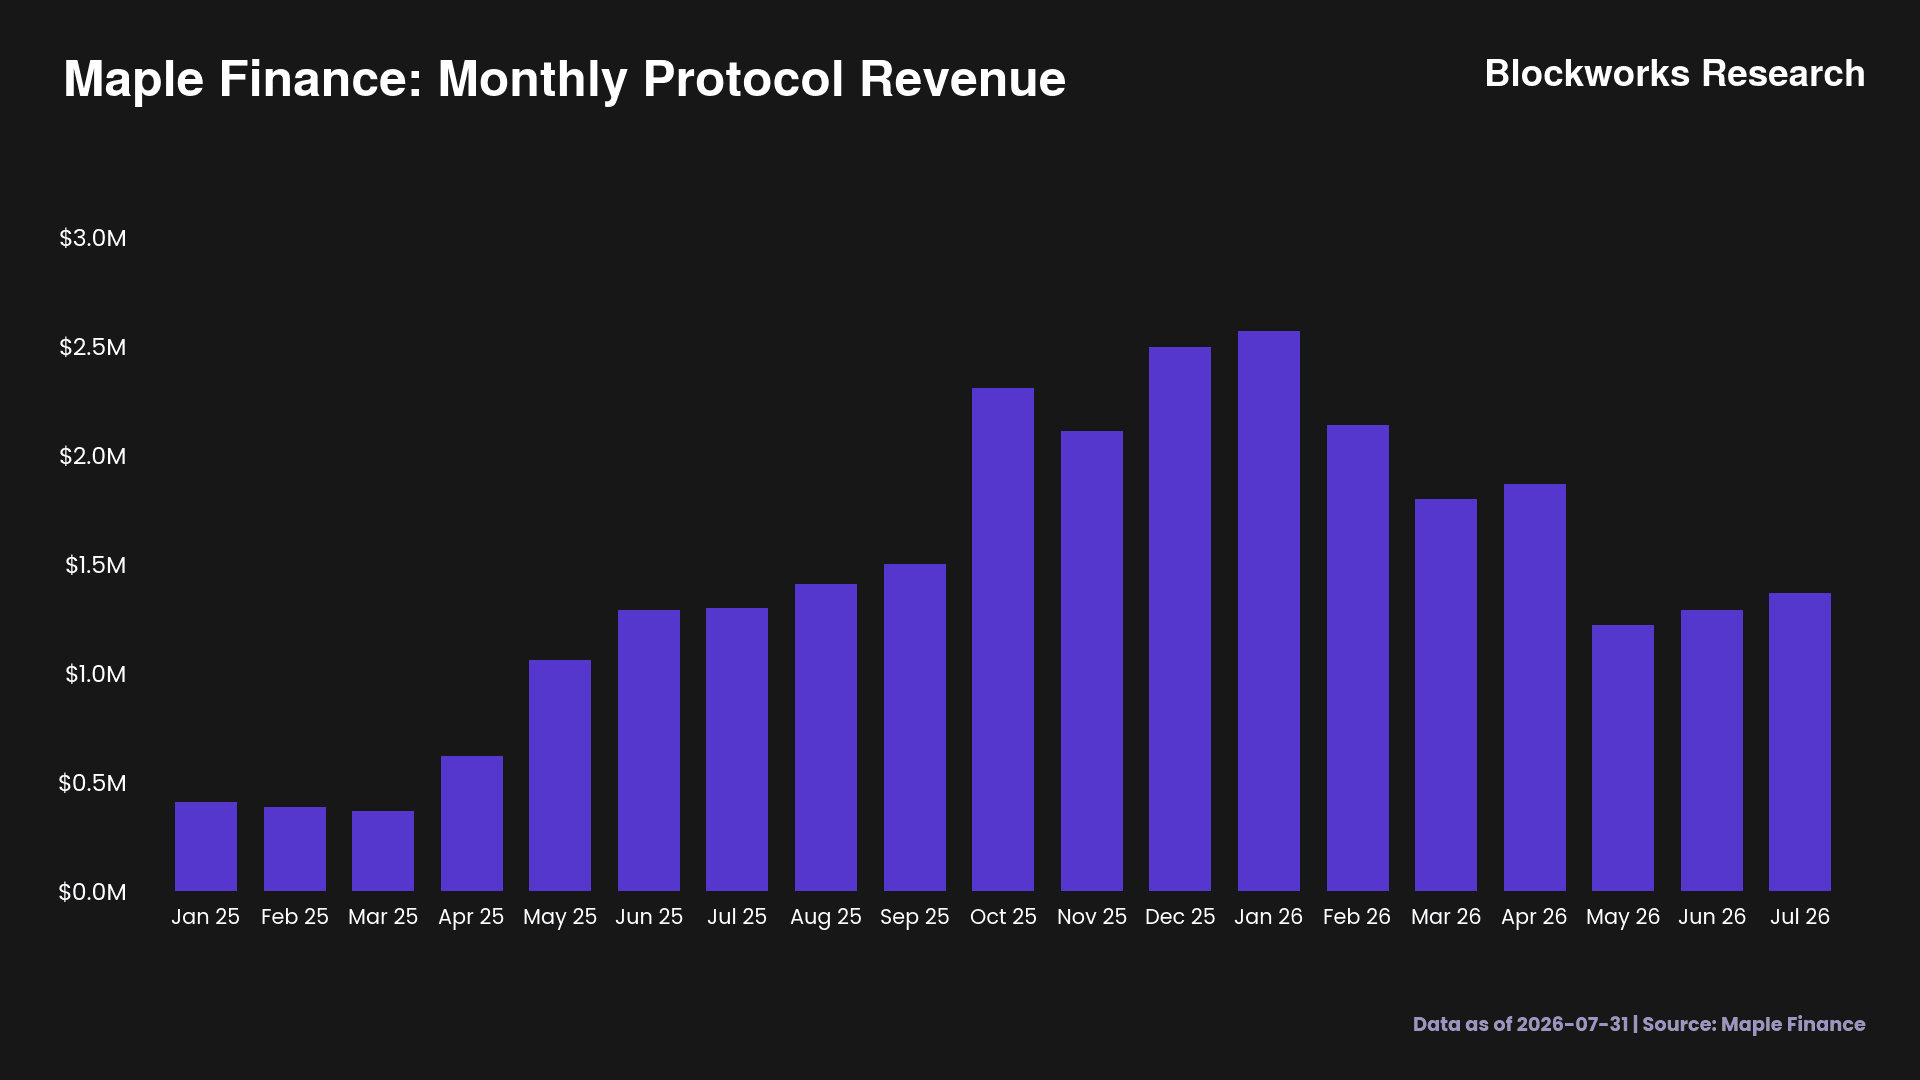
Revenue completes the picture. Despite the lacklustre crypto market for most of the year, Maple has generated close to $1M in monthly revenue since May 2025, with revenue remaining fairly stable since October last year.
This performance stands out because most lending protocols have seen their metrics fall alongside the broader market. Over the same period, Aave’s deposits are down 56.9% and revenue is down 73%, while Kamino’s deposits are down 40% and revenue is down 65%. Morpho is one of the few exceptions, with deposits up 19%.
Part of this difference comes down to asset composition. Aave and Kamino have more ETH- and SOL-denominated activity driven by LST looping, while Morpho and Maple skew more heavily toward stablecoin lending. Their deposits and loans are therefore less sensitive to ETH and SOL price movements.
This helps explain why Maple’s metrics have held up better than those of Aave and Kamino, but it also makes SYRUP’s 52% decline harder to justify. To understand why that gap exists, we first need to look at what has driven Maple’s recent growth.
Distribution, Distribution and Distribution
The key to growing any product is distribution and sitting as close to the end user as possible. Lending protocols are a core pillar of the crypto economy, but have historically been a cyclical business. Most depend on demand for leverage from crypto native users, leaving them highly exposed to market cycles.
That cyclicality is also visible in token performance. With the exception of Morpho, every token in the lending basket is down more than 50% over the past year. MORPHO, meanwhile, is up 5.4%.
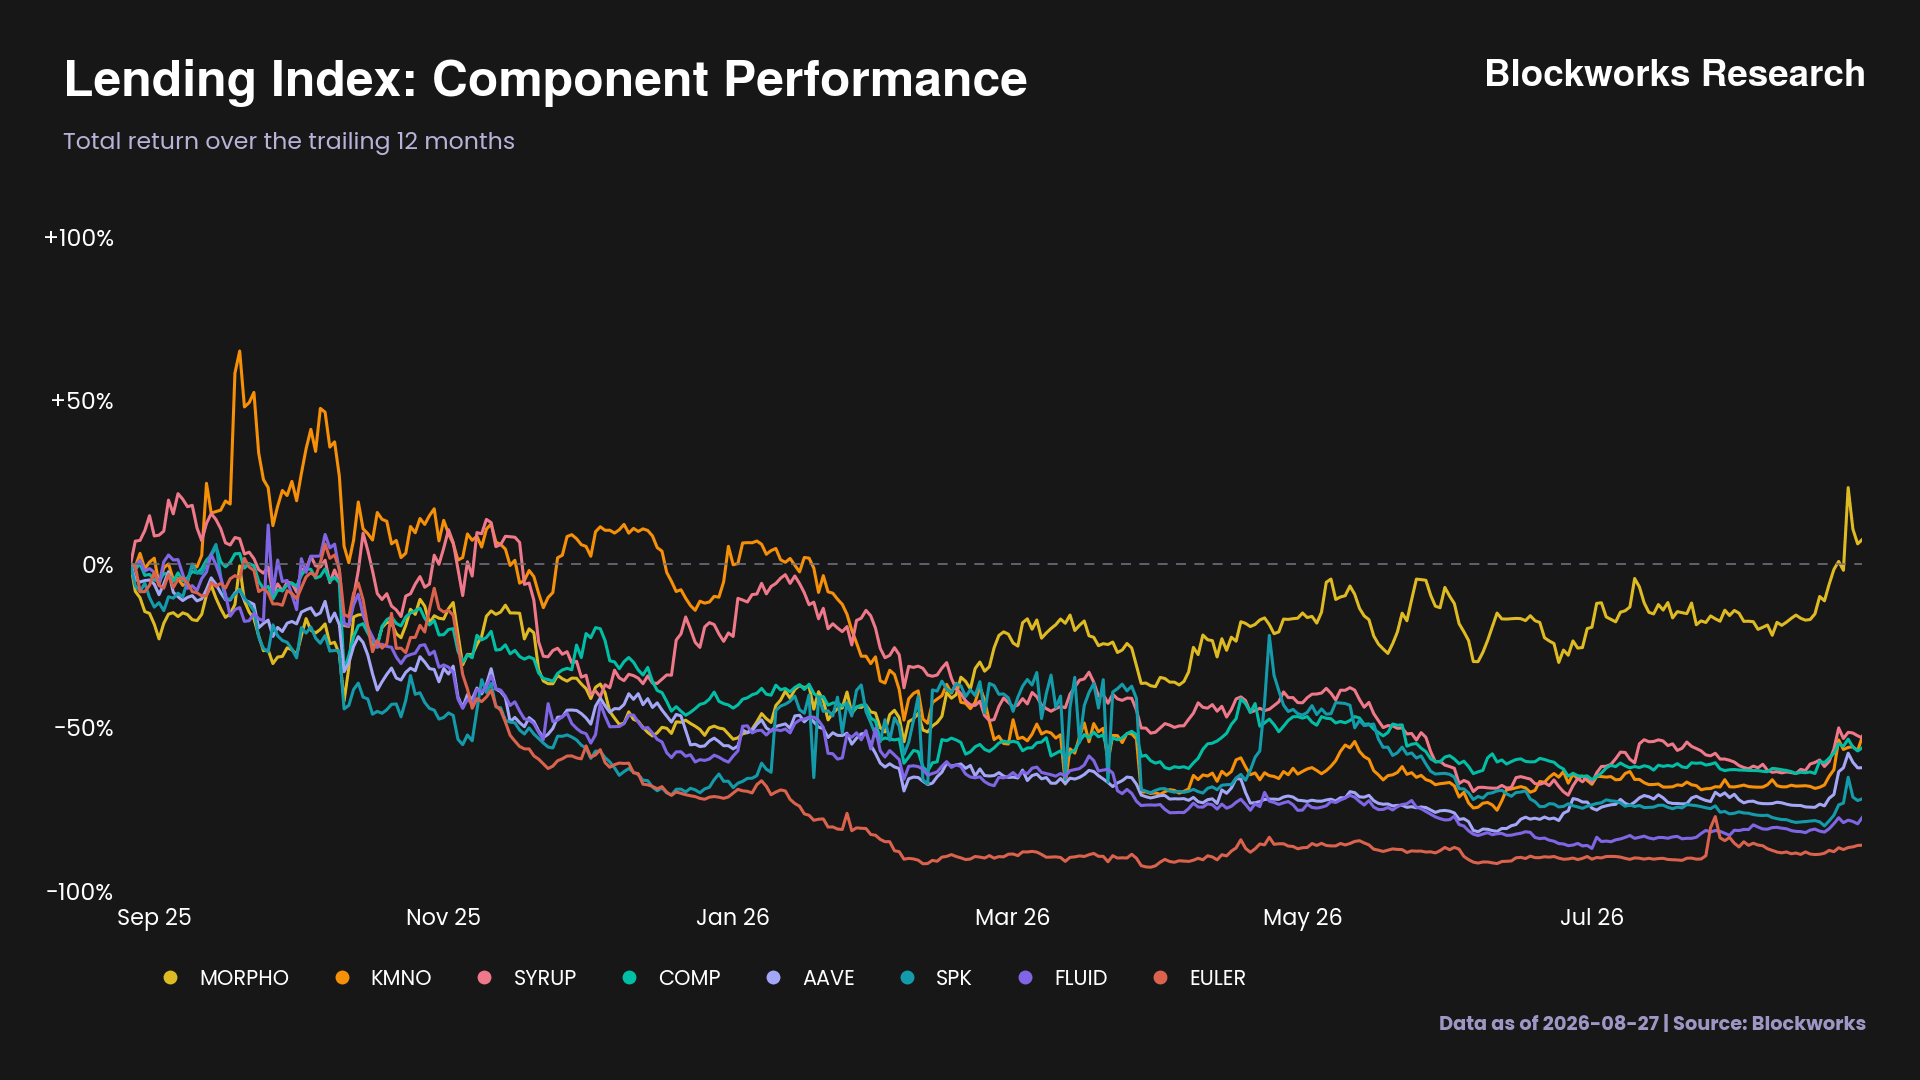
Morpho’s differentiated performance reflects its distribution strategy. Morpho has spent the past year embedding itself as the backend yield product powering savings products for fintechs such as Coinbase, Kraken and, most recently, Robinhood. Retail users can now access onchain yield through a familiar interface without having to touch the clunky blockchain experience underneath.
Maple is following the same playbook, and its early traction on Robinhood shows how large this opportunity could become. The Steakhouse USDG vault powering Robinhood’s savings product has grown to $387M in TVL just two months after launch while offering users an APY of up to 7%.
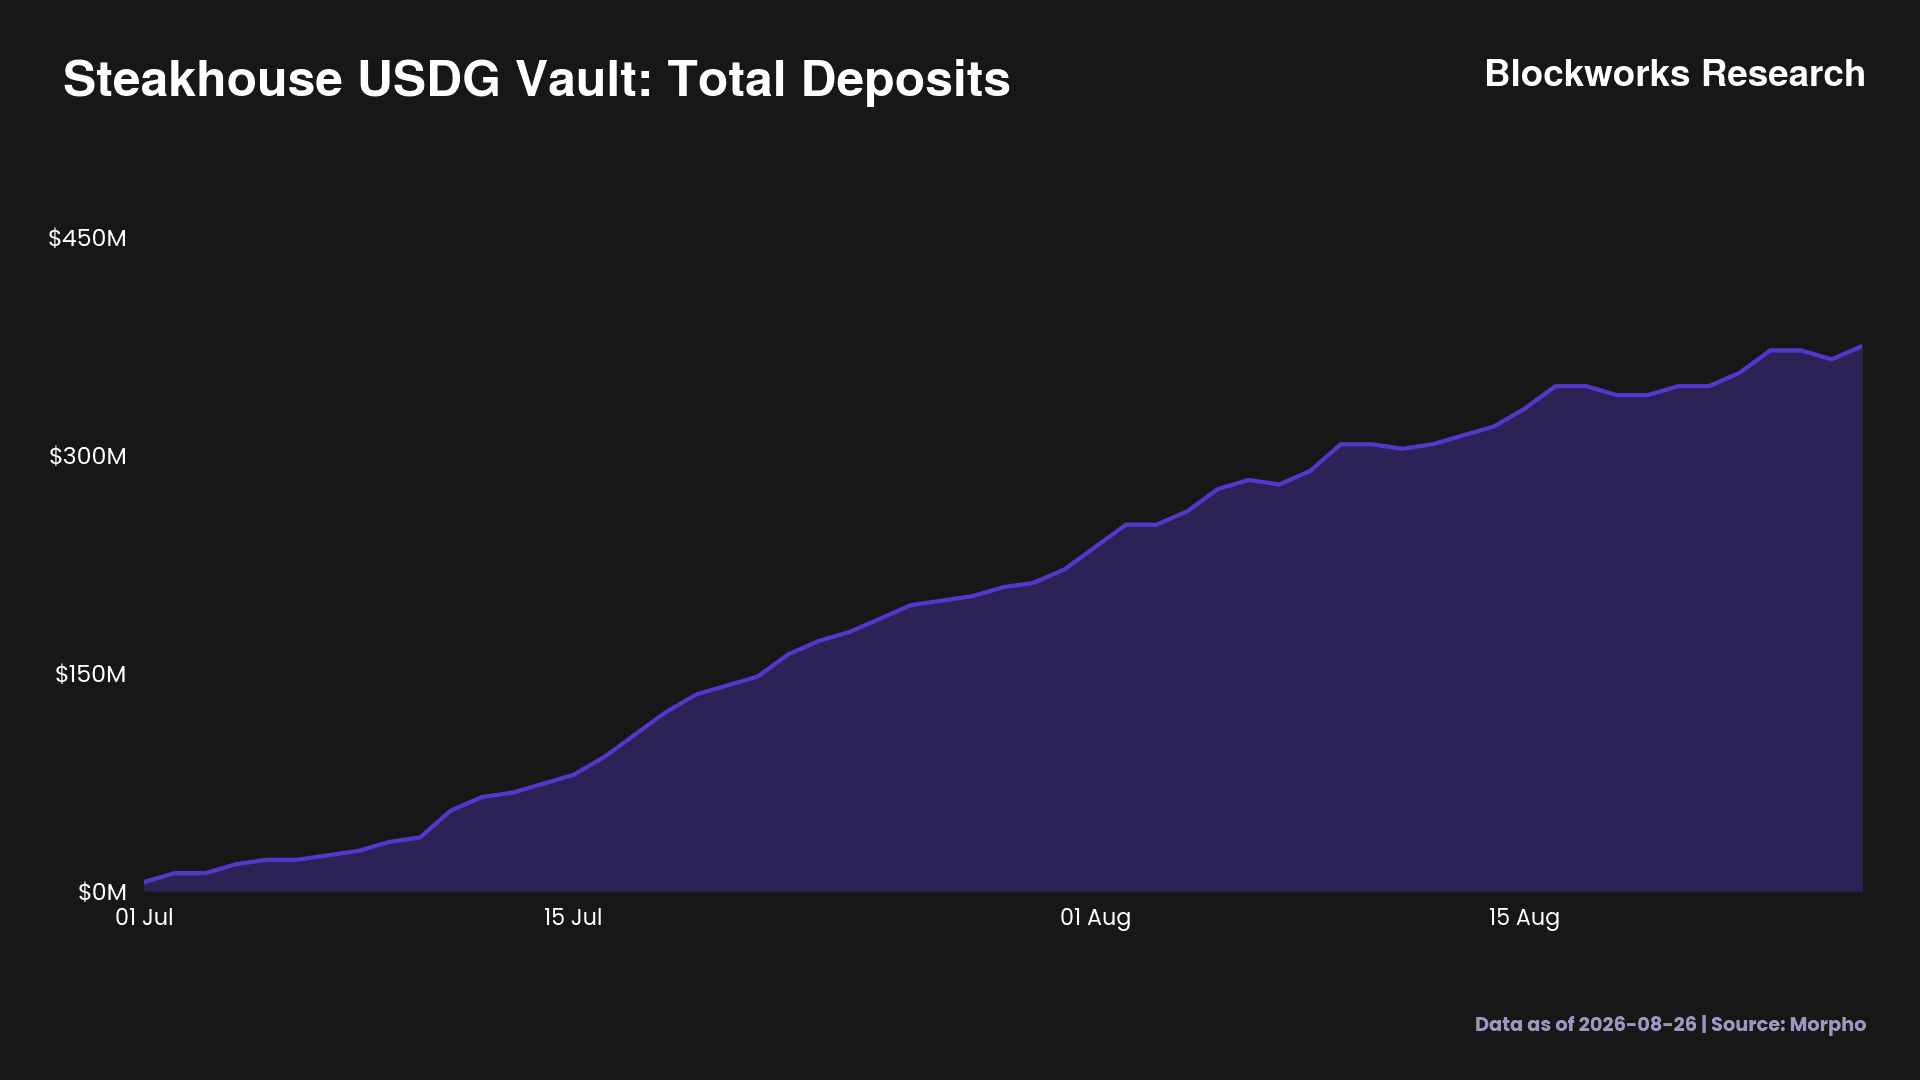
Around 67% of the vault is allocated to USDe and 24% to syrupUSDG. The yield on USDe is currently supported by incentives because USDe itself is the non-yield-generating version of Ethena’s stablecoin. These incentives are unlikely to last forever. As they fade, the vault will need to allocate more capital to higher-yielding assets if it wants to maintain a competitive return.
This is where Maple has an edge. Over the past 30 days, syrupUSDG has offered a 5.01% APY, compared with 4.49% for sUSDe and 3.52% for sUSDS.
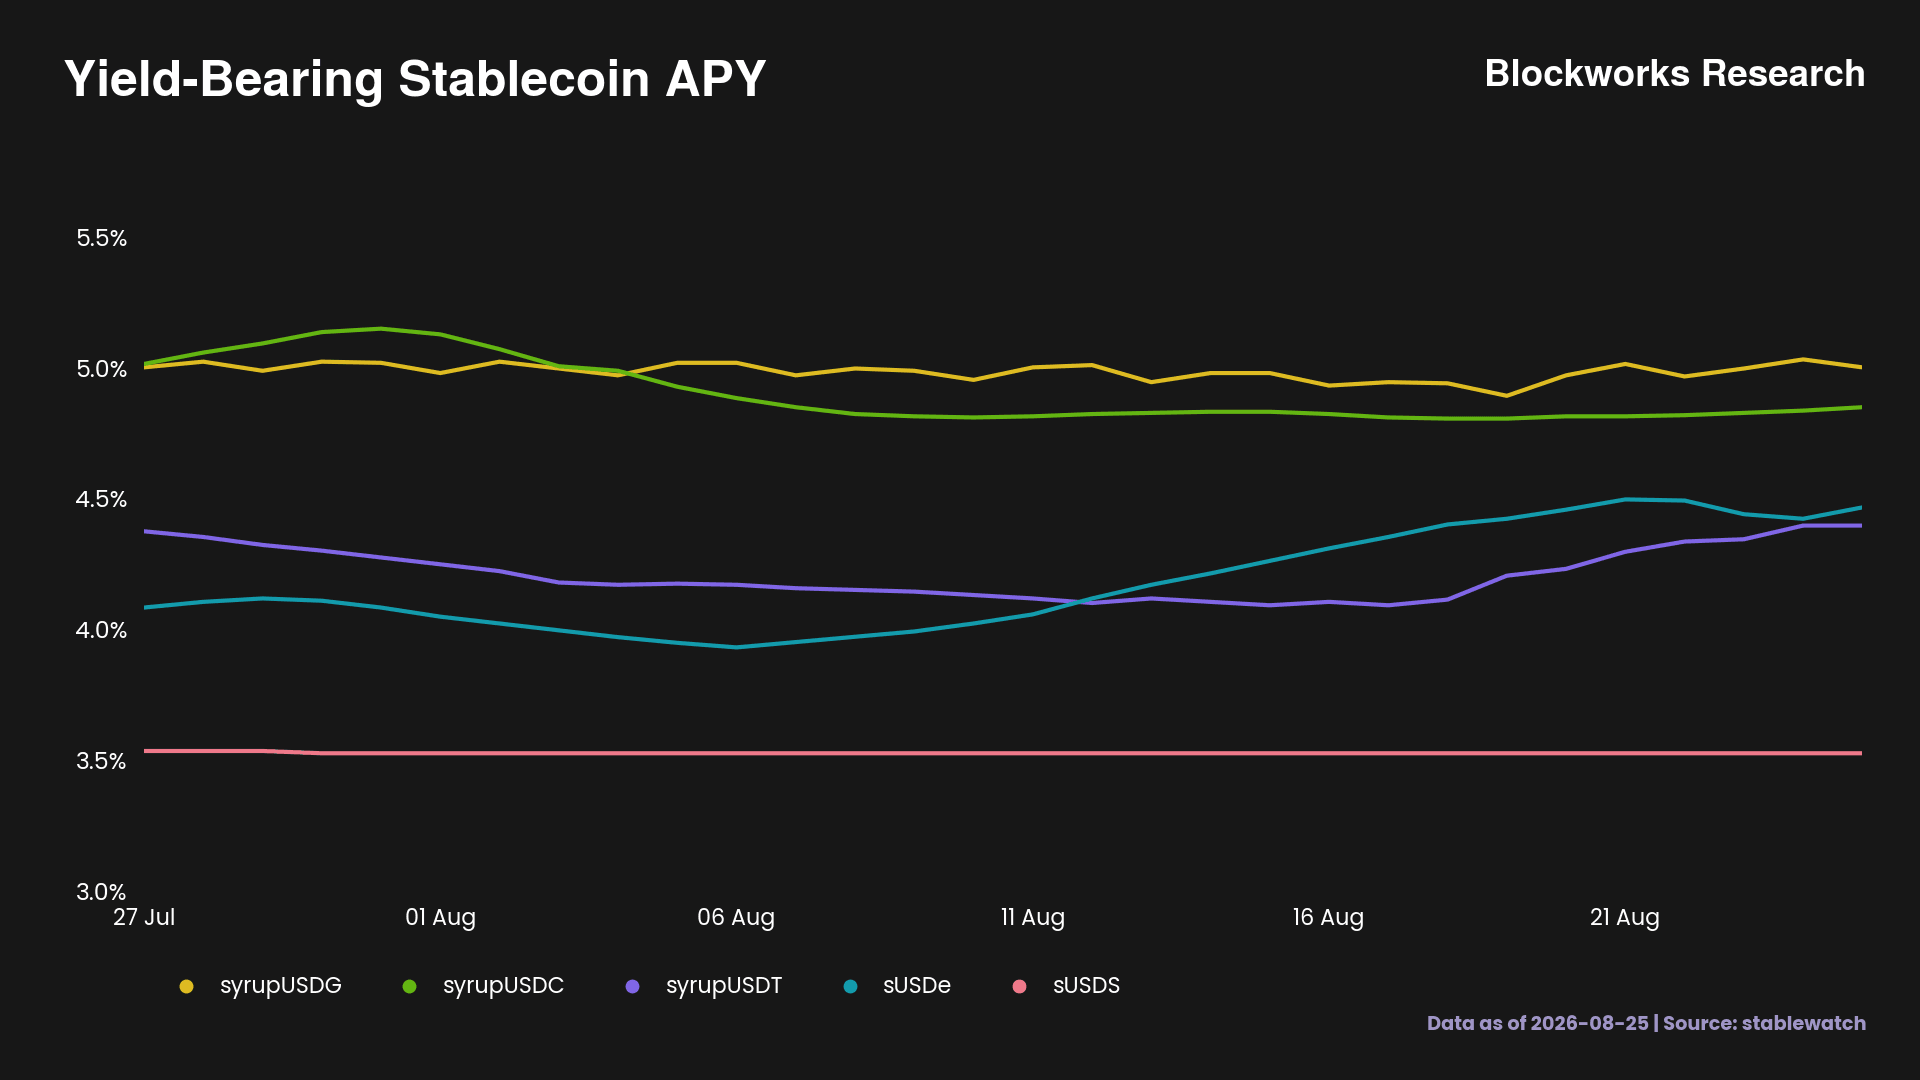
If Robinhood Earn continues to scale while maintaining its yield target, Maple is well positioned to capture a larger share of its deposits. The next question is whether Maple can absorb that capital without compressing yields.
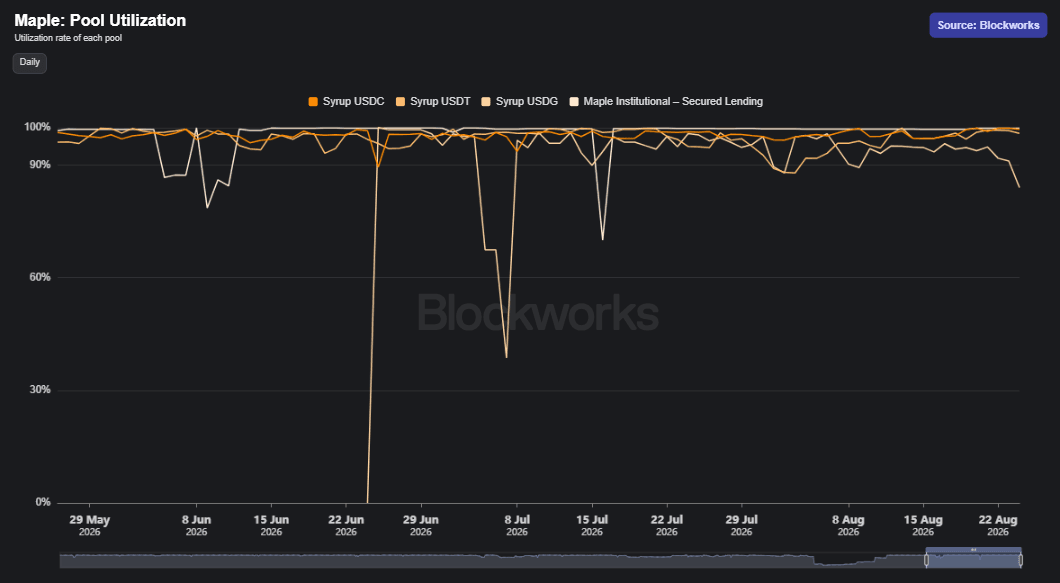
So far, the answer appears to be yes. Outstanding loans have grown alongside deposits, while utilization across syrupUSDC and syrupUSDT remains close to 100%. This indicates that borrower demand has kept pace with deposit growth. The main exception is syrupUSDG, where utilization is slightly lower at 84%.
We have already seen how powerful fintech distribution can be. Following Coinbase’s integration, Coinbase users now account for 56% of USDC deposits and 86% of cbBTC collateral on Morpho. Those assets represent just 1.5% of Coinbase’s assets under custody, yet they have become a major driver of Morpho’s growth.
Robinhood’s opportunity is even larger. The platform has roughly $325B in assets under custody. If just 1.5% eventually flows into Robinhood Earn and 25% of that capital is allocated to Maple, Maple’s deposits would increase by roughly $1.2B, representing around 24% growth from this product alone.
Maple is also widening distribution on the other side of its marketplace. On June 24, it announced an onchain warehouse facility with Kraken to fund the exchange’s OTC lending program. The facility allows Kraken’s institutional clients to borrow against BTC and ETH without selling their holdings, giving Maple a new source of institutional credit demand.
This shows how fintech distribution can support both sides of Maple’s business. Robinhood can bring in retail deposits, while Kraken helps source the institutional borrowers needed to deploy that capital. Since the Kraken partnership was announced, total deposits in Maple Institutional have risen from $200M to $823M.
The team reinforced this focus during its recent quarterly call, highlighting fintech distribution and embedded yield products as key priorities for the second half of the year.
If Maple can replicate even part of Morpho’s success with Coinbase through Robinhood and future partners, its metrics should continue trending higher. Each partnership should also bring more attention to SYRUP, much as fintech distribution did for MORPHO. Maple remains an institutional lender, but it is starting to sit behind savings products used by a much larger audience. We do not think the market fully appreciates the potential scale of this growth channel.
The Ethena Call Option
Another overlooked driver of Maple’s growth is Ethena. In a previous report covering Ethena’s proposed reserve diversification, we argued that institutional lending was its most scalable option for reducing reliance on the basis trade. Institutional lending now accounts for 12% of USDe’s backing, with 62.5% of that capital sitting in Maple Institutional. This amounts to roughly $302M.
Unlike traditional DeFi lending protocols such as Aave, institutional lending platforms allow stablecoin lenders to provide capital directly to KYC-verified trading firms, market makers and hedge funds. More flexible collateral requirements and customized credit arrangements allow lenders to earn a premium over traditional DeFi lending markets.
With Ethena’s TVL currently at $4B, well below its $14.8B peak last September, the relationship functions as a call option for Maple. If crypto markets continue to strengthen, higher funding and lending yields should make sUSDe yields more attractive and support a recovery in TVL.
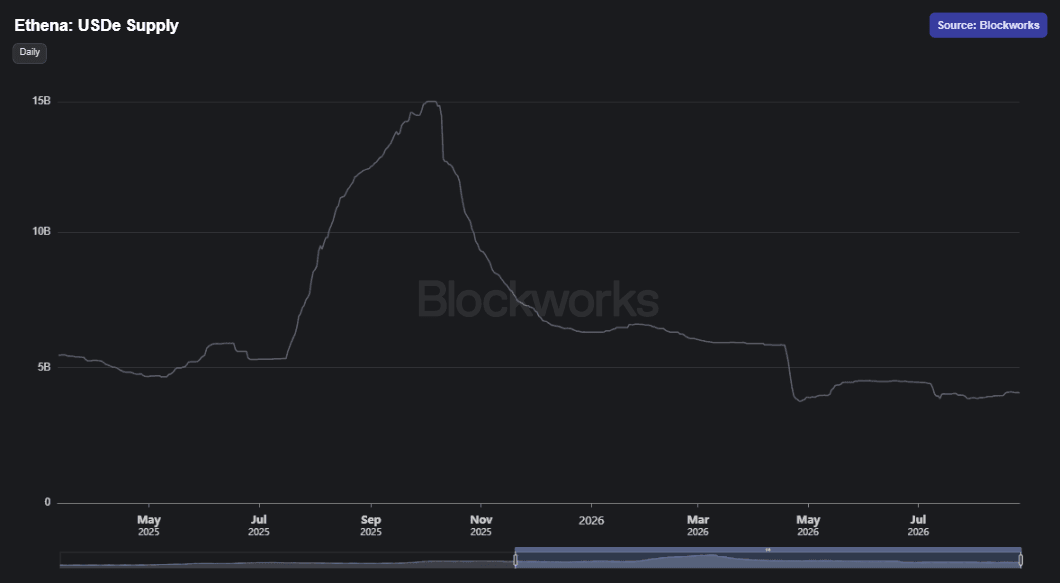
If Maple retains its current share of Ethena’s institutional lending allocation, part of any recovery in USDe should flow into Maple Institutional. As highlighted in our previous piece, institutional lending gives Ethena an important source of diversification away from its crypto and RWA basis trades.
We expect the strategy to become a sizable part of Ethena’s backing and a key source of future growth for Maple. If Maple remains the leading venue for this capital, it could provide a scalable source of deposits and revenue while further differentiating Maple from traditional DeFi lenders.
Buybacks Become Predictable
Revenue-funded buybacks were already in place before MIP-021. They initially flowed to SYRUP stakers, before MIP-019 ended staking rewards and directed 25% of protocol revenue to the Syrup Strategic Fund. However, MIP-019 did not specify how much of that allocation had to be used for buybacks rather than cash and other reserves.
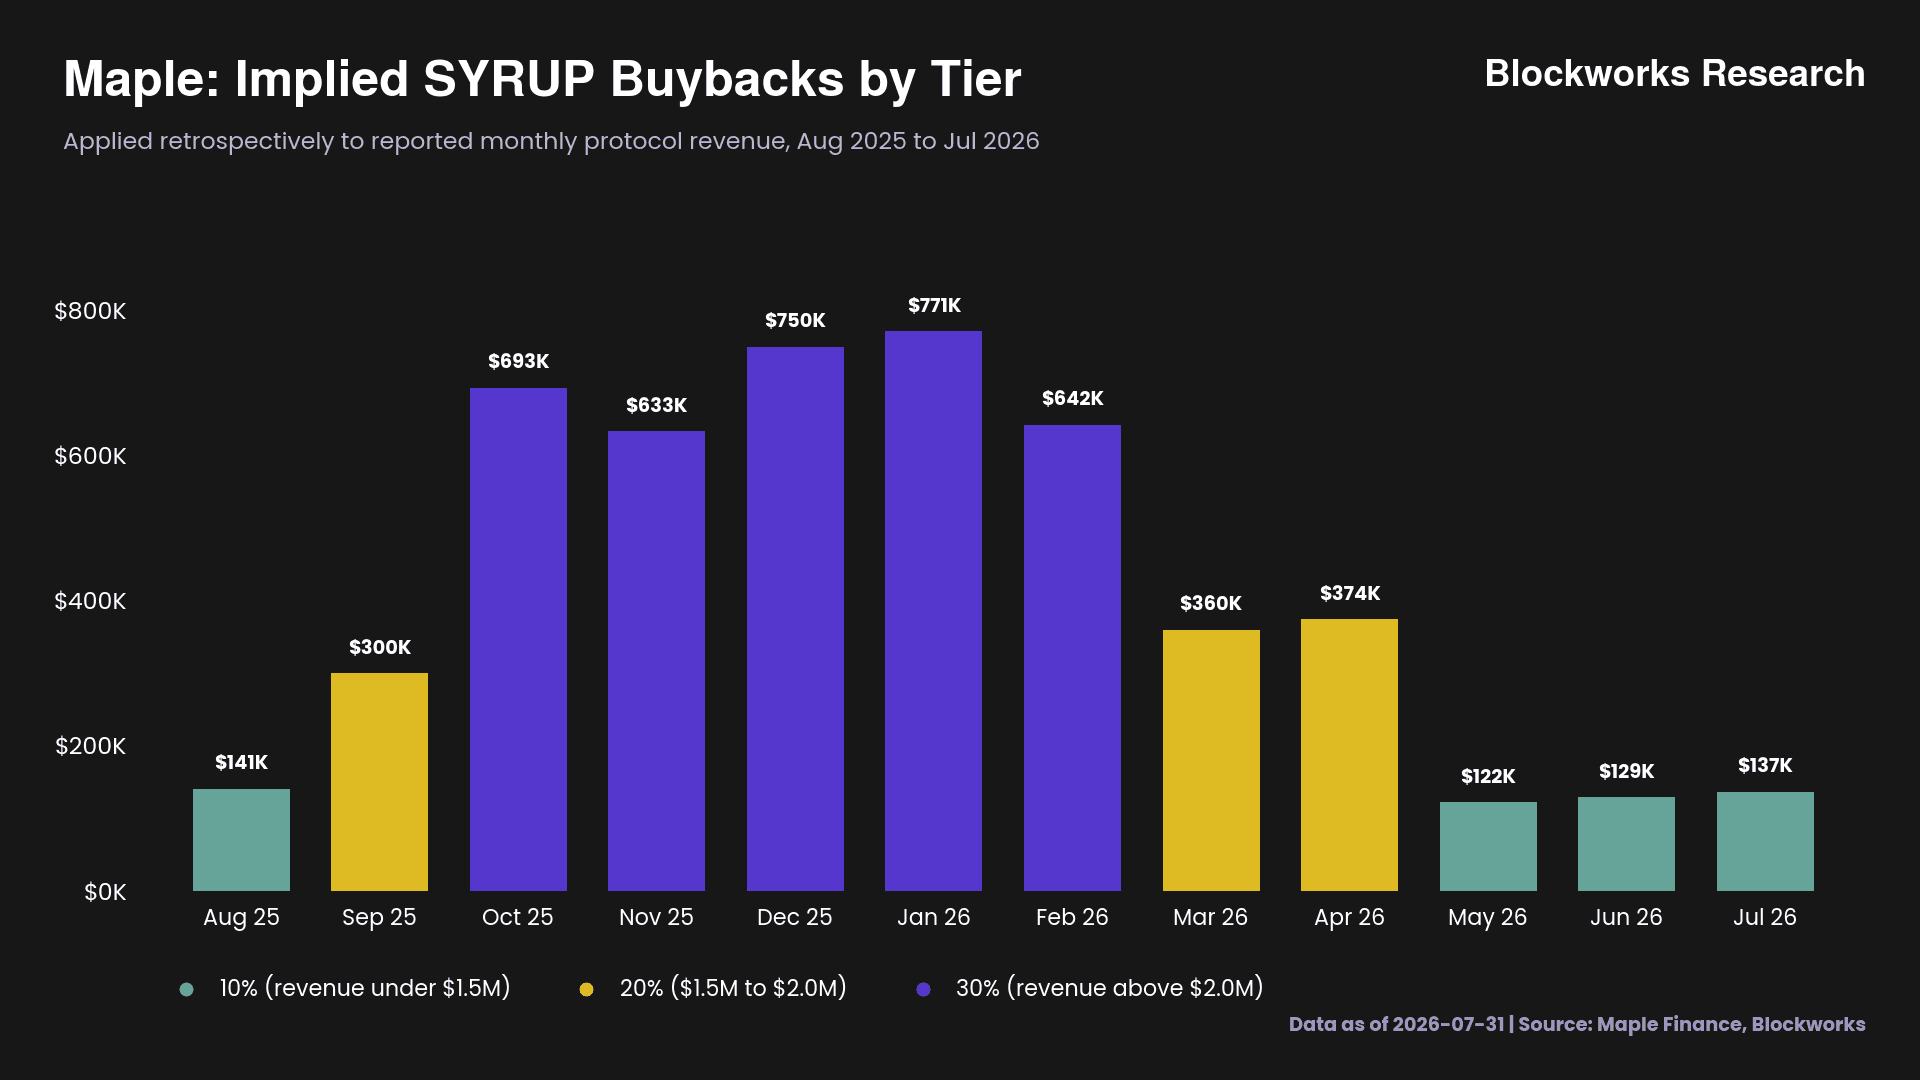
MIP-021 replaces that discretion with a rules-based framework. Under the proposal, 10% of monthly net revenue is directed to buybacks when Maple earns less than $1.5M, rising to 20% between $1.5M and $2M and 30% above $2M. The purchased SYRUP remains in the Strategic Fund.
Had the framework been in place over the past year, $5.1M of Maple’s $22.1M in revenue would have been used to buy back SYRUP, while the remaining $17M would have been reinvested into growth.
We view the current buyback allocation as appropriate for Maple’s growth stage. At this stage, we would rather see Maple prioritize distribution, institutional partnerships and loan book growth.
This also matches the team’s message during its recent quarterly call, where expanding distribution remained the top priority. If Maple executes, today’s smaller buybacks should grow alongside revenue and become a much larger source of demand for SYRUP over time.
The Rerating Case
From a valuation standpoint, annualizing the past 30 days of interest generated and revenue suggests that SYRUP is between 33% and 65% undervalued relative to the median multiple of its peers.
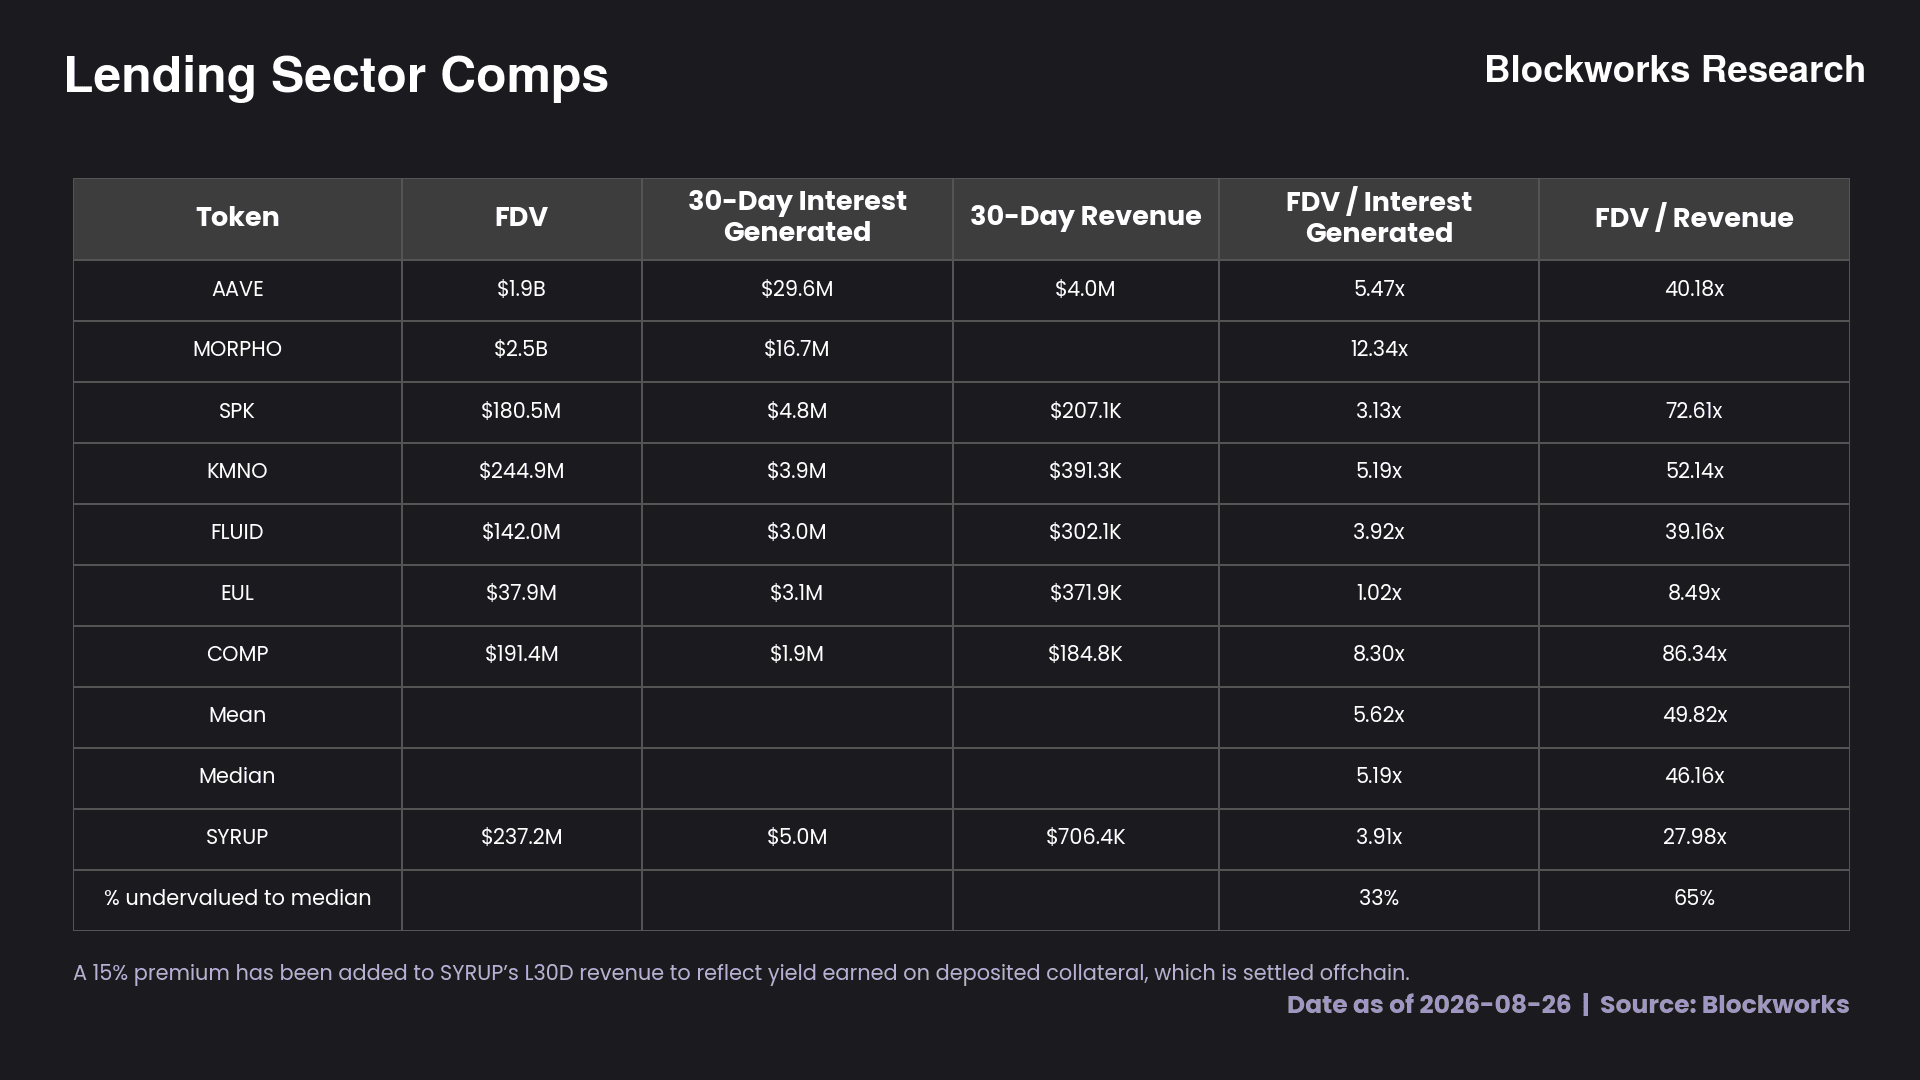
That discount looks too wide given how Maple’s distribution is developing. Robinhood and Ethena can bring more capital into the protocol, while Kraken and future institutional partners can help source the borrowers needed to deploy it. Growing both sides matters. Deposits add little if borrowing demand cannot keep up, while new borrowers cannot support growth without a steady source of capital.
Morpho provides the closest comparison. Its premium reflects how successfully it has used partnerships with Coinbase, Kraken and Robinhood to reach users outside of DeFi. Maple is earlier in that process, but the same playbook is beginning to show in its deposits and loan book. Maple also has buybacks live, giving SYRUP holders a clearer way to benefit if these partnerships translate into higher revenue.
We believe Maple already warrants a valuation closer to the median of its peers, which would imply 33% to 65% upside. If Robinhood Earn continues to scale, Kraken brings in more borrowing demand and Ethena drives deposits, a multiple closer to Morpho becomes easier to justify. Additional fintech partnerships, which we expect to be announced over the coming quarter, would strengthen the rerating case and serve as a strong catalyst from both a narrative and fundamental standpoint.
Risks to the Thesis
The biggest risk to our thesis is that Maple’s growth in deposits and loans fails to translate into higher revenue. Supply rates across Maple’s pools have been compressing, which explains why revenue has plateaued in recent months even as deposits and outstanding loans continued to grow.
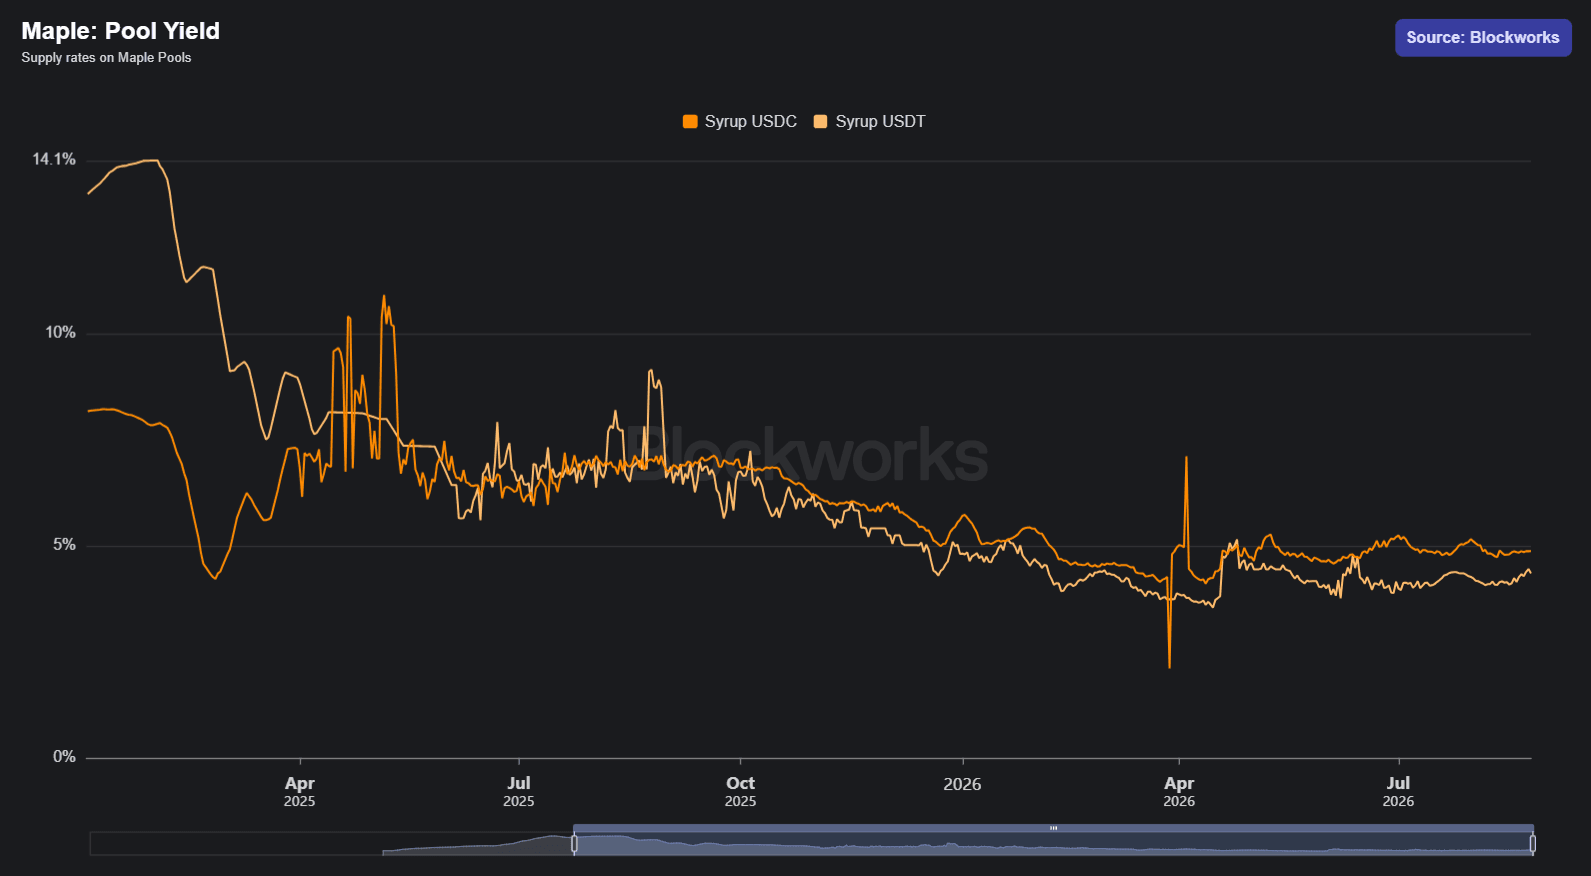
As institutional lending has matured, its yields have moved closer to those available across DeFi. Traditional lending protocols now offer fixed-term loans that can be tailored to institutional borrowers, reducing part of the premium Maple previously earned. Maple should still command some premium, but it will likely be narrower and more sensitive to market conditions and borrowing demand. If rates remain low, revenue and buybacks could grow more slowly than deposits.
Maple’s distribution strategy also creates some partner concentration. Robinhood and Ethena are becoming important sources of capital, meaning changes to Robinhood’s vault allocations or Ethena’s backing strategy could slow deposit growth.
Another risk is that the market continues to reserve premium multiples for clear category leaders. Protocols such as Hyperliquid and Pump benefit from greater liquidity, mindshare and defensibility, which helps explain why they trade above their peers. Morpho currently holds a similar position in fintech distribution, and Maple may continue trading at a discount until it proves that its recent partnerships can be repeated at scale.
That said, crypto markets remain inefficient and patience is often rewarded. The market was slow to recognize the change in EtherFi’s business model, despite the shift appearing in the data well before the token rallied. We believe the setup for SYRUP is similar. Maple’s institutional lending growth, fintech distribution and Ethena flows are already visible, but the market may only begin to value them as they become a larger part of deposits and revenue.
Conclusion
Maple has spent the past year growing while most lending peers contracted. Deposits and loans are higher, distribution has expanded through Robinhood and Kraken, Ethena provides another source of upside, and buybacks are now live. Yet SYRUP remains down 52% over the same period and trades well below peer valuations.
Revenue remains the missing piece. Rate compression could delay the rerating, but Maple now has several channels that can drive its next phase of growth. Buybacks also ensure that any recovery in revenue creates direct demand for SYRUP.
We believe the current discount is too wide. With one or two more fintech partnerships or a return to revenue growth, we expect Maple to come back into the spotlight and much of the valuation gap to close, setting SYRUP up for a strong rebound through the next leg of the bull market.
The information contained in this report and by Blockworks Inc. and related affiliates is for general informational purposes only and is not intended to provide legal, financial, or investment advice. The report should not be construed as an offer or solicitation to buy or sell any security, token, or financial instrument and does not represent any recommendation or endorsement of any investment or financial product or service. Blockworks Inc. and related affiliates are not registered as a securities broker-dealer or an investment advisor in any jurisdiction or country.